The Local Lowdown: December 2023

Michelle Kim  |  January 1, 2024
The Local Lowdown: December 2023

The Local Lowdown

Quick Take:
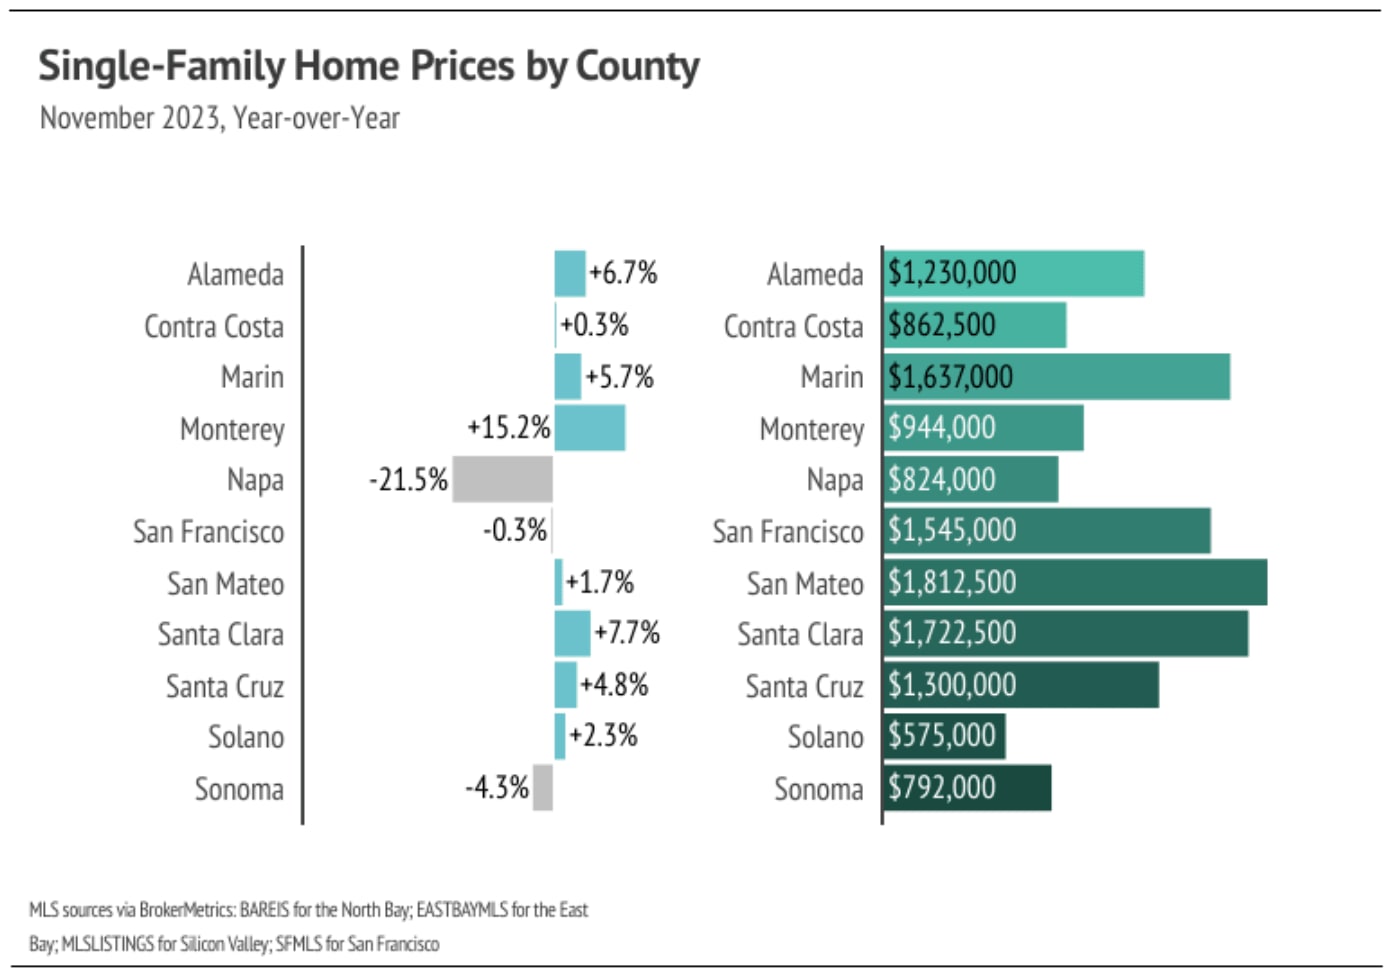
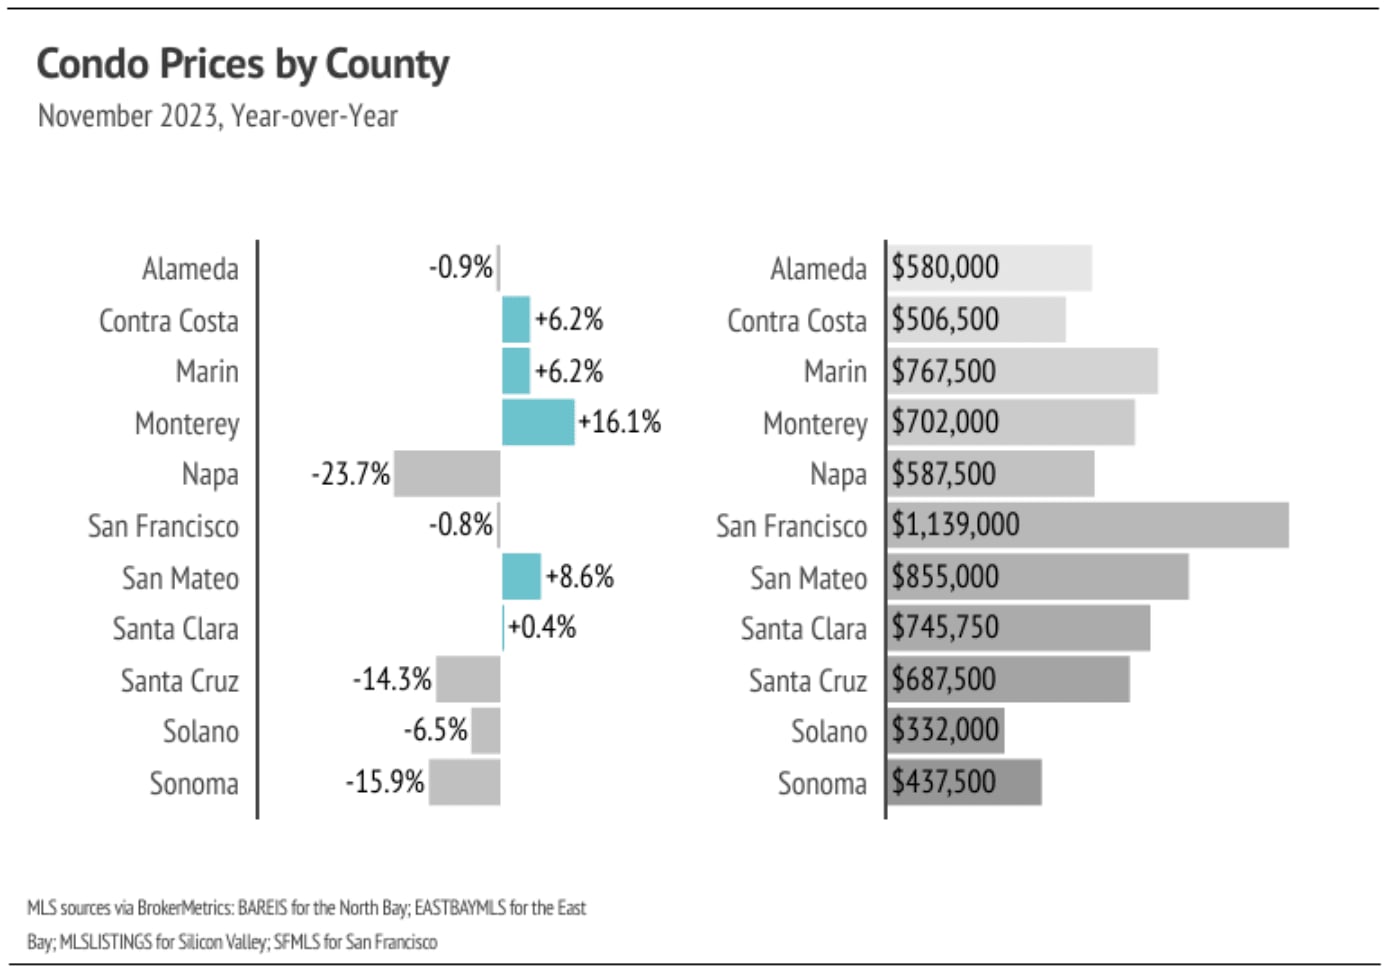
  • Year over year, the median single-family home prices rose across most Bay Area counties in November, staying in line with the six-month horizontal price trend. We expect that trend to continue until interest rates drop and more sellers come to the market.
  • Active listings, sales, and new listings fell month over month for single-family homes and condos. Inventory will likely decline more over the next few months before rising in the spring.
  • Months of Supply Inventory indicates the single-family home market still strongly favors sellers, but the condo market has shifted toward a balanced market. It’s common for MSI to trend higher in the fall and winter, when fewer buyers are in the market and sales slow.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
 

Price growth slows across most of the Bay Area

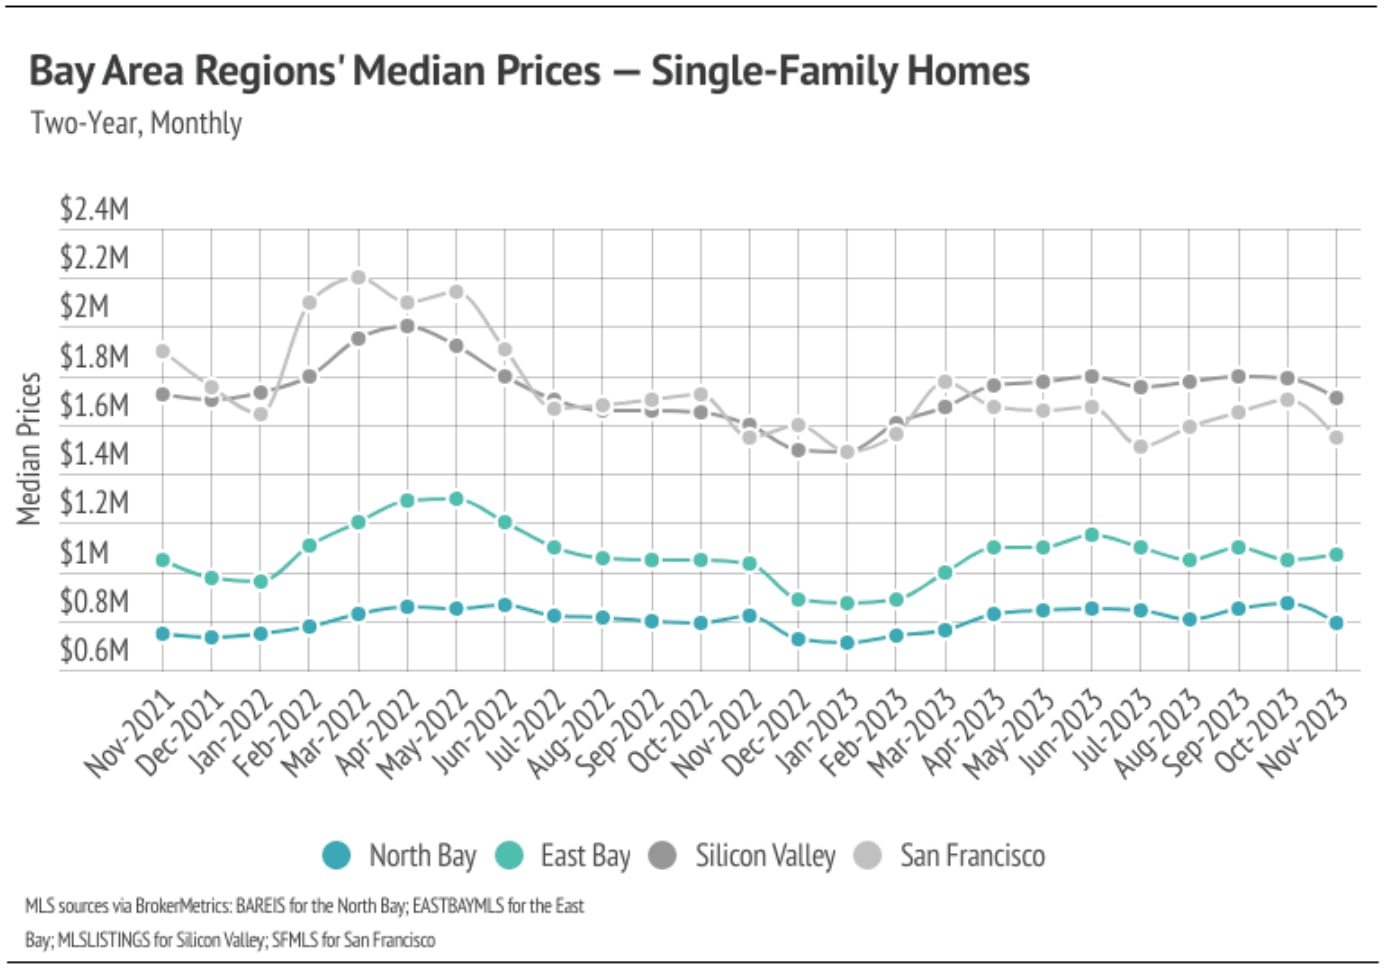
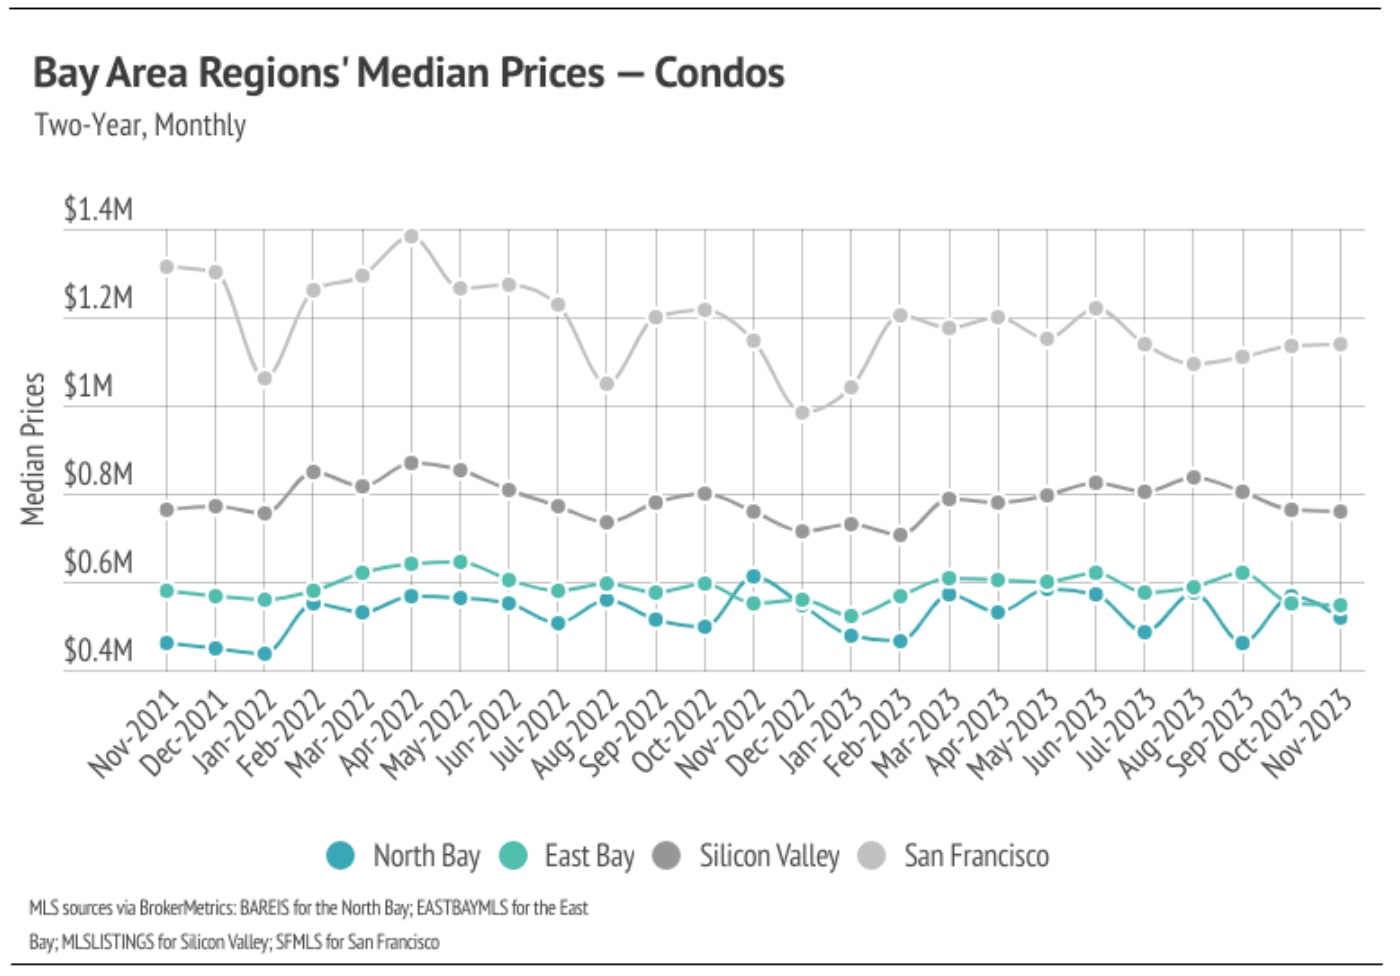
In the Greater Bay Area, home prices haven’t been largely affected by rising mortgage rates after the initial period of price correction from April 2022 to January 2023. In November, the median prices across most Bay Area counties were only slightly below their record highs with the exception of San Francisco, which has not yet seen the price bounce. We expect prices to remain fairly stable in the winter months, but as interest rates decline and more sellers come to the market, prices will almost certainly rise in the first half of 2024. More homes must come to the market in the spring and summer to get anything close to a healthy market.
 
High mortgage rates soften both supply and demand, so ideally, as rates fall, far more sellers will come to the market. Rising demand can only do so much for the market if there isn’t supply to meet it. Unlike 2023, 2024 inventory has a much better chance of following more typical seasonal patterns.
 

Inventory, sales, and new listings declined month over month

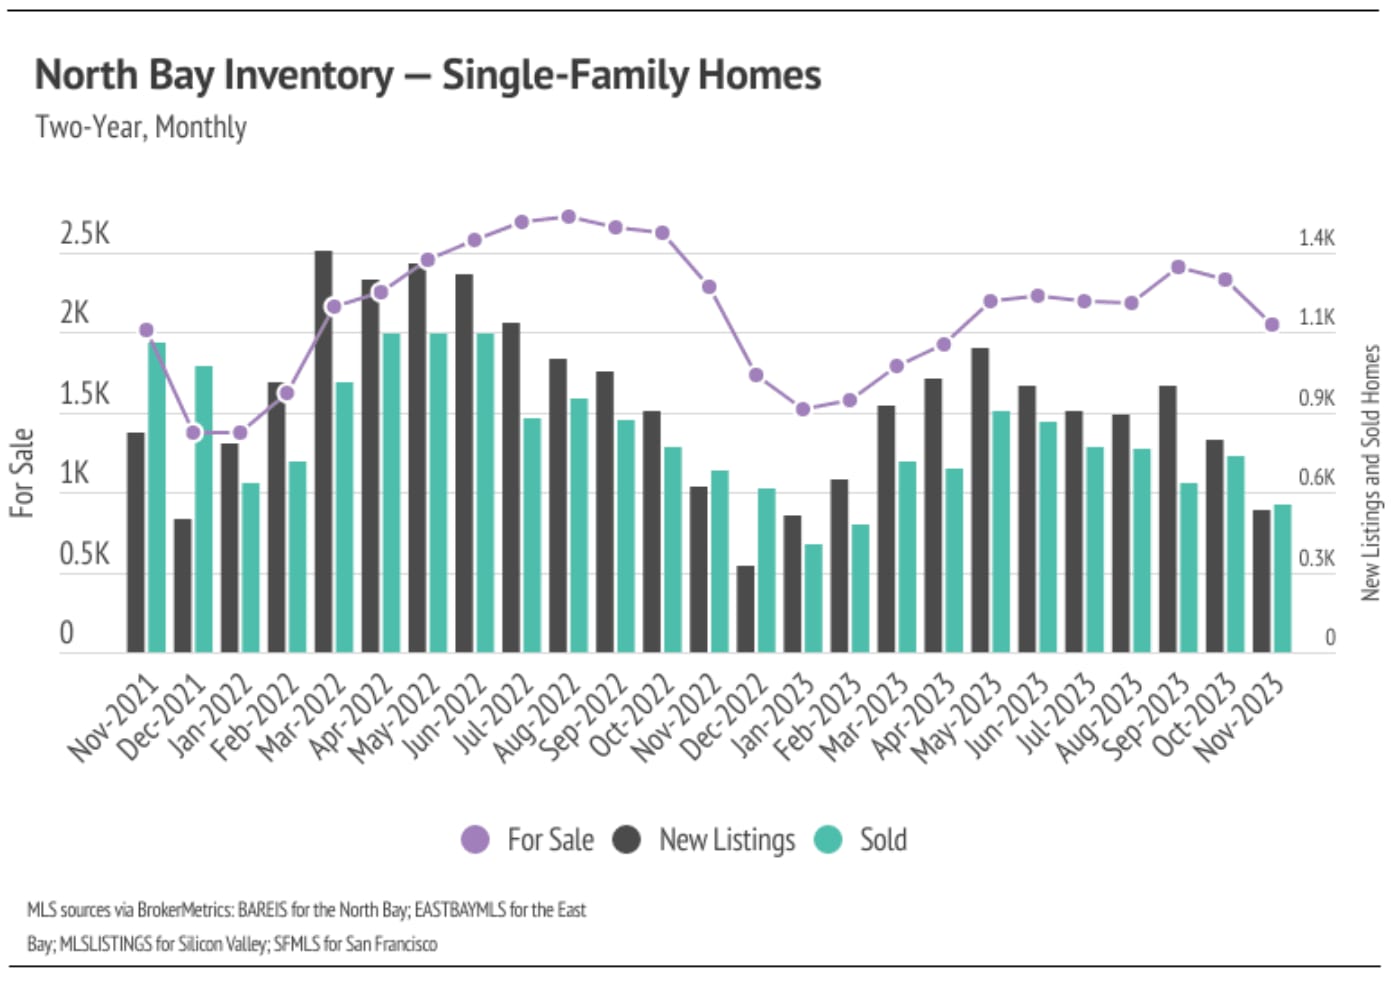
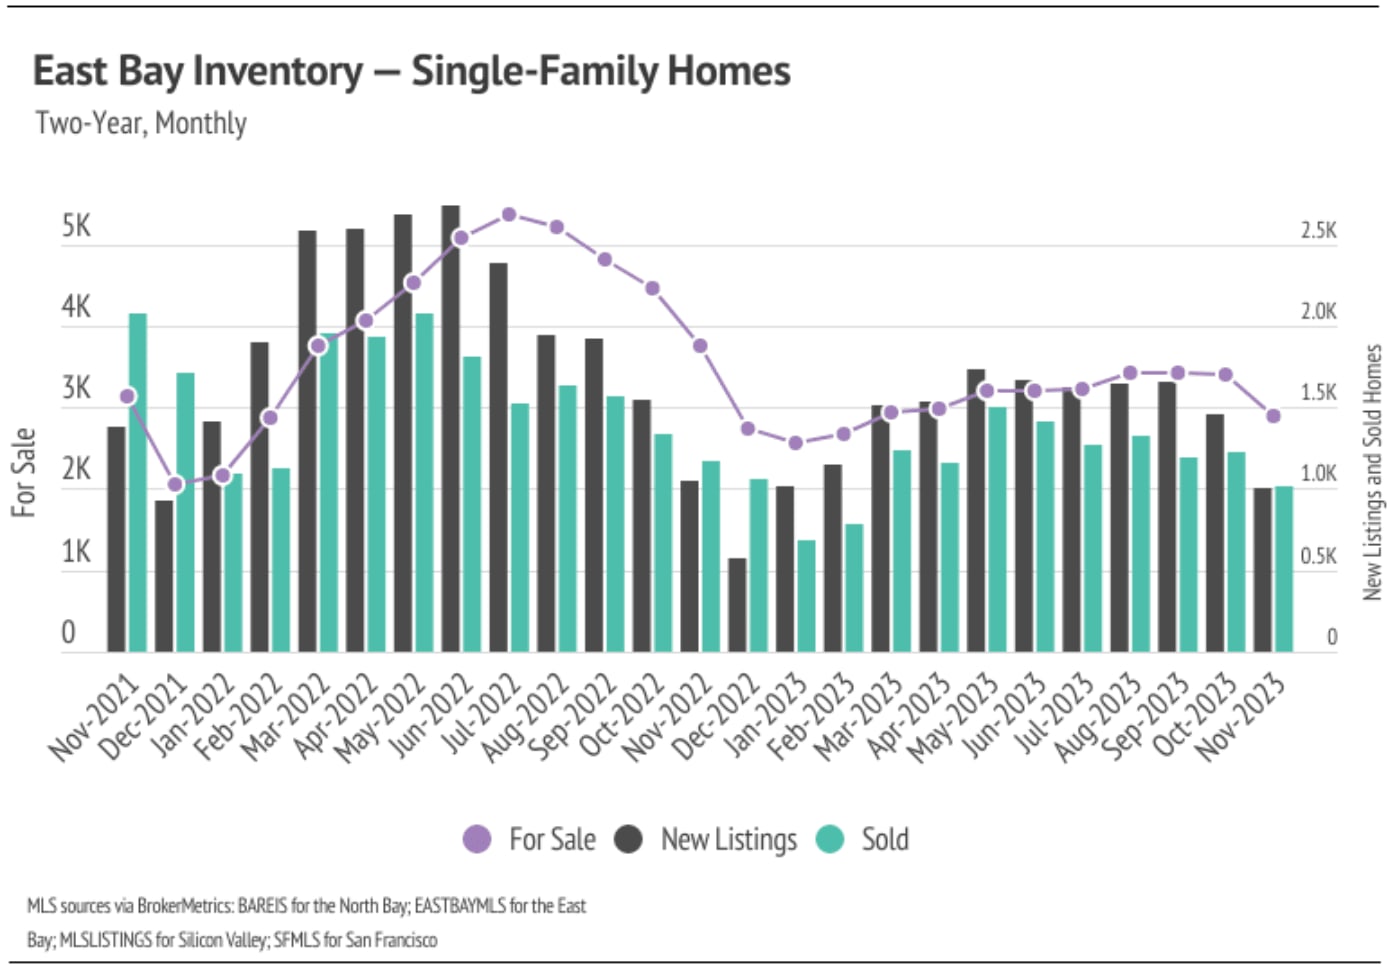
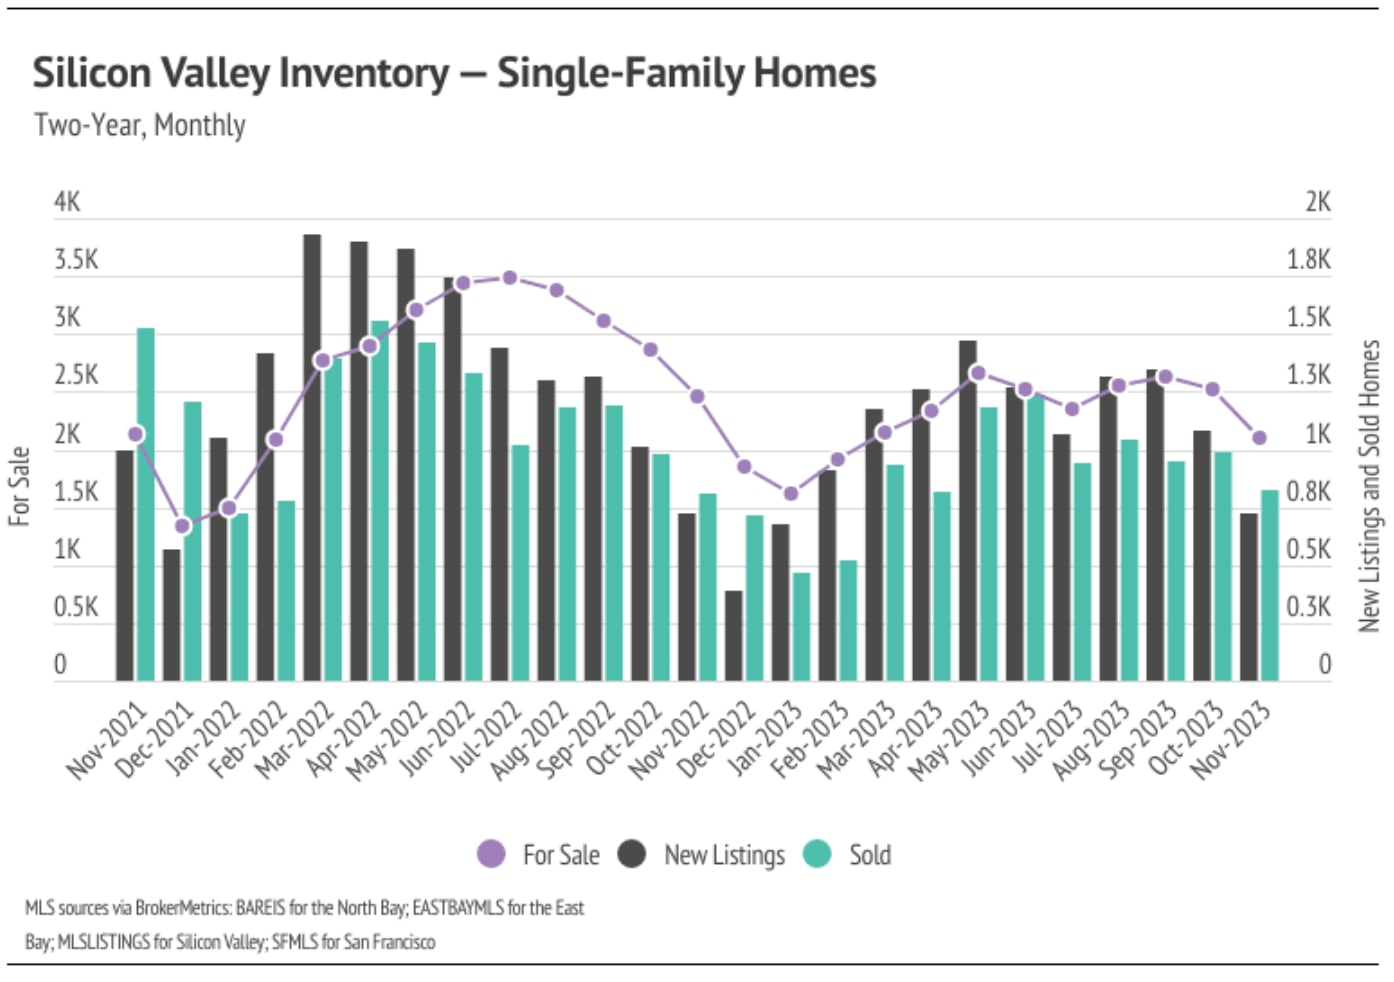
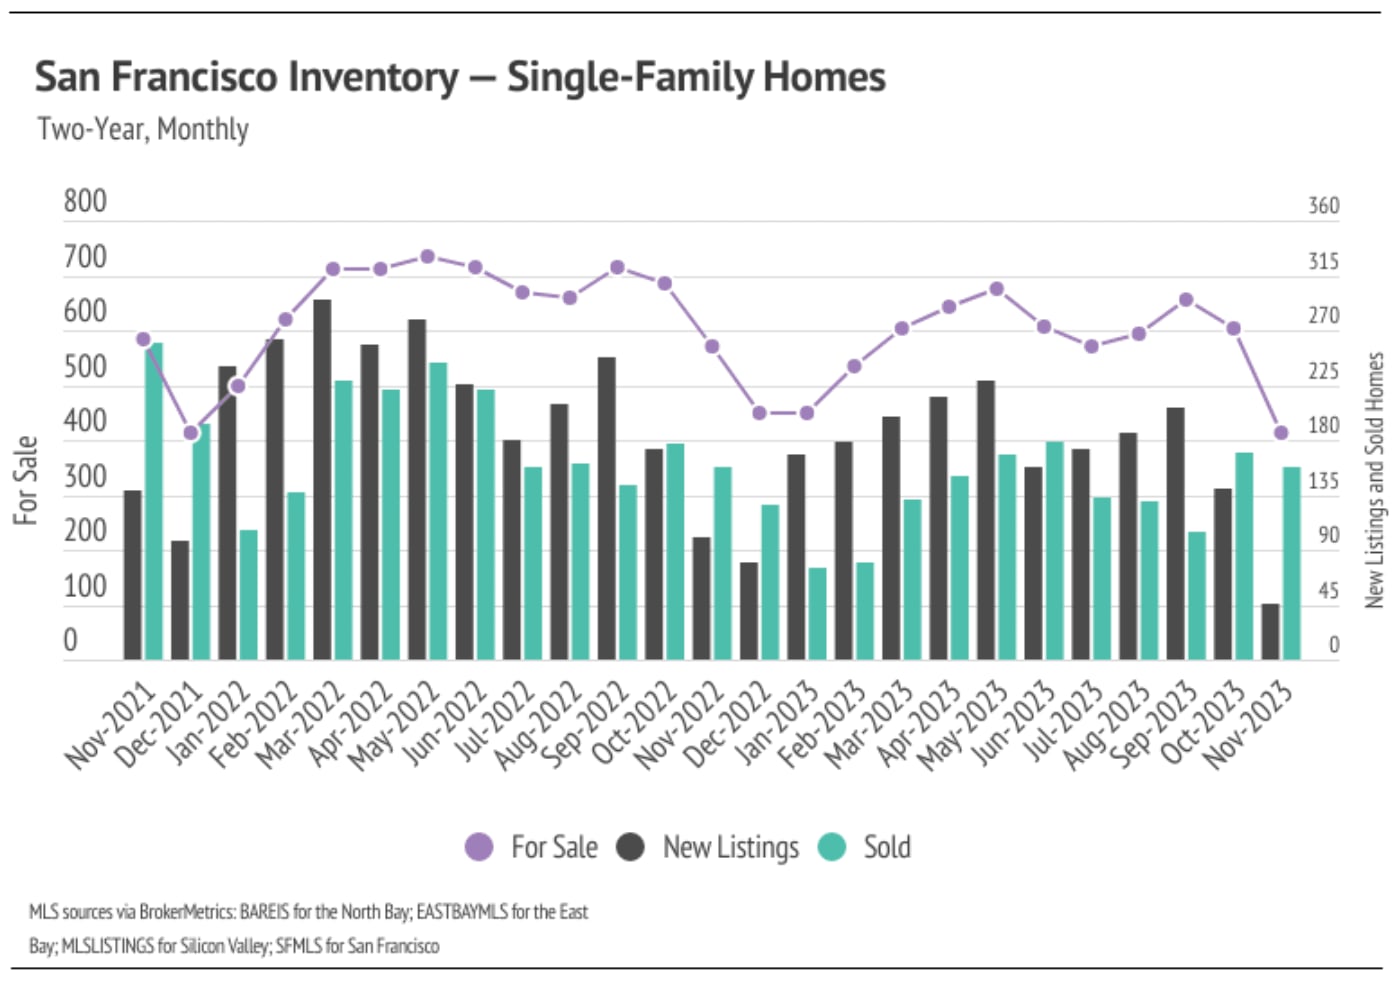
Single-family home and condo inventory barely increased at all this year, which is far from the seasonal norm. In 2023, inventory didn’t have anything resembling the typical sine wave, since far fewer sellers came to the market, especially in the first half of the year, and the low inventory and fewer new listings have slowed the market considerably. New listings have been exceptionally low, so the little inventory growth this year was driven by softening demand. In fact, new listings in San Francisco were so low in November that inventory declined to a record low. Typically, inventory peaks in July or August and declines through December or January. In November, inventory, sales, and new listings dropped across Bay Area markets, which is normal this time of year. With the current low inventory levels, the number of new listings coming to market is a significant predictor of sales. Month over month, new listings fell 32% and sales declined 19%. Year over year, sales and new listings are down 11% and 3%, respectively.
 
As demand slows, buyers are gaining slightly more negotiating power and paying less than asking price on average. The average seller received 95% of list in January, which grew to 102% by May. From May to November, the average seller received around 100% of list price. Inventory will almost certainly remain historically low for the next few months, and buyer competition will ramp up meaningfully in the spring, which will create price support.
 

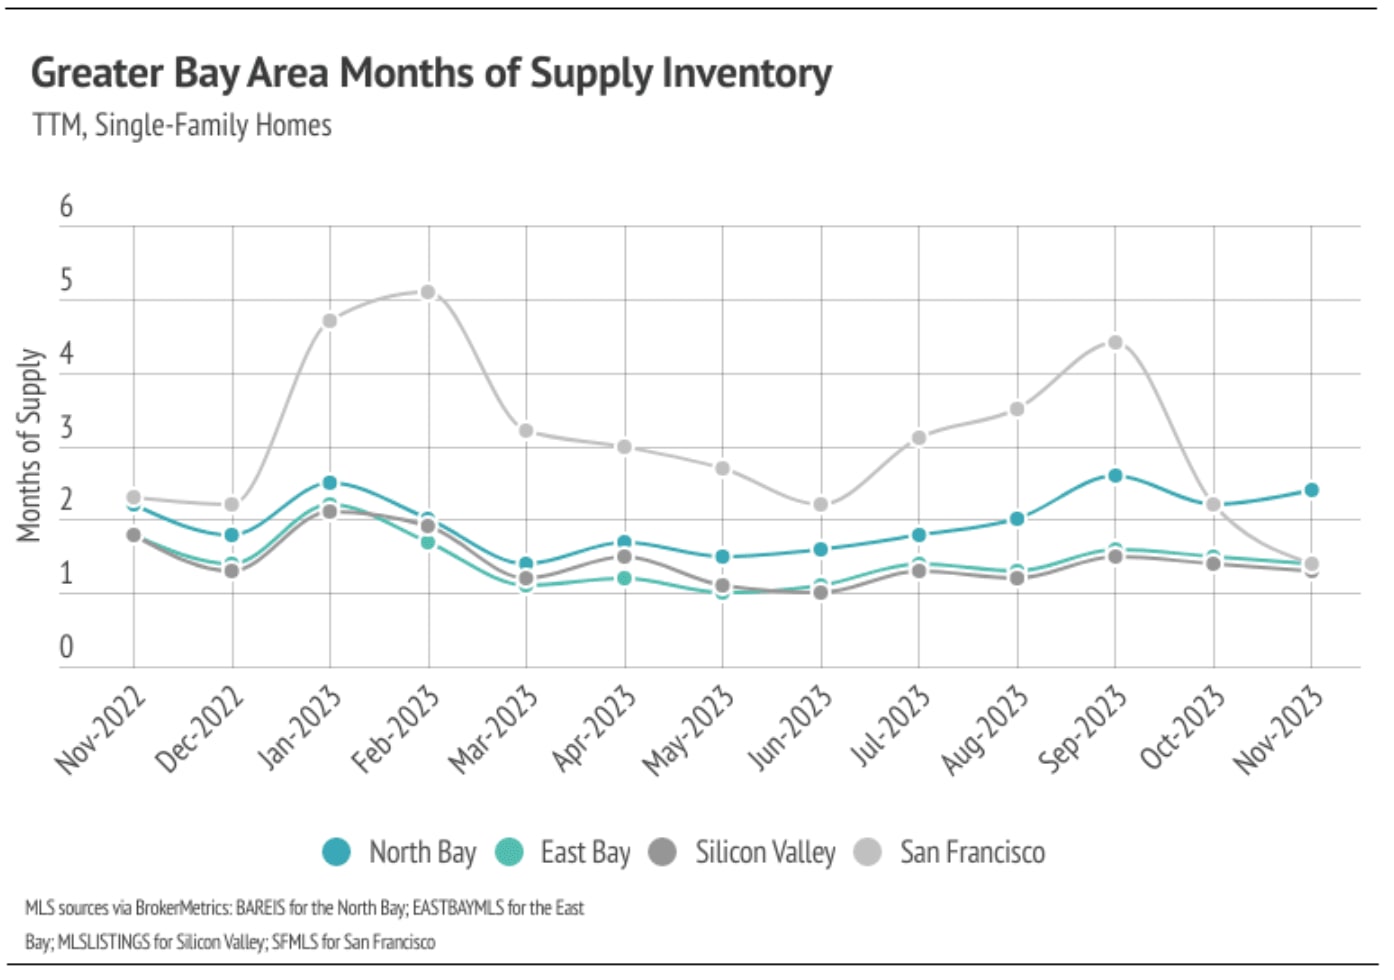
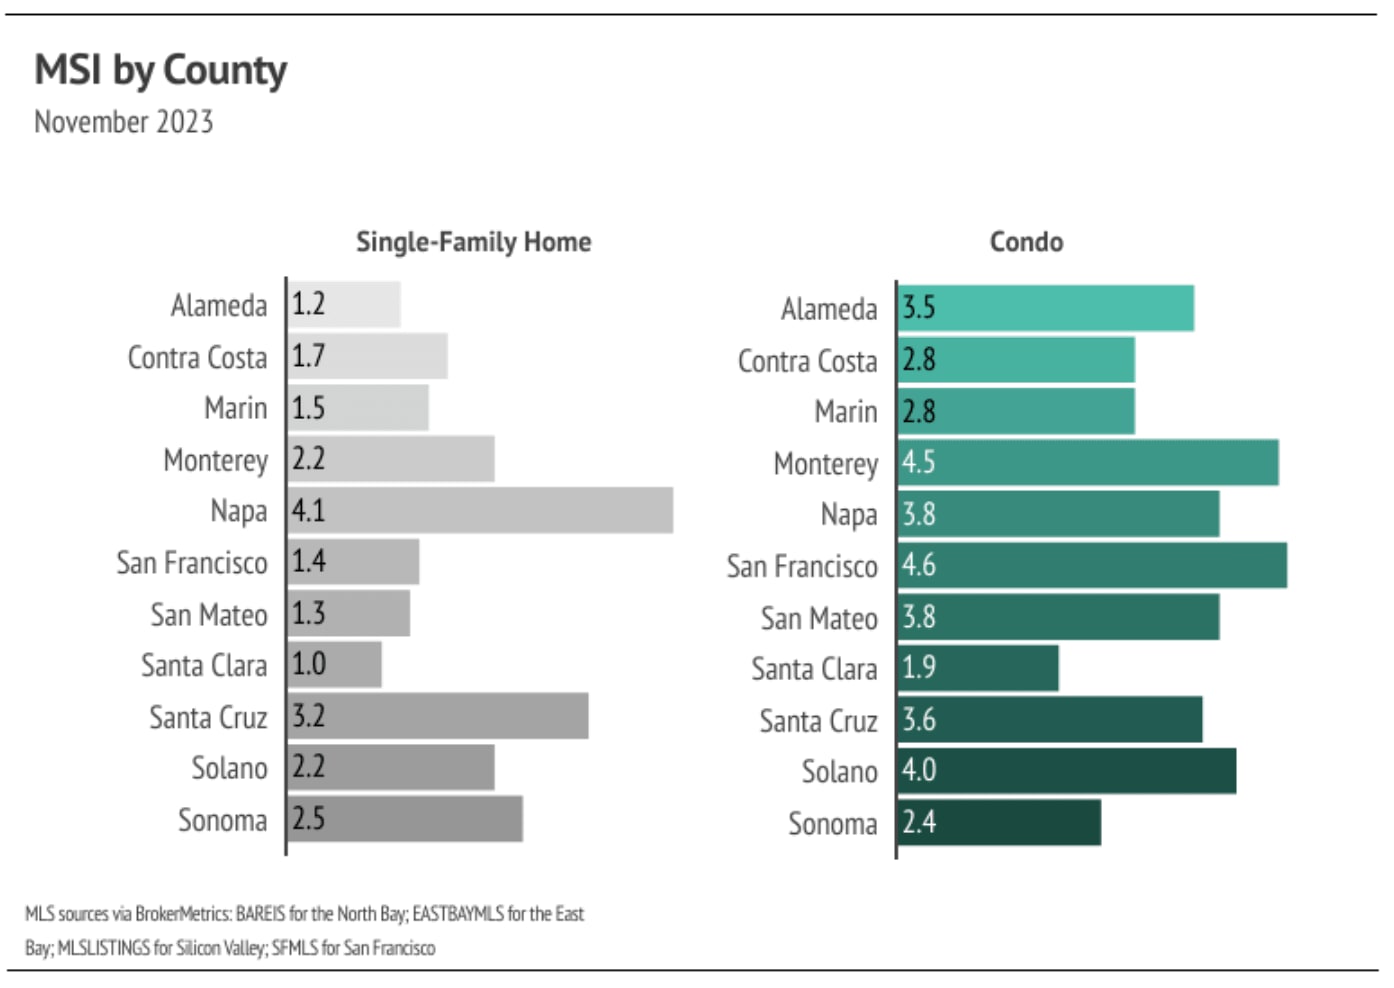
Months of Supply Inventory indicates the single-family home market still strongly favors sellers, while the condo market is trending toward balance

Months of Supply Inventory (MSI) quantifies the supply/demand relationship by measuring how many months it would take for all current homes listed on the market to sell at the current rate of sales. The long-term average MSI is around three months in California, which indicates a balanced market. An MSI lower than three indicates that there are more buyers than sellers on the market (meaning it’s a sellers’ market), while a higher MSI indicates there are more sellers than buyers (meaning it’s a buyers’ market). The Bay Area markets tend to favor sellers, which is reflected in their low MSIs. San Francisco MSI is notable for its variability this year, oscillating from buyers’ to sellers’ markets twice over the course of 10 months. Currently, single-family home MSI is below three months of supply (sellers’ market) in every Bay Area county except for Santa Cruz, which is more balanced, and Napa, which now favors buyers. The condo markets are a little more mixed, but mostly balanced.
 

Local Lowdown Data

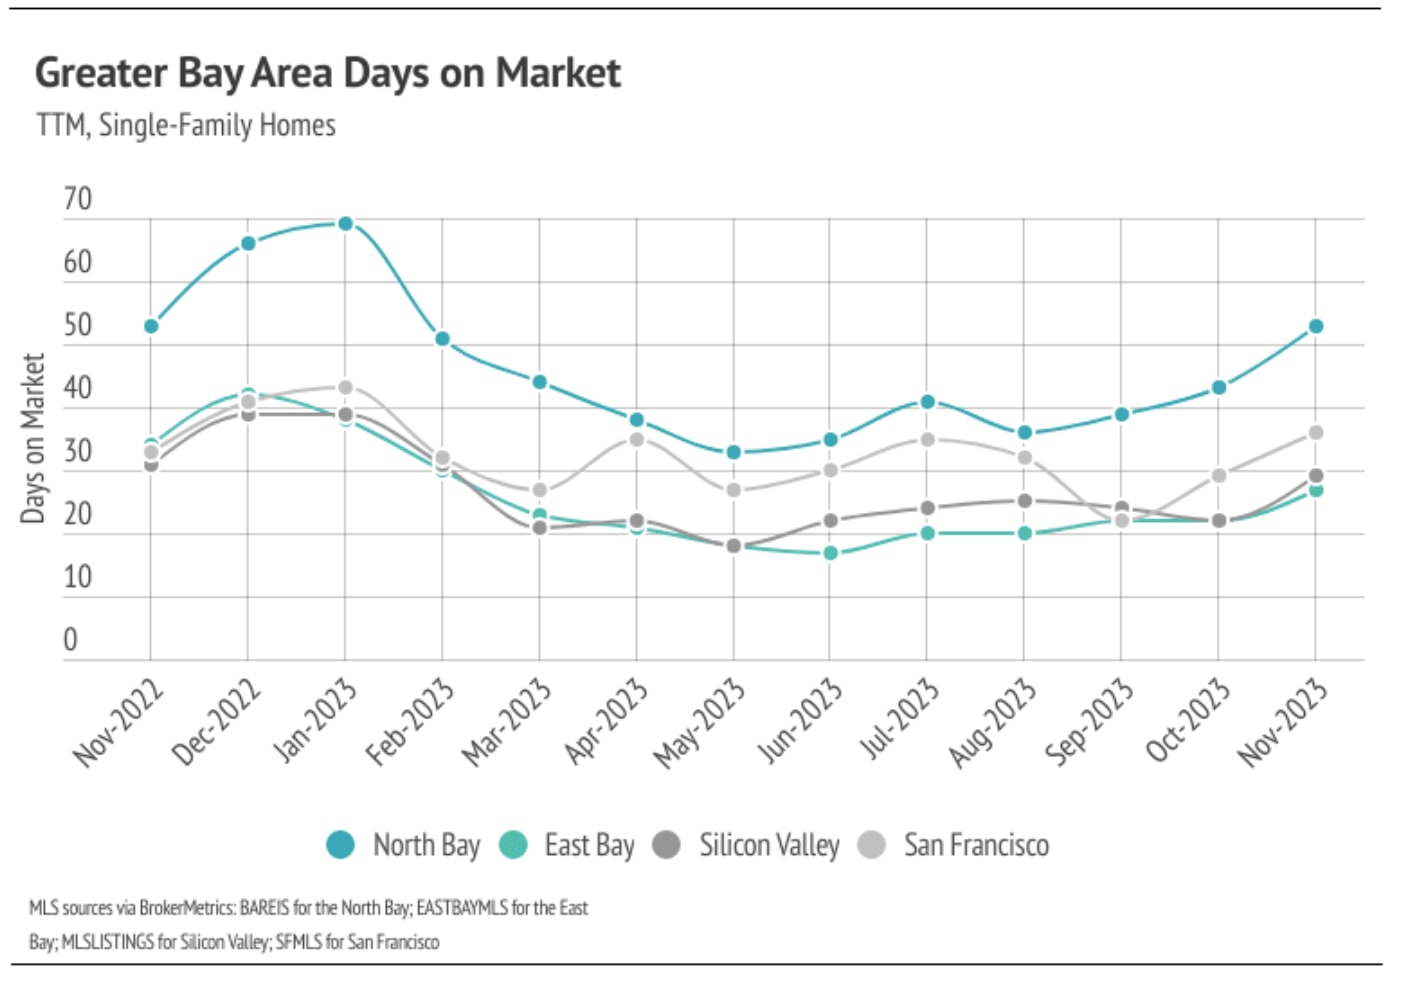
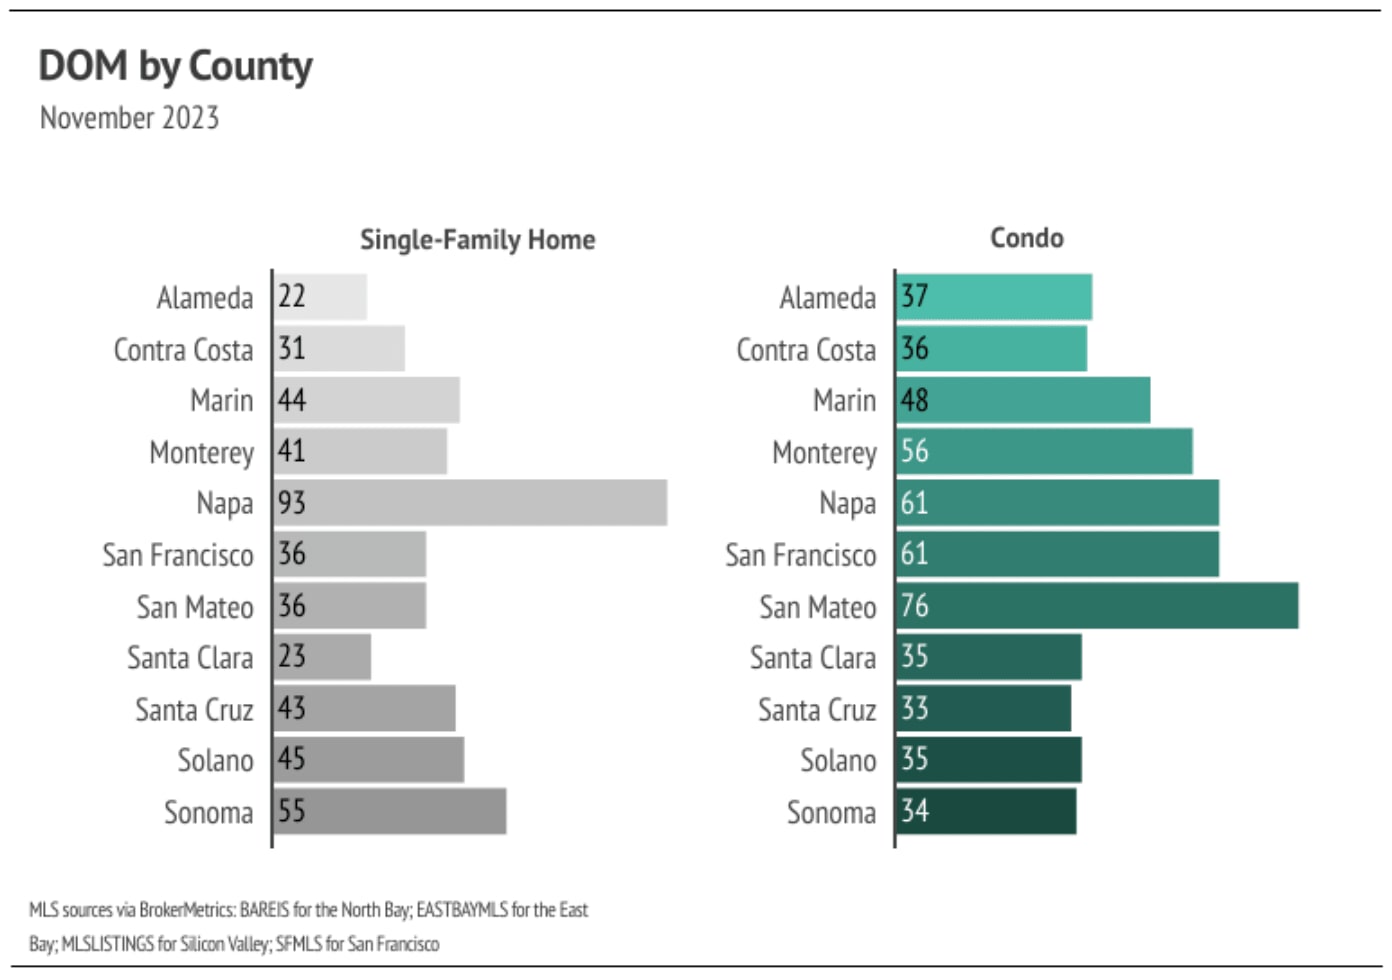
Line chart comparing two years of monthly single-family home median prices across four Bay Area regions.Chart of November 2023 Bay Area county home prices and year-over-year changes; Monterey rose most, Napa fell most.Chart of monthly Bay Area condo median prices by region from November 2021 to November 2023.Chart of year-over-year condo prices by Bay Area county in November 2023, including price changes and listed prices.Chart of North Bay single-family home inventory, new listings, and sales from November 2021 to November 2023.Chart of East Bay single-family home inventory, new listings, and sales from November 2021 through November 2023.Chart of monthly Silicon Valley single-family home inventory, new listings, and sales from November 2021 to November 2023.Chart of San Francisco single-family home inventory, new listings, and sales by month from November 2021 to November 2023.Line chart comparing monthly days on market for single-family homes in four Greater Bay Area regions, November 2022–November 2023.November 2023 Bay Area days-on-market chart comparing single-family homes and condos across ten counties.Line chart comparing monthly single-family home supply across four Greater Bay Area regions, November 2022–November 2023.November 2023 months of supply by county, comparing single-family homes and condos across the Bay Area.

We Would Love to Meet You!

You’ve got questions and we can’t wait to answer them.