The Local Lowdown: August 2026

Michelle Kim  |  September 1, 2026
The Local Lowdown: August 2026

The Local Lowdown

Quick Take:
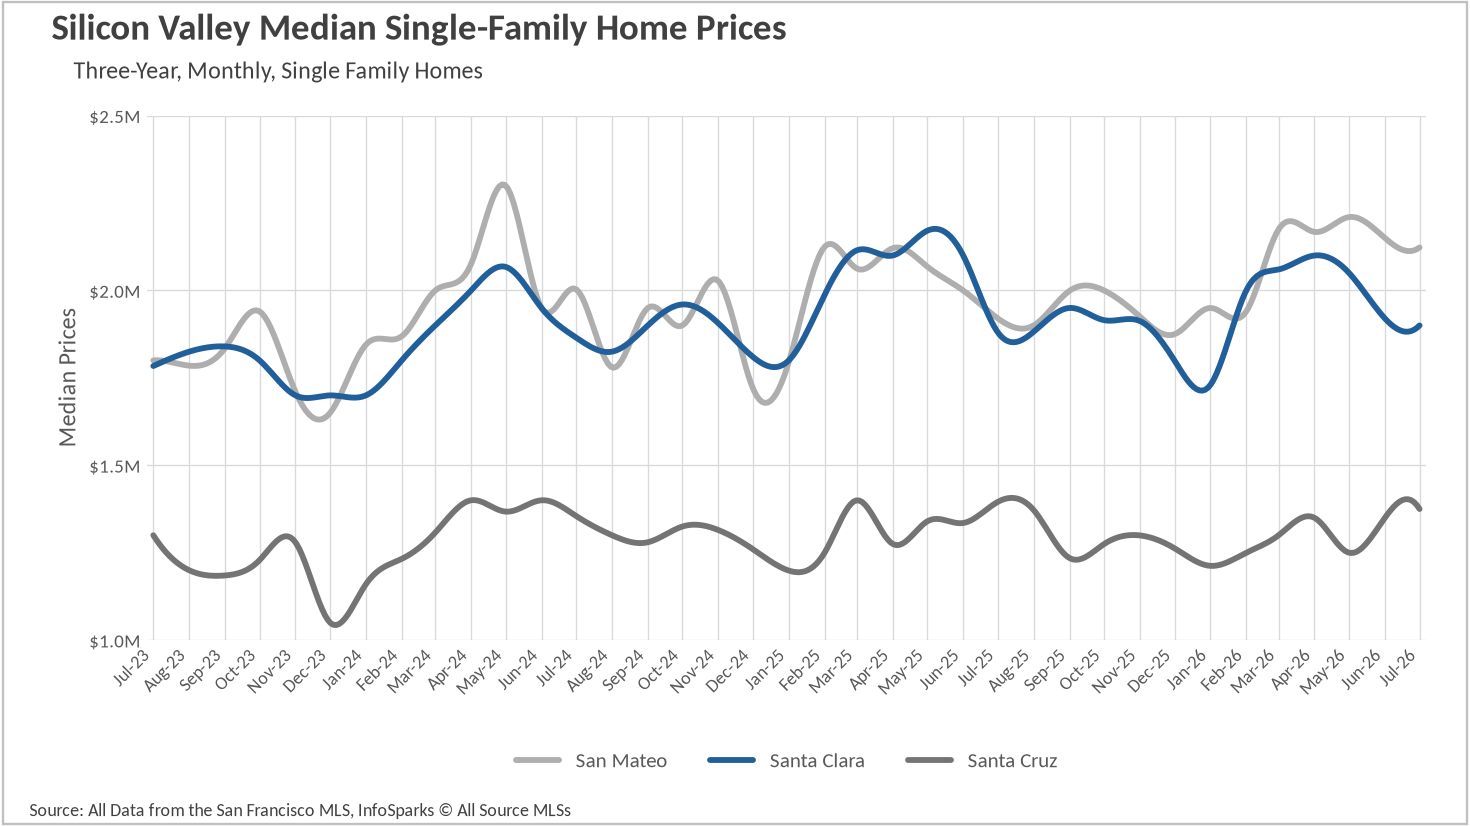
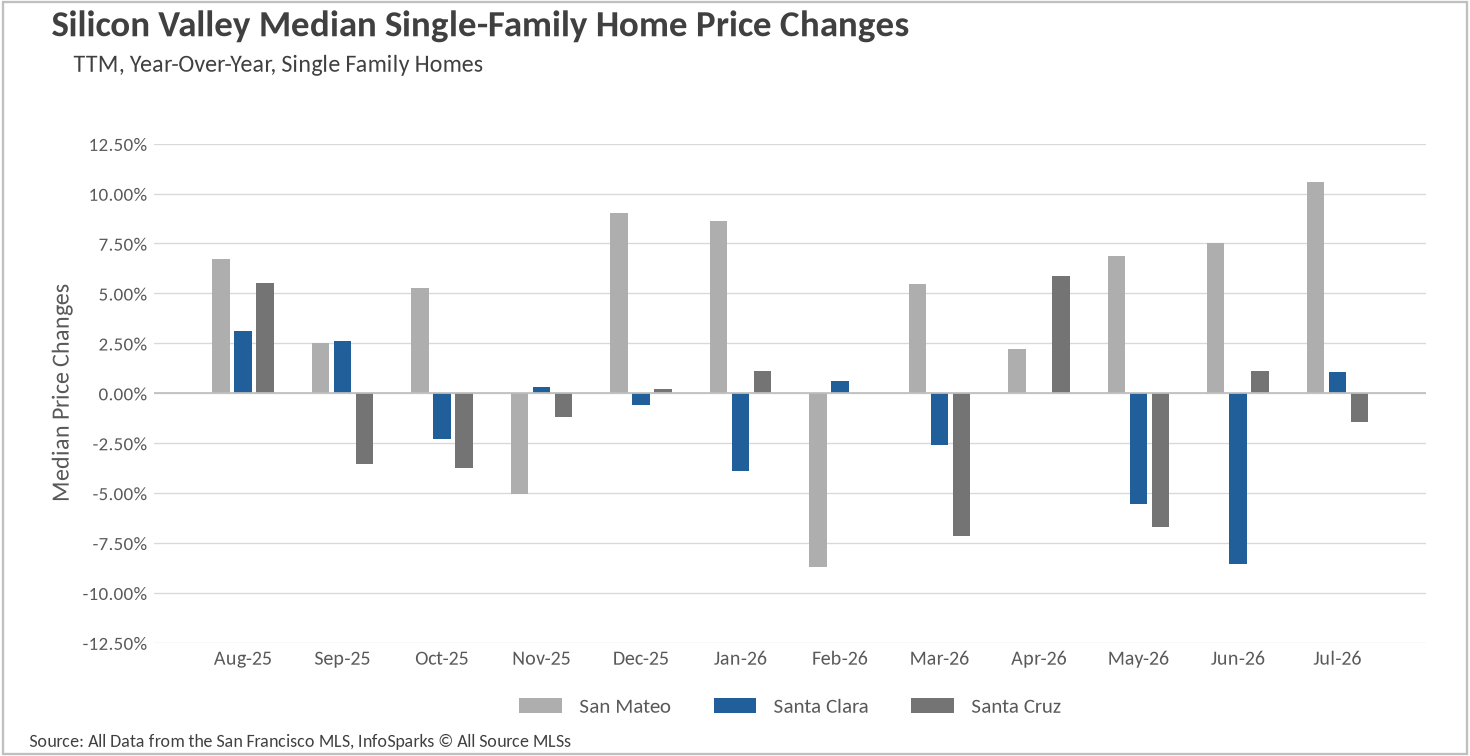
  • Single-family prices held above year-ago levels almost everywhere in July, led by San Francisco at $2,050,000 (up 24.87%) and San Mateo County at $2,123,000 (up 10.57%), while most other counties posted modest gains and eased off their spring peaks.
  • Inventory is the story of the summer. Just over 7,300 single-family homes were for sale across the Bay Area's four subregions, with declines ranging from 22% in Silicon Valley to 42% in San Francisco.
  • Homes are moving quickly, with seven of the region's ten counties clearing single-family listings in 20 days or less.
  • Nearly every single-family market in the region sits below three months of supply, and the condo segment is tightening fast behind it.

A summer step down that still leaves the region ahead of last year

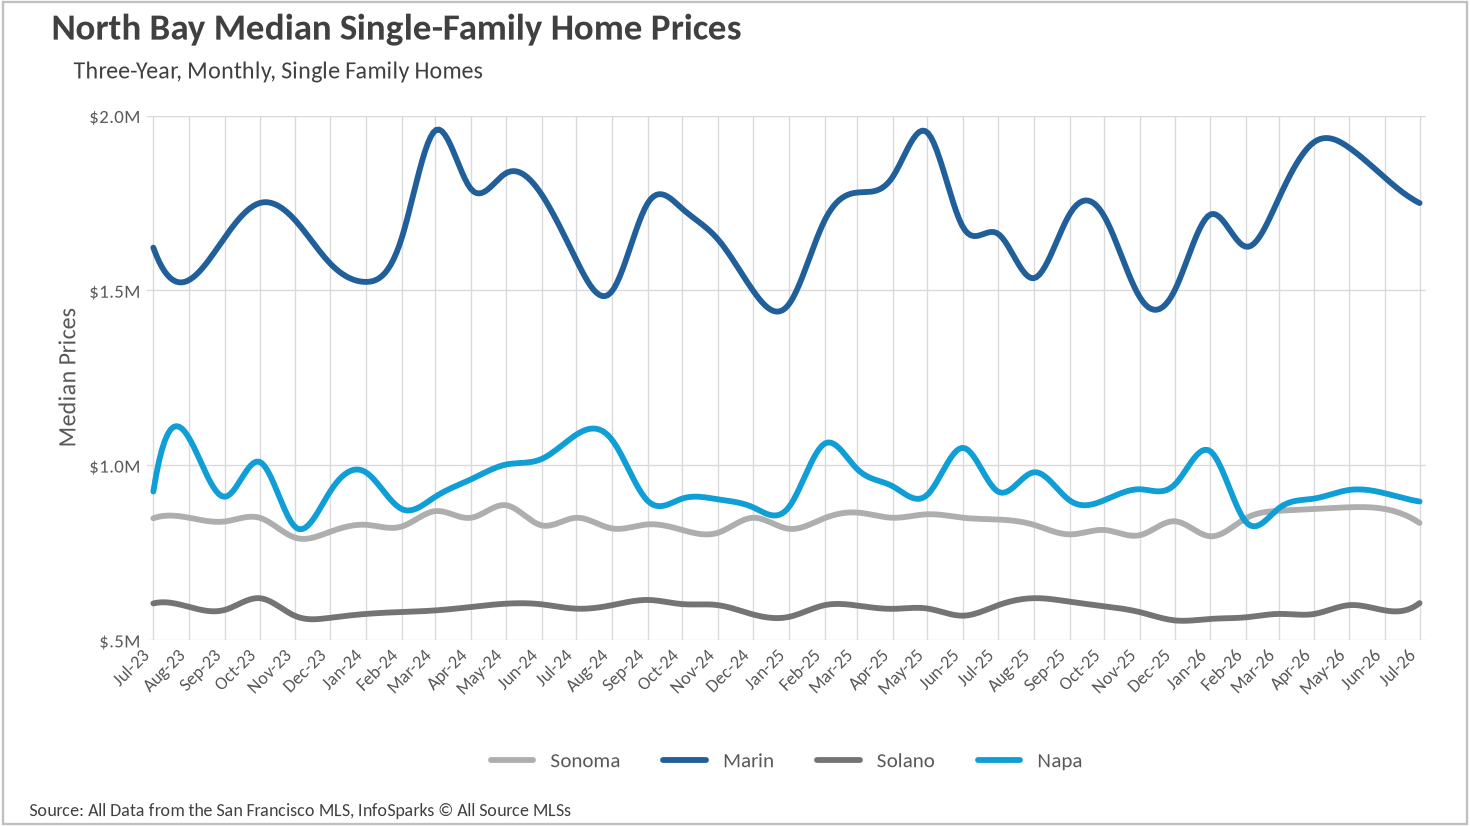
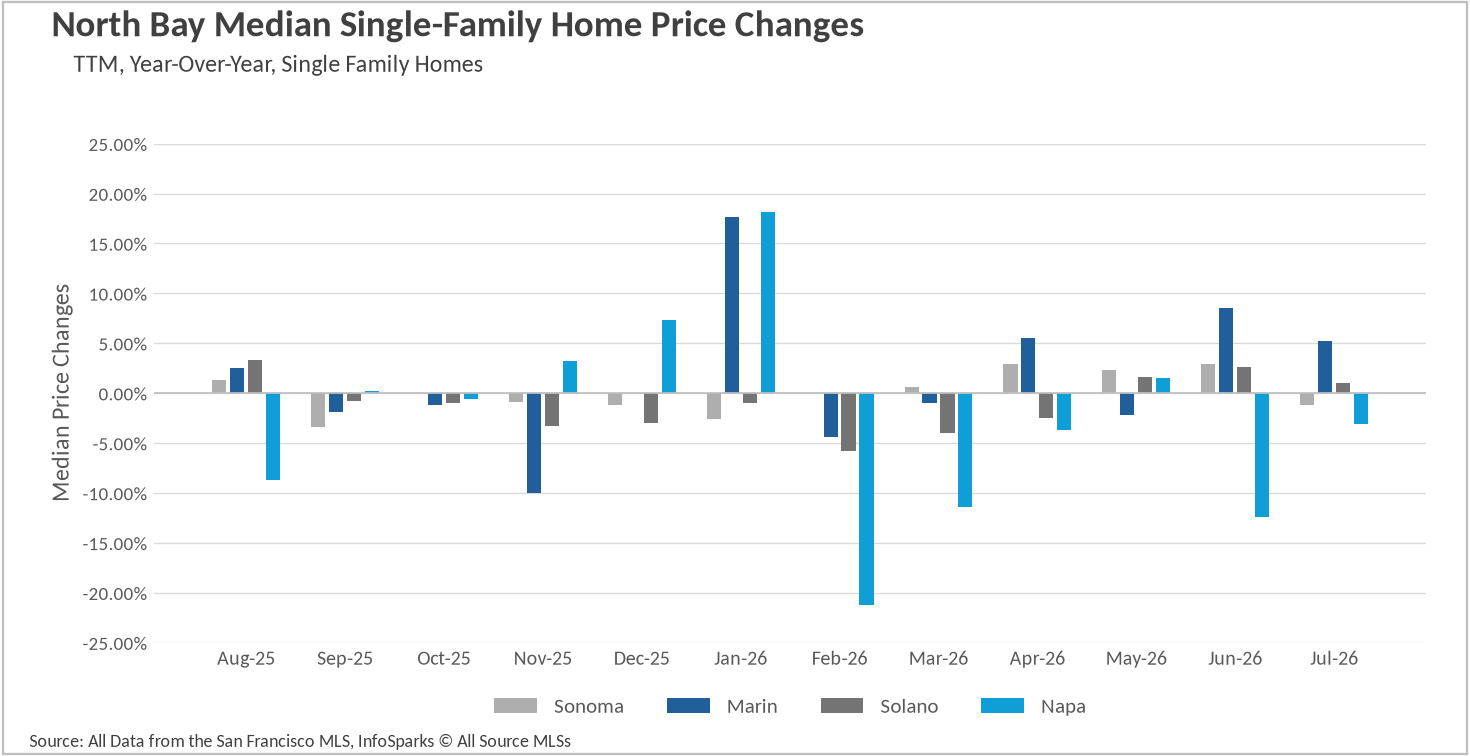
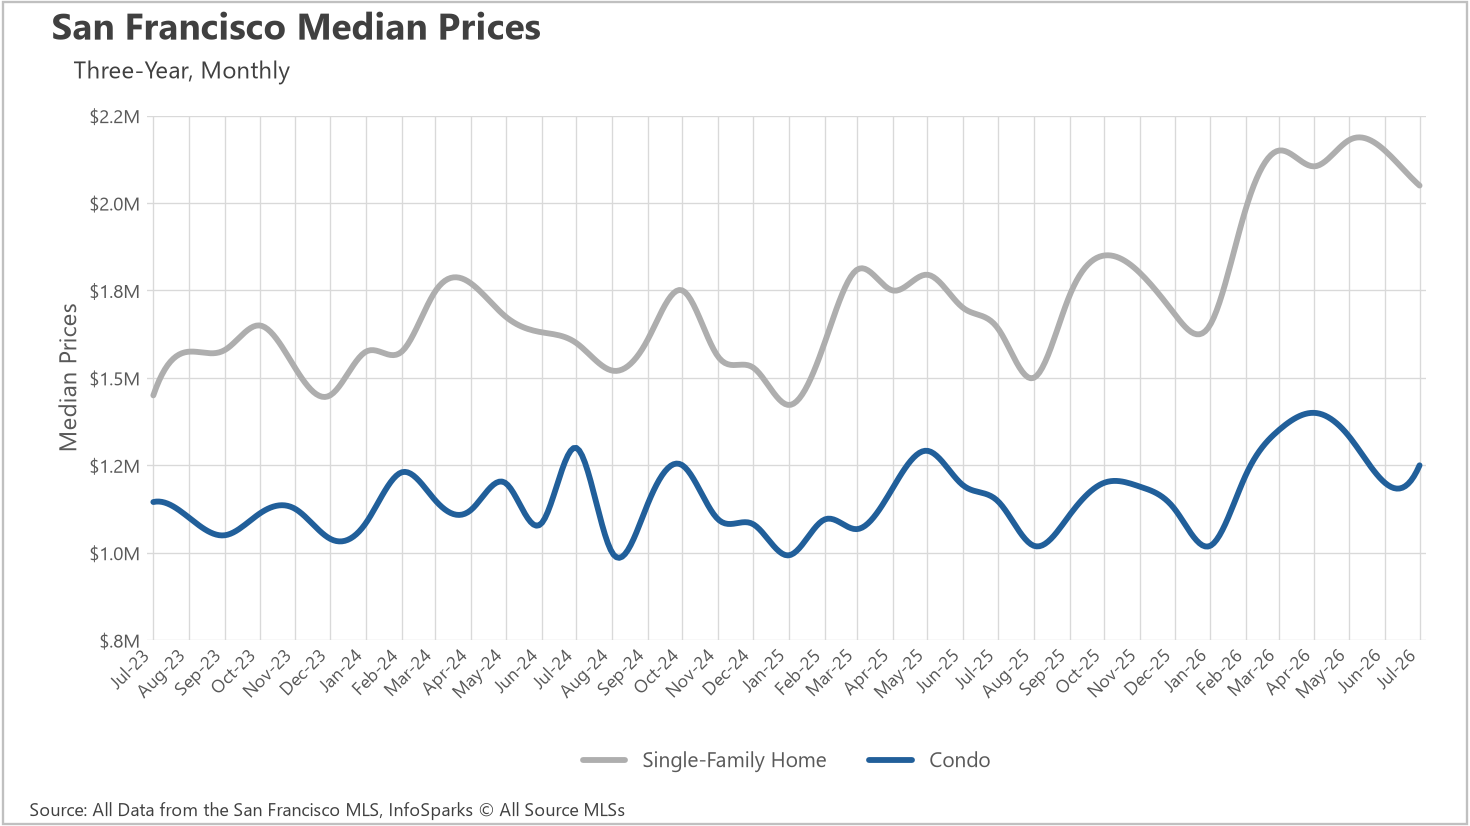
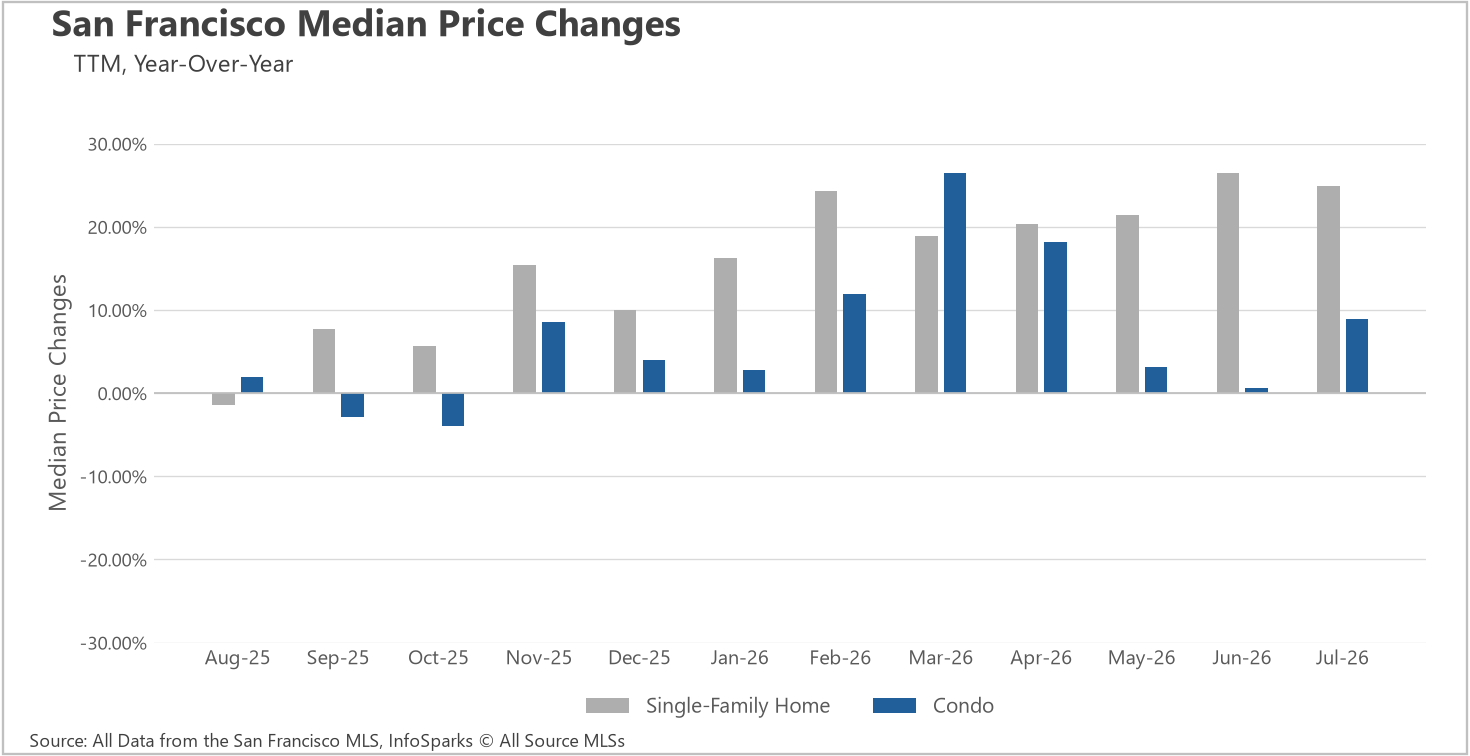
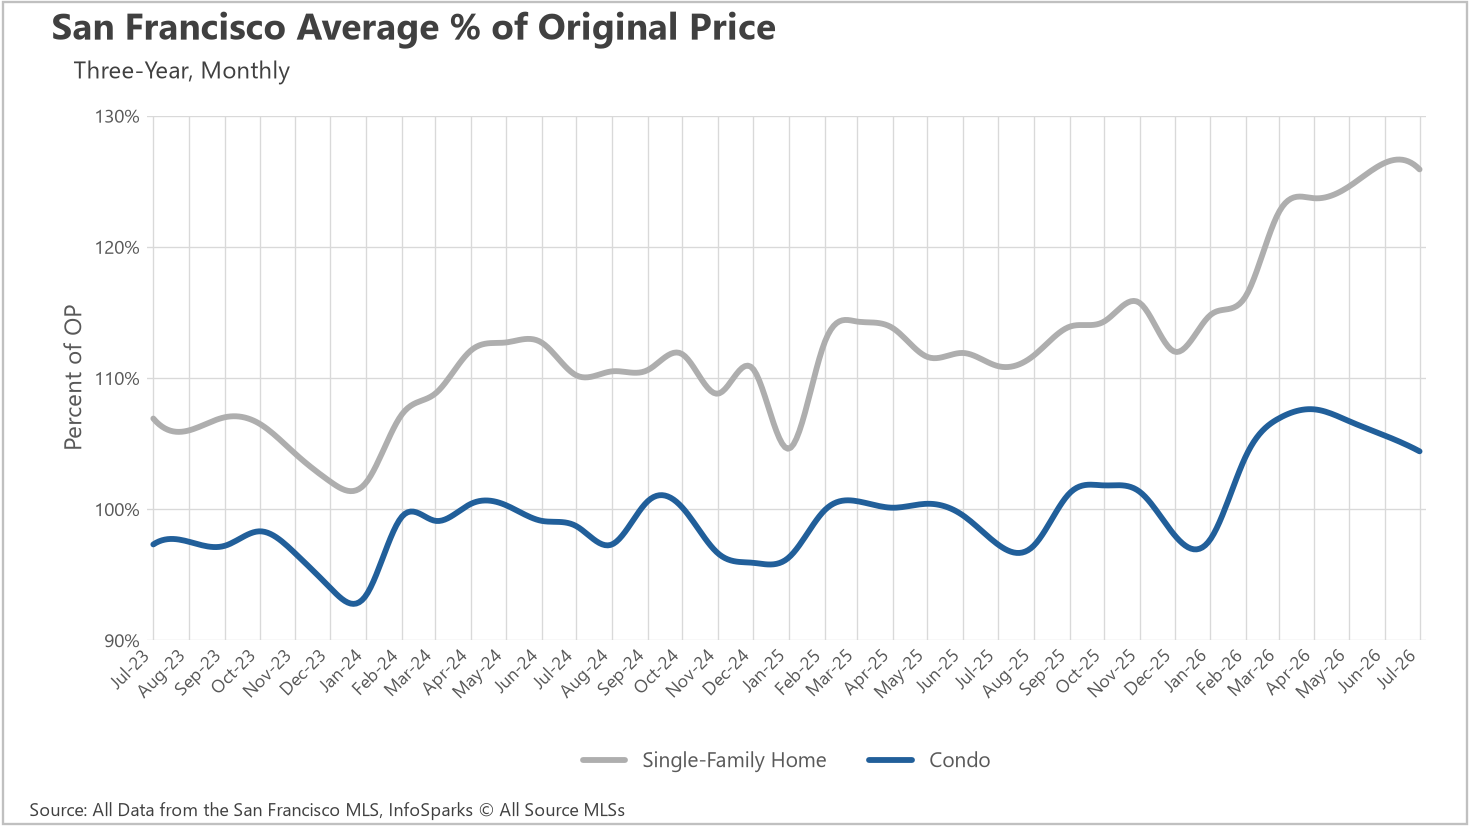
July followed the script the Bay Area has written for the past several summers: medians eased back from their May and June highs while remaining comfortably above where they stood twelve months ago. San Francisco set the pace on the year-over-year comparison, with the single-family median settling at $2,050,000, down 4.65% from June's $2,150,000 but a remarkable 24.87% above last July's $1,641,750. San Mateo County posted the region's highest median at $2,123,000, up 10.57% from a year ago, while Marin County added 5.26% to
reach $1,750,000.

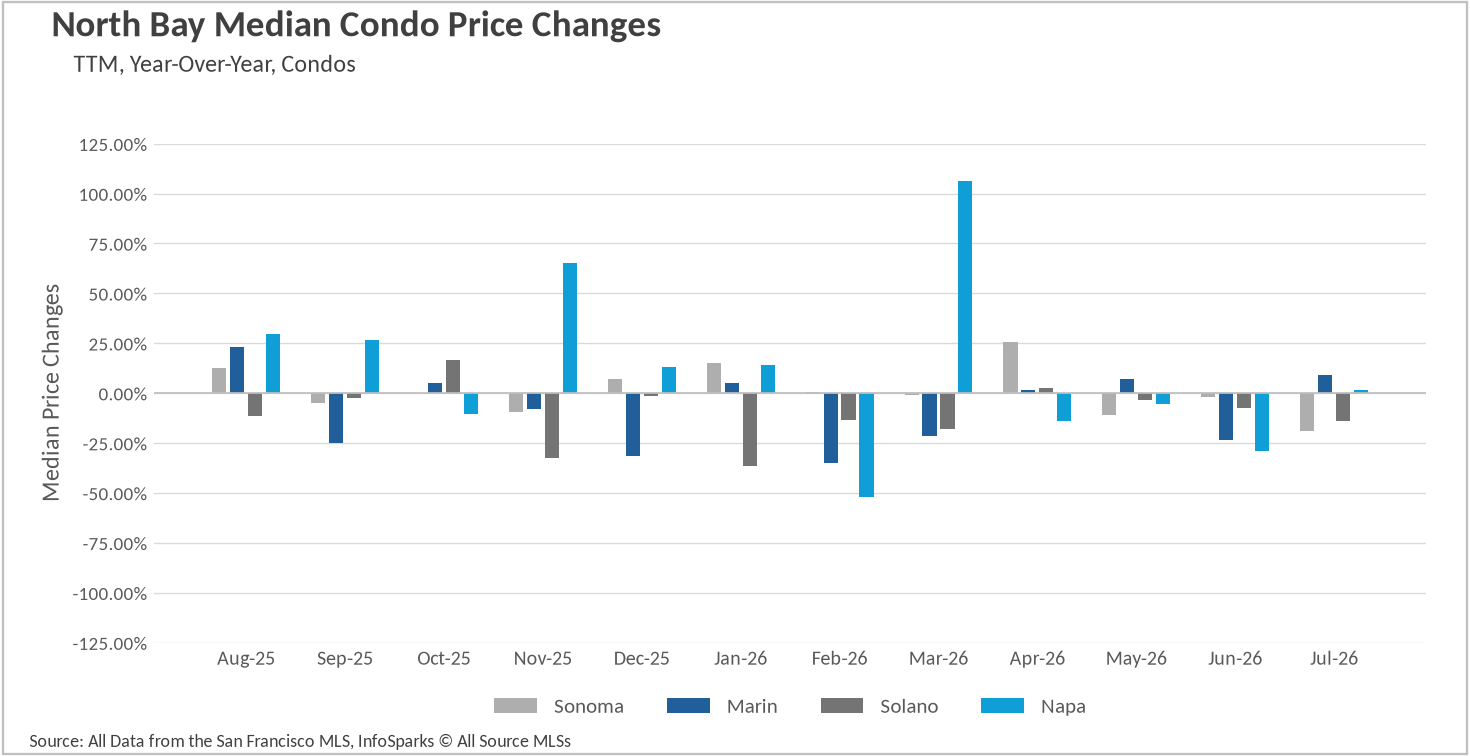
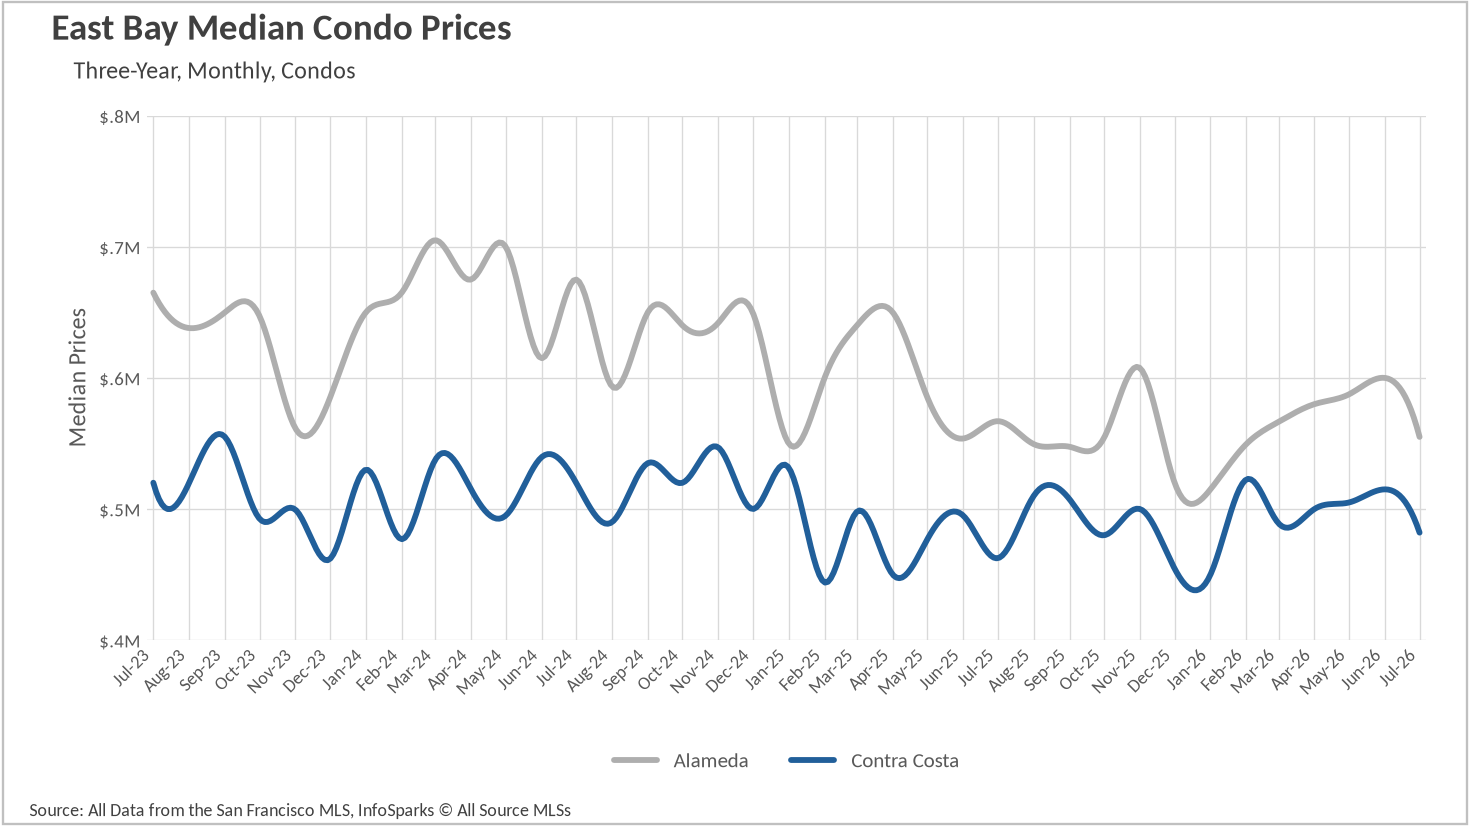
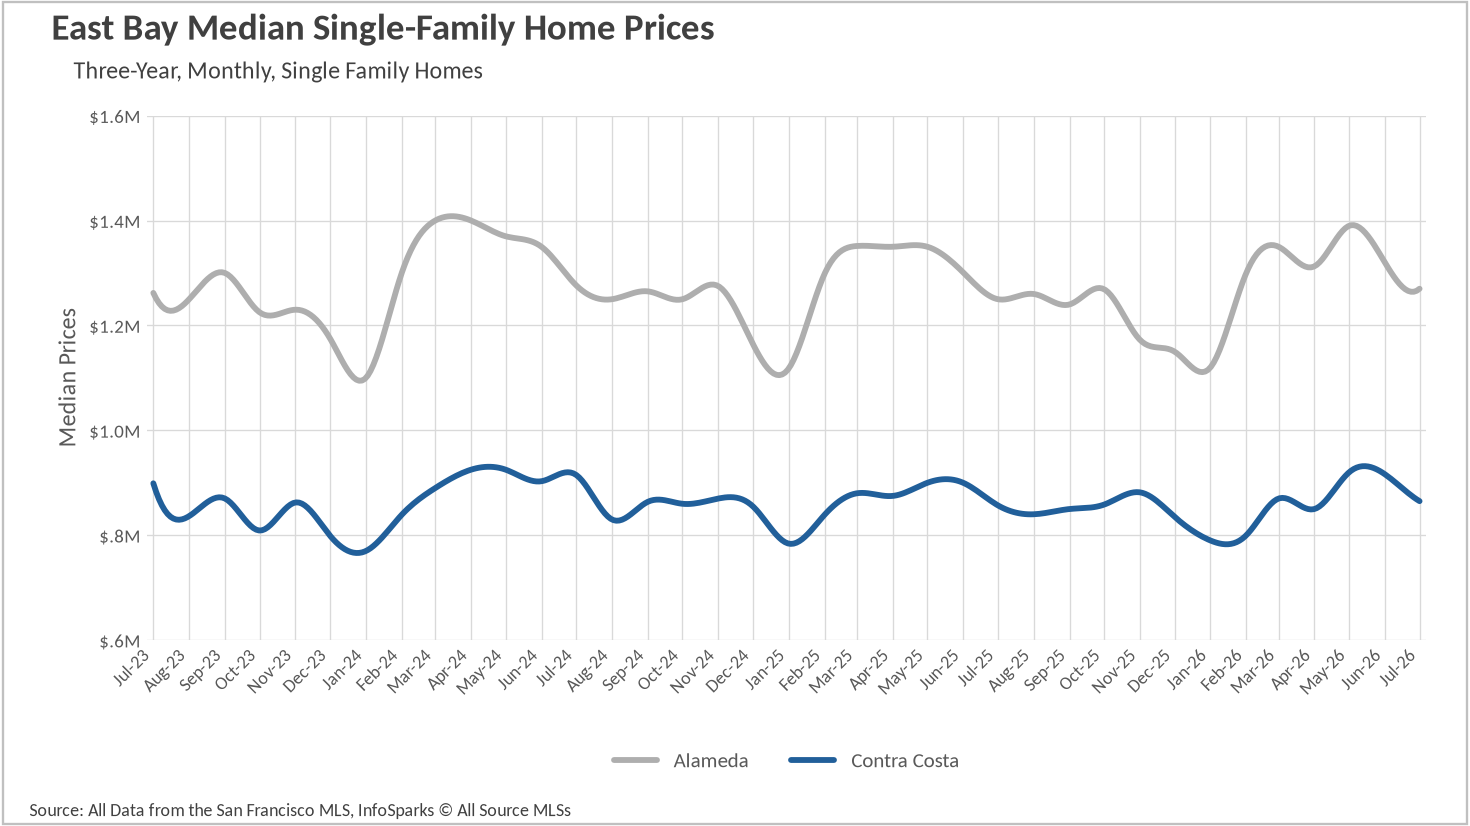
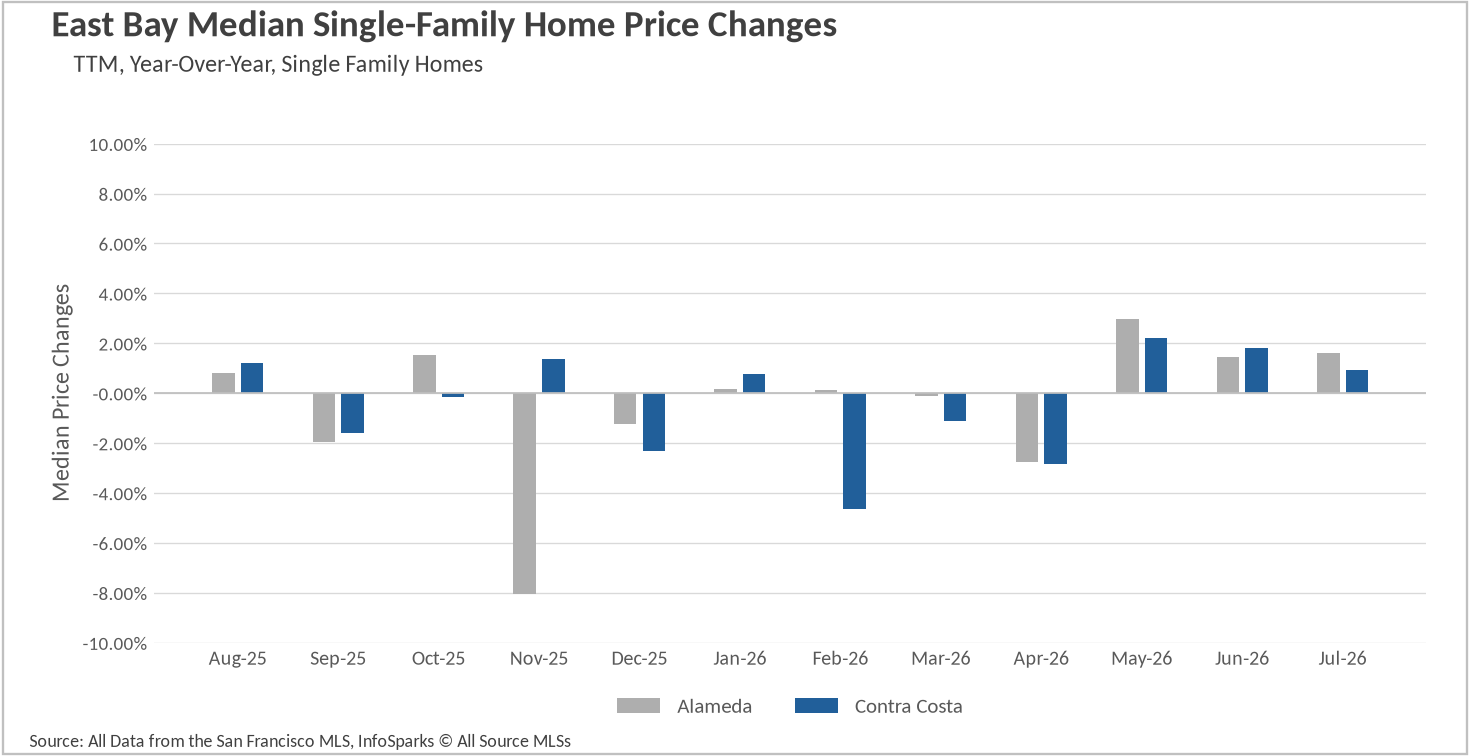
Elsewhere the gains were narrower. Santa Clara County was essentially flat at $1,900,000, up just 1.06% year over year and down for a third straight month from May's $2,050,000. Alameda County came in at $1,270,000 and Contra Costa at $865,000, up 1.60% and 0.93% respectively after peaking in May. Solano County was the month's monthly standout, climbing 3.59% from June to $606,000. Only Santa Cruz, Sonoma, and Napa Counties finished below last July, each by less than 3.1%.

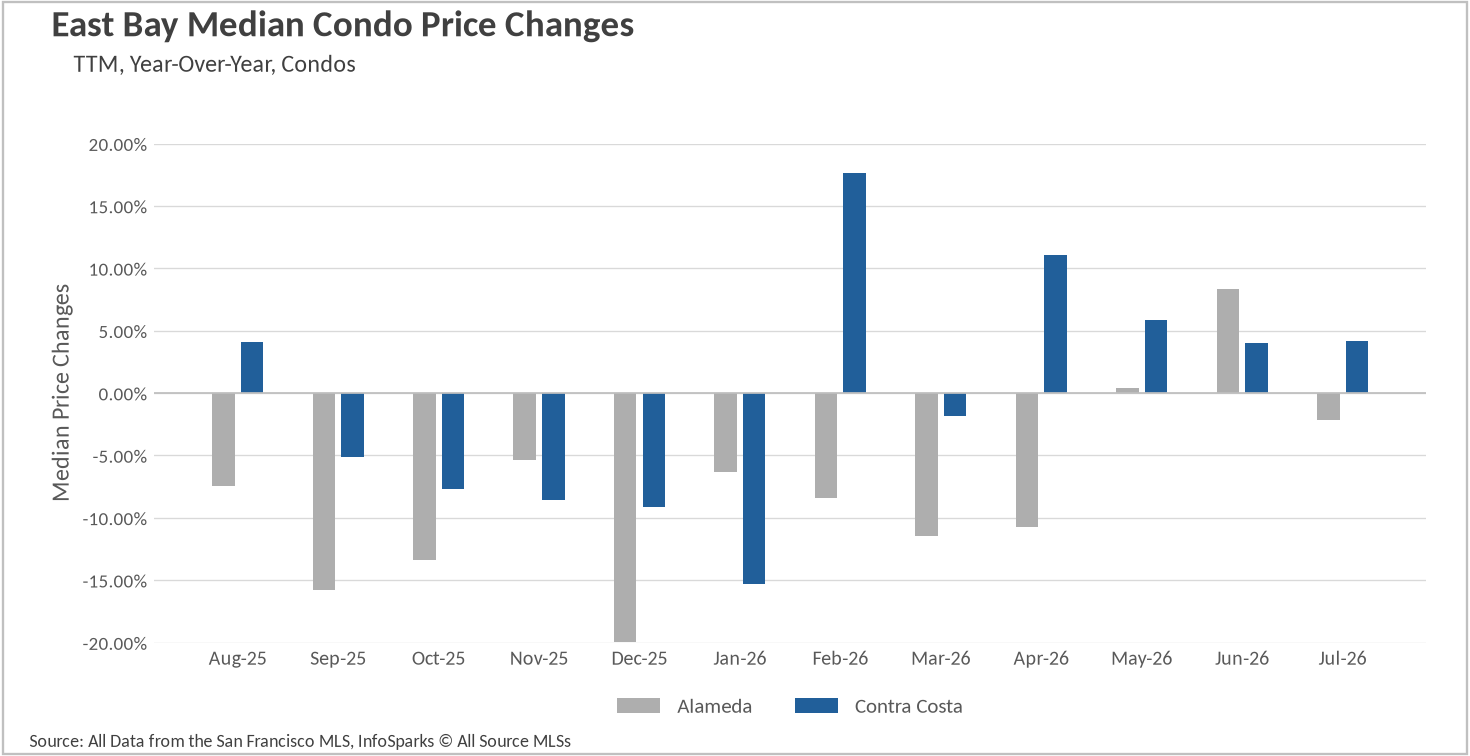
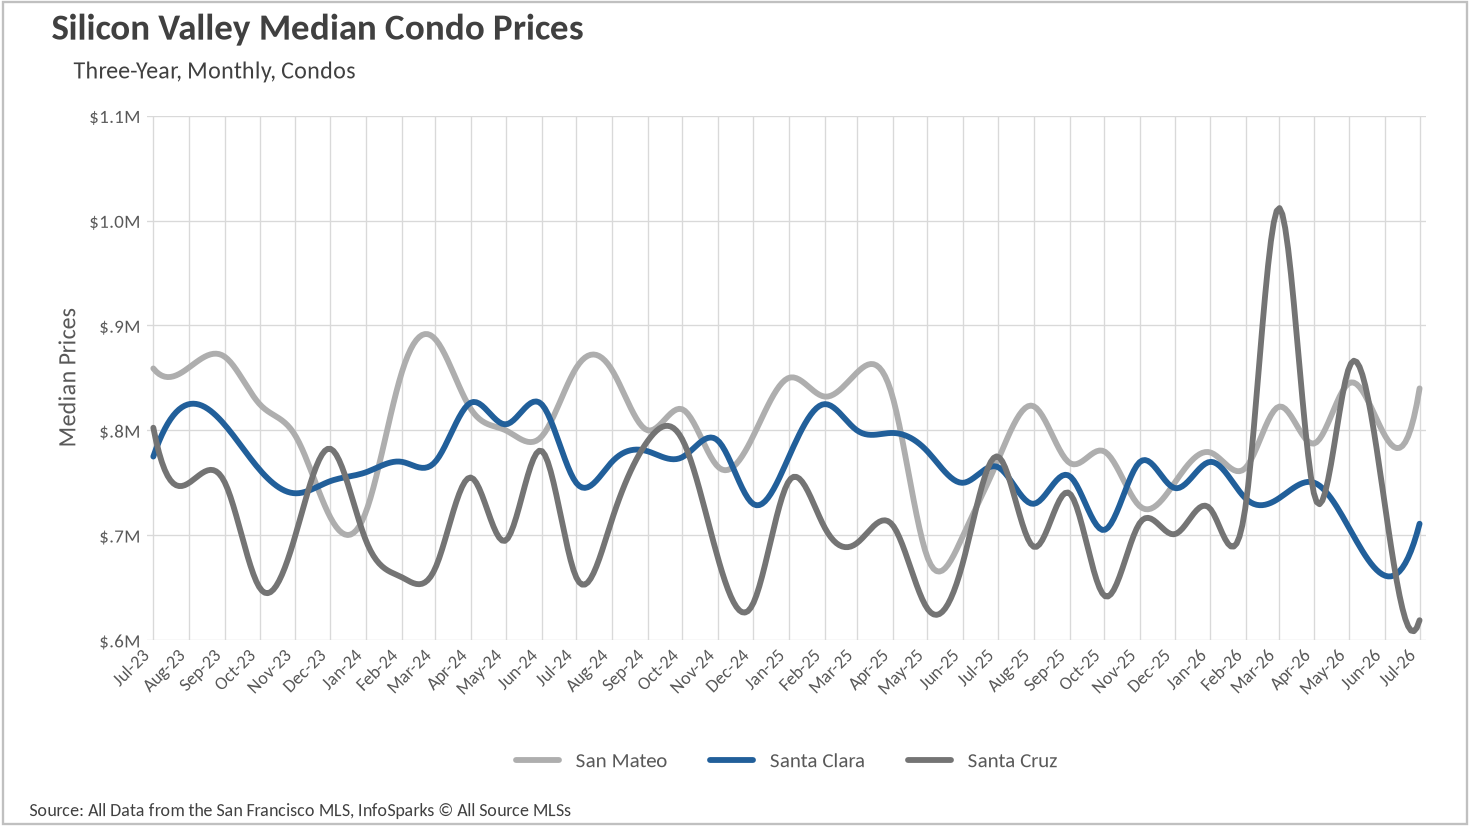
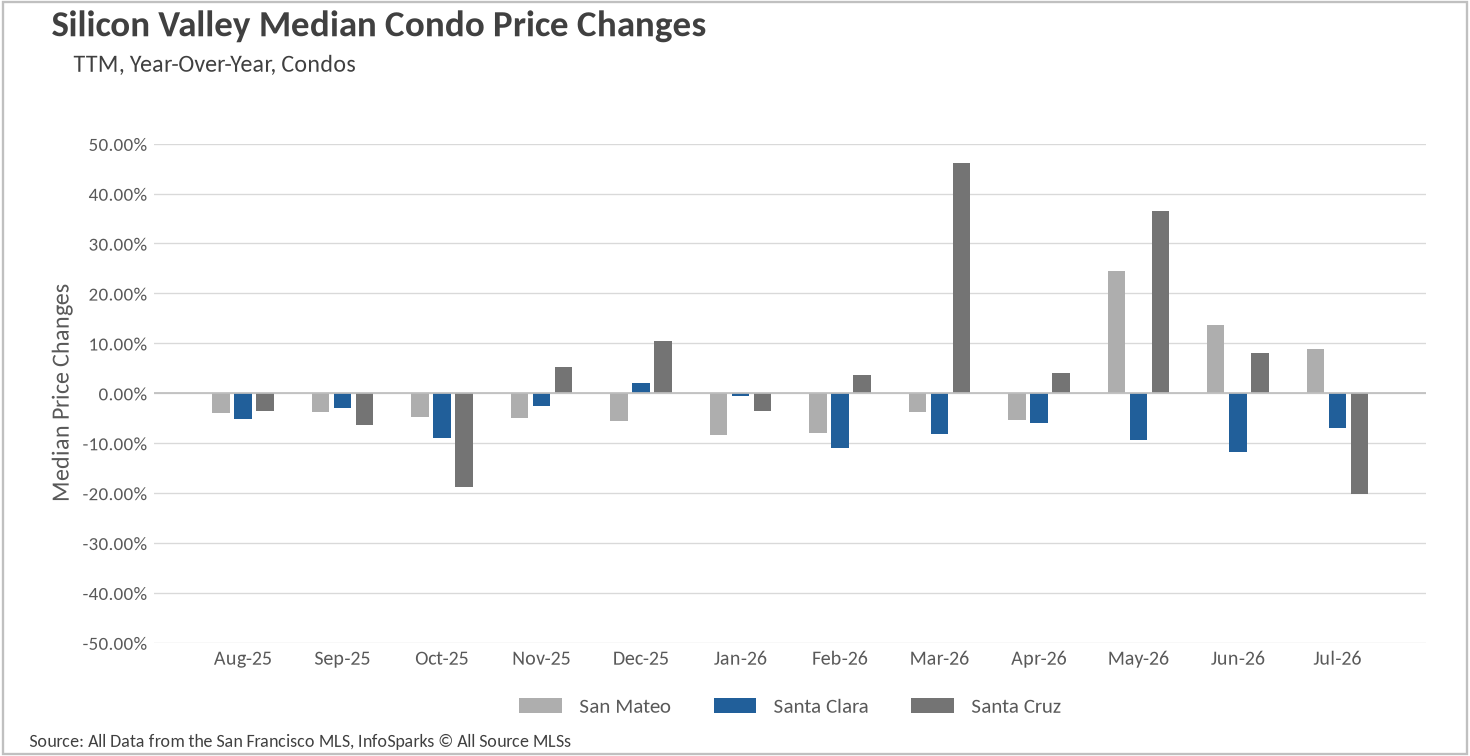
The condo picture was genuinely split. San Francisco condos rose 4.17% from June to $1,250,000, an 8.93% annual gain, and Marin County condos reached $707,500, up 8.85%. San Mateo County condos added 8.88% to $840,000. Working the other direction, Sonoma County condos fell 18.84% and Santa Cruz County condos dropped 20.13%, though transaction counts in those segments are thin enough that single-month prints deserve caution.

The supply squeeze is now region-wide

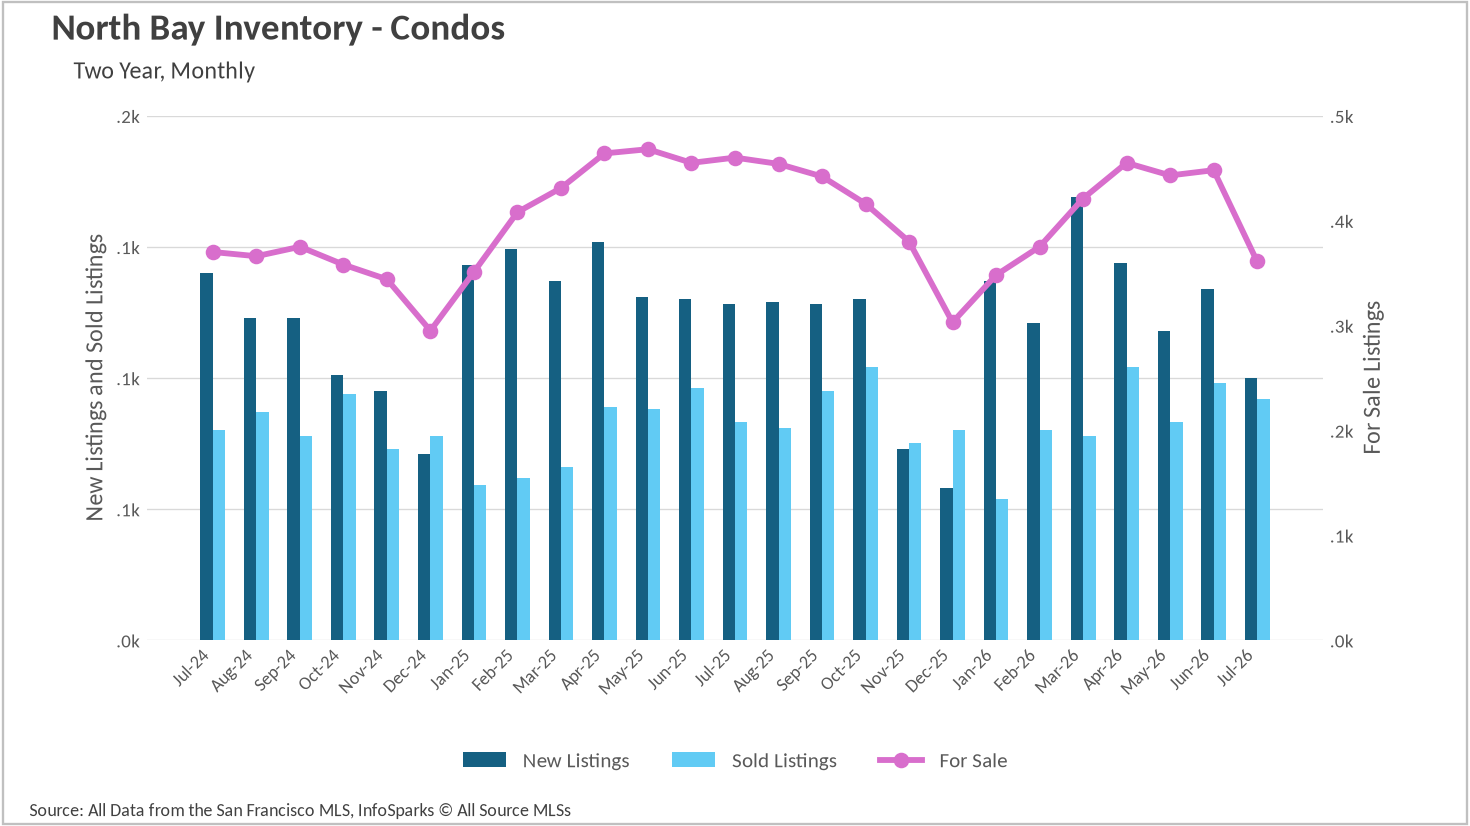
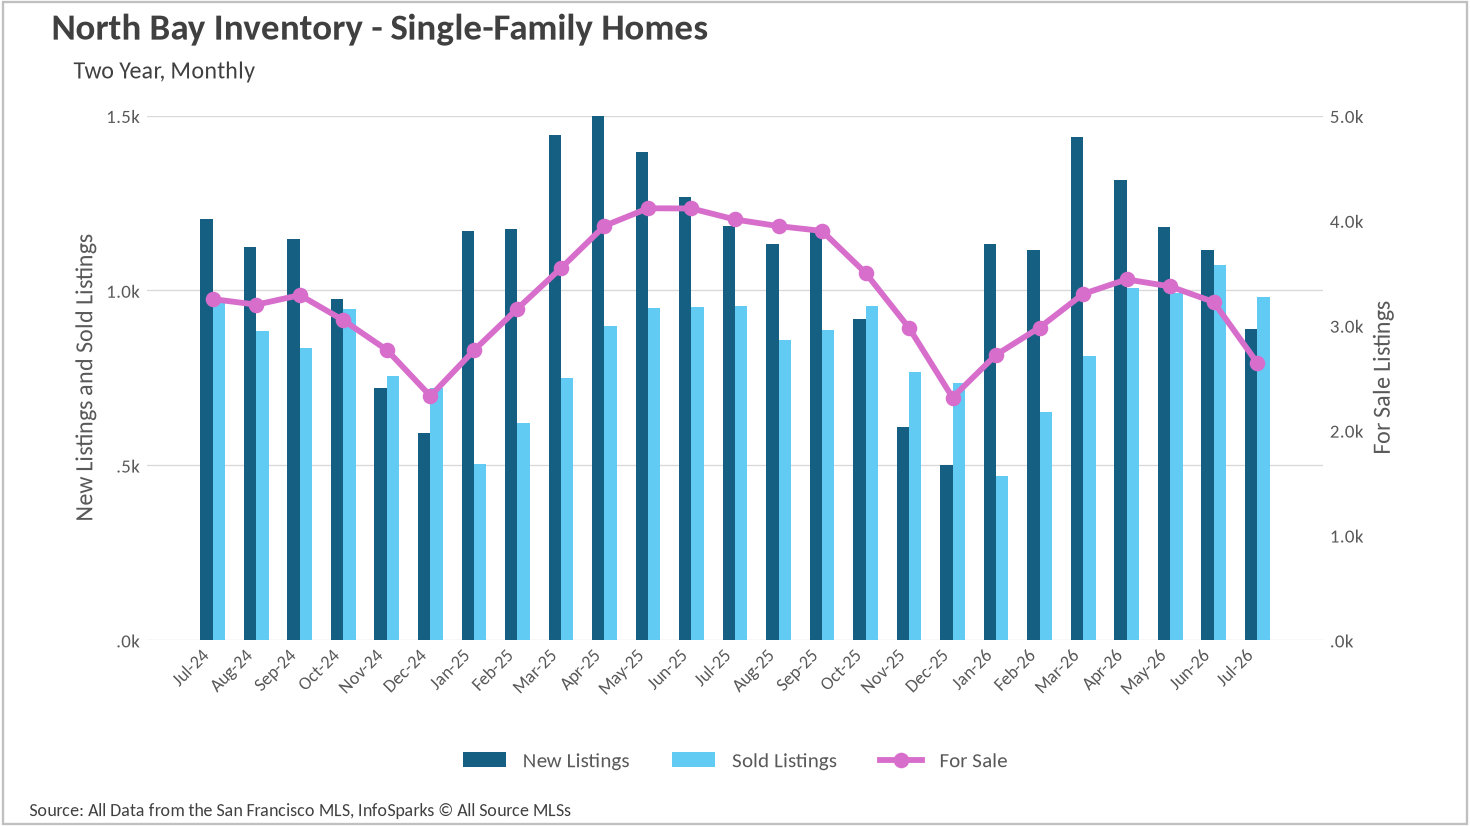
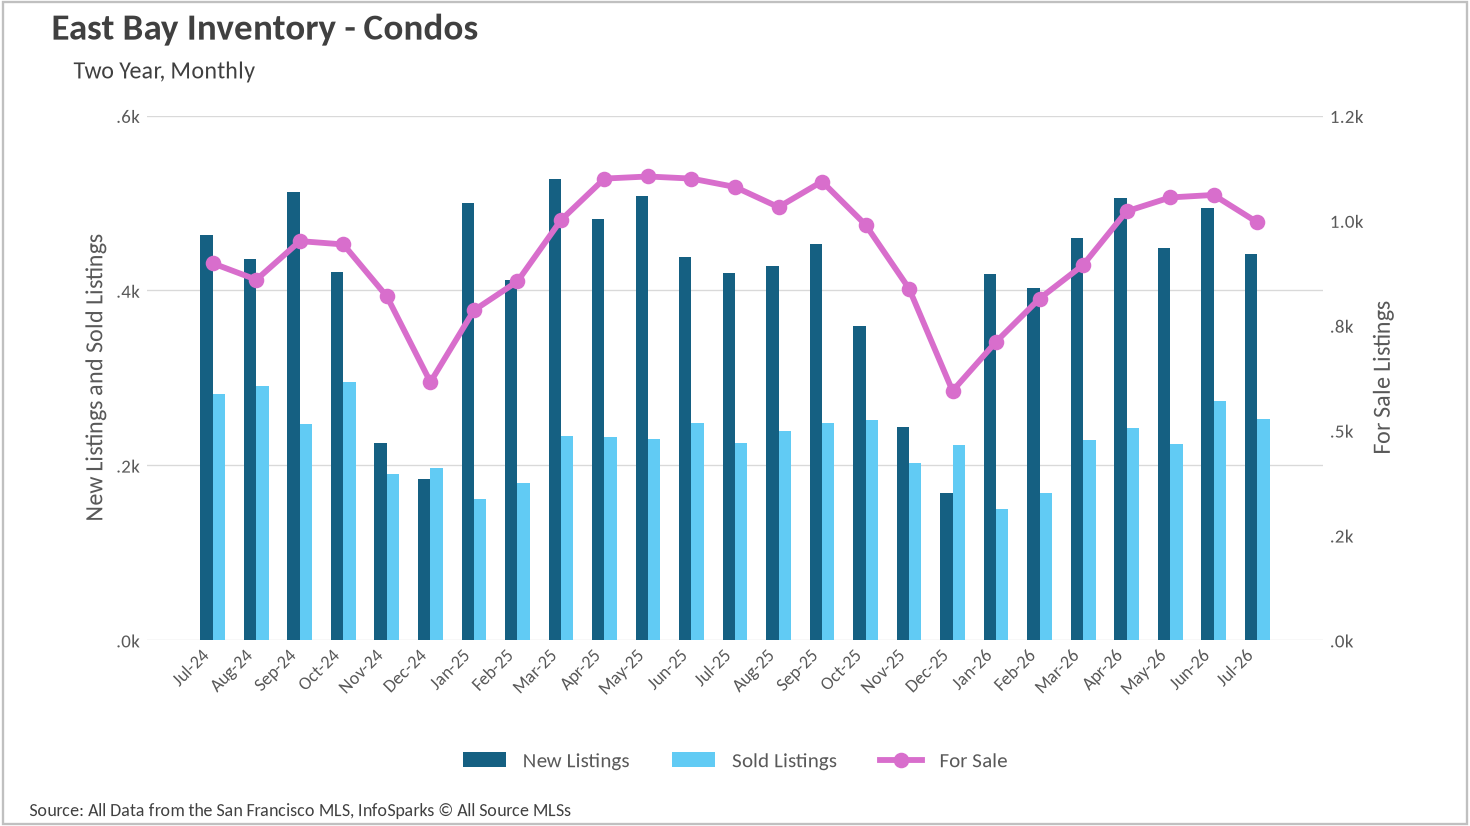
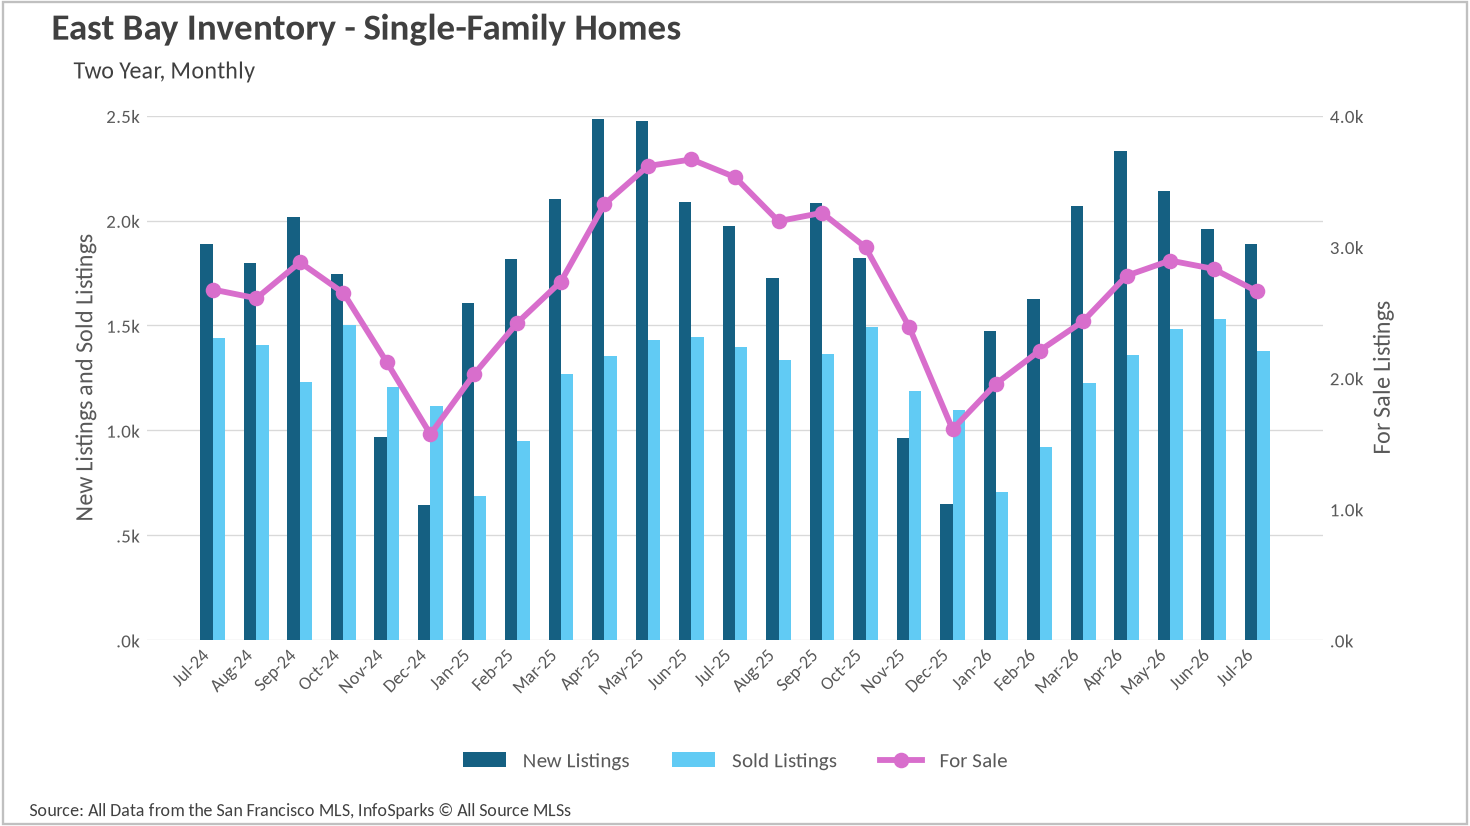
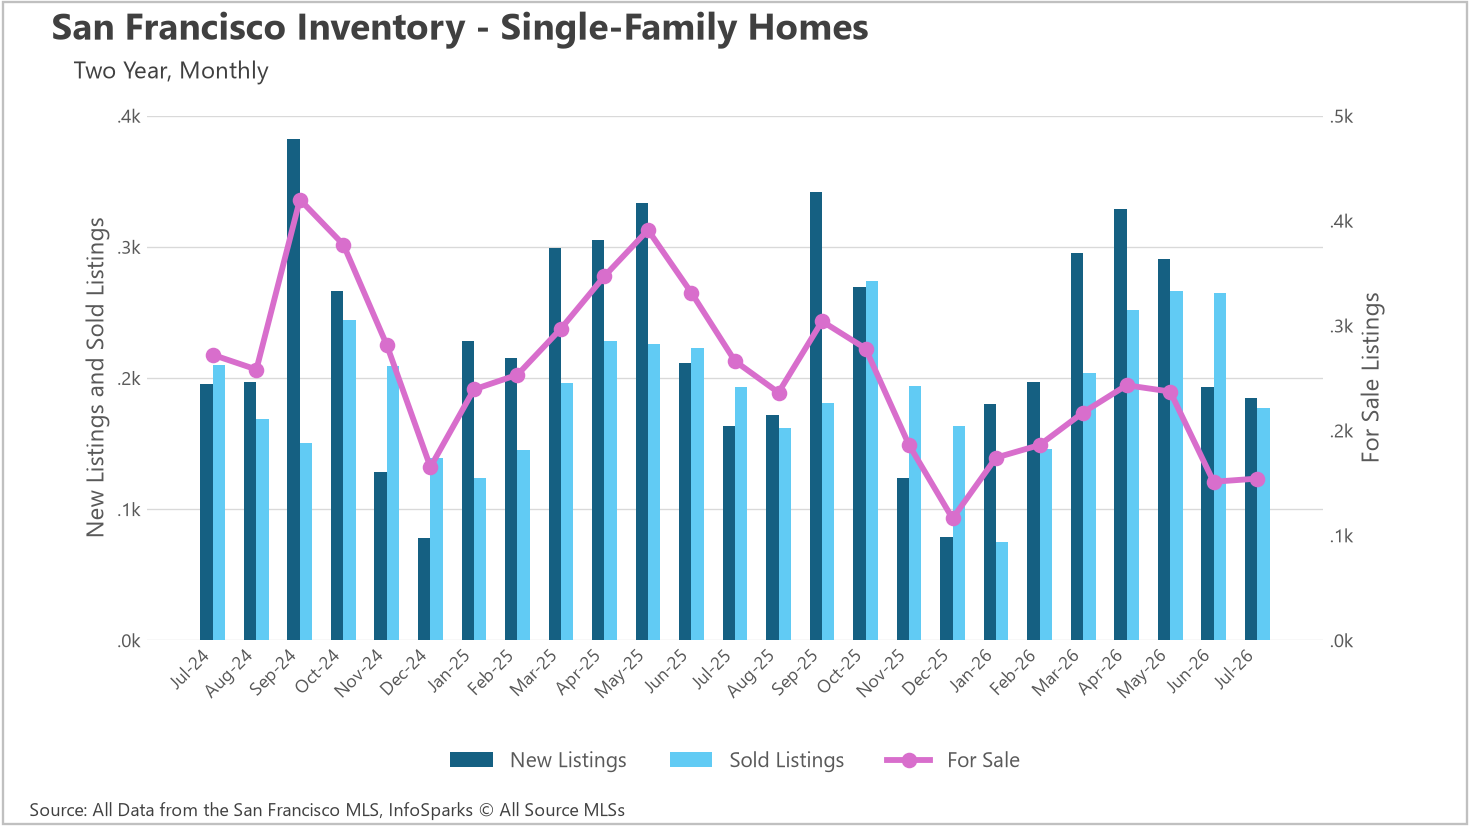
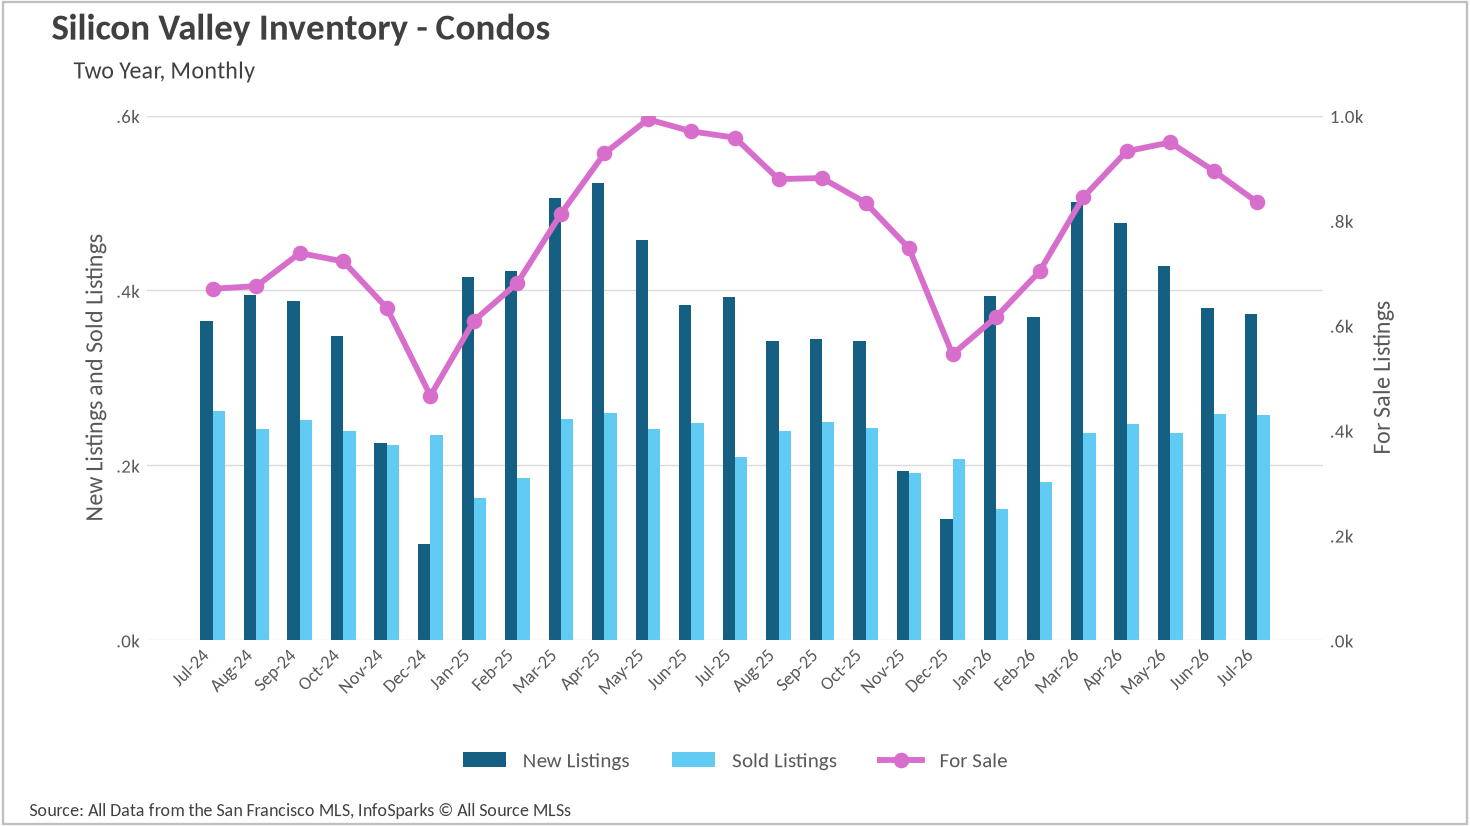
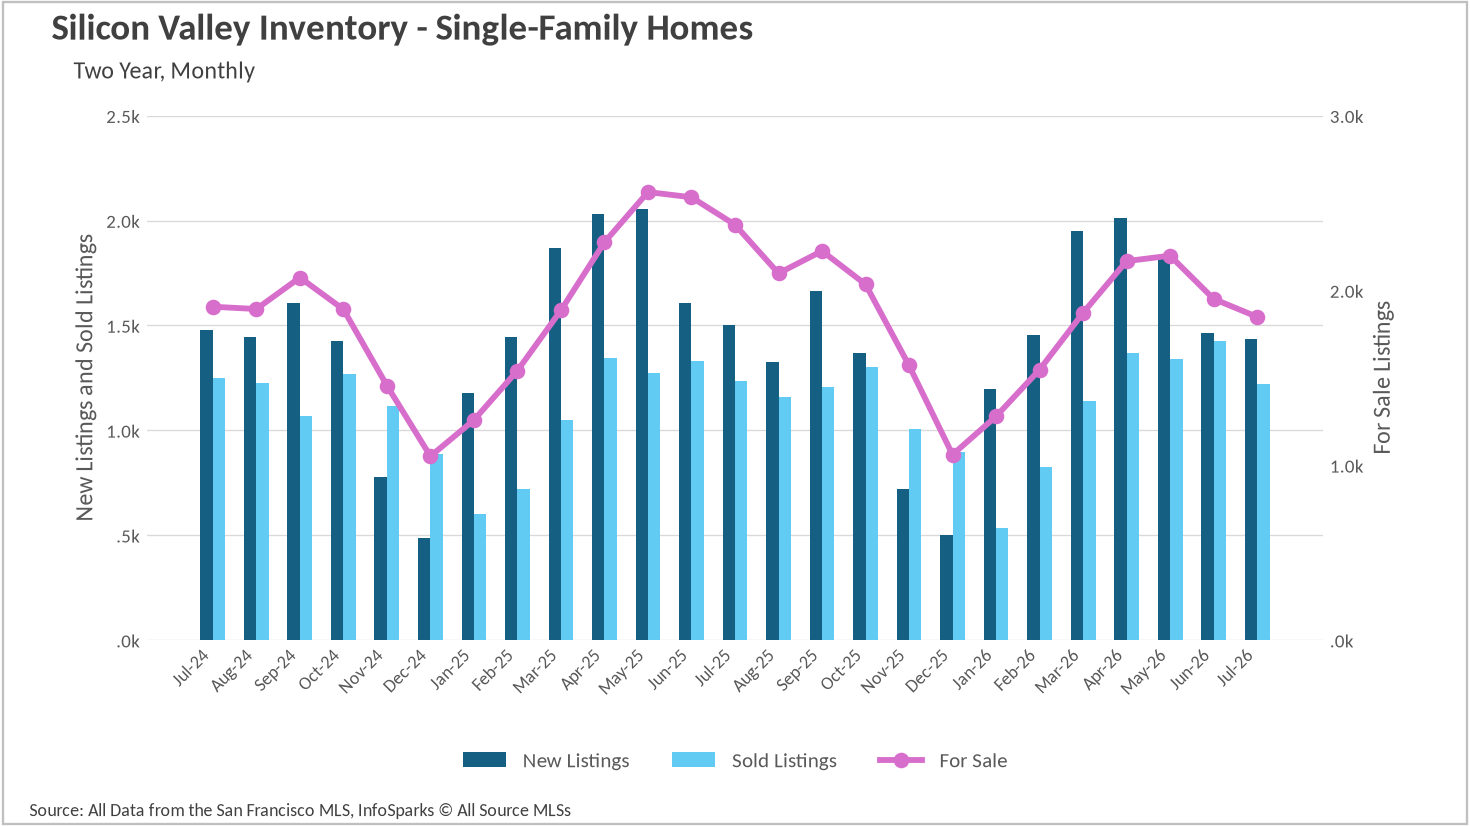
Every corner of the Bay Area is short of homes. Silicon Valley counted 1,849 single-family homes for sale in July, down 22.18% year over year and 5.28% from June. The East Bay closed the month at 2,659, off 24.70%. The North Bay saw the sharpest contraction, falling to 2,645 units, a 34.04% annual decline and 17.96% below June, the leanest July reading in that region's two-year series. San Francisco had just 154 single-family homes on the market, down 42.11% from 266 a year ago.

What makes this different from a demand story is that sales have held up. Roughly 3,750 single-family homes closed across the four subregions in July, and each region posted volume that was flat to slightly higher than last July. The shortfall is coming from sellers. New single-family listings fell 4.59% in Silicon Valley, 4.26% in the East Bay, and 24.98% in the North Bay, with only San Francisco bucking the trend at a 13.5% increase.
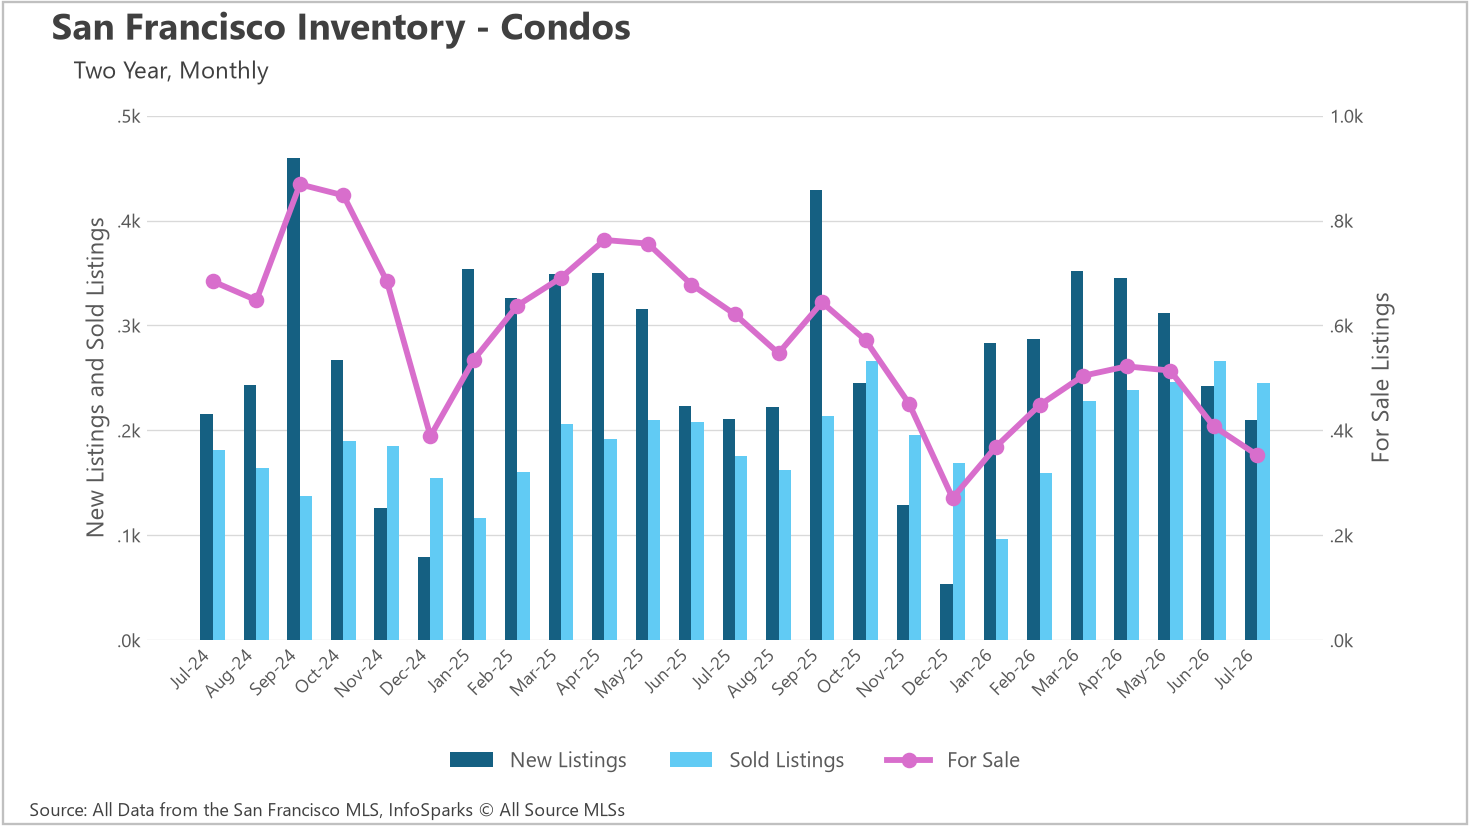
Condos are following the same trajectory for a different reason. Inventory fell 12.84% in Silicon Valley, 7.78% in the East Bay, 21.52% in the North Bay, and 43.16% in San Francisco, but closed condo sales rose in all four regions, including a 39.2% jump in San Francisco and 23.44% in Silicon Valley. Condo supply is thinning largely because buyers are finally absorbing it.

Two weeks in the core, six weeks in the outer ring

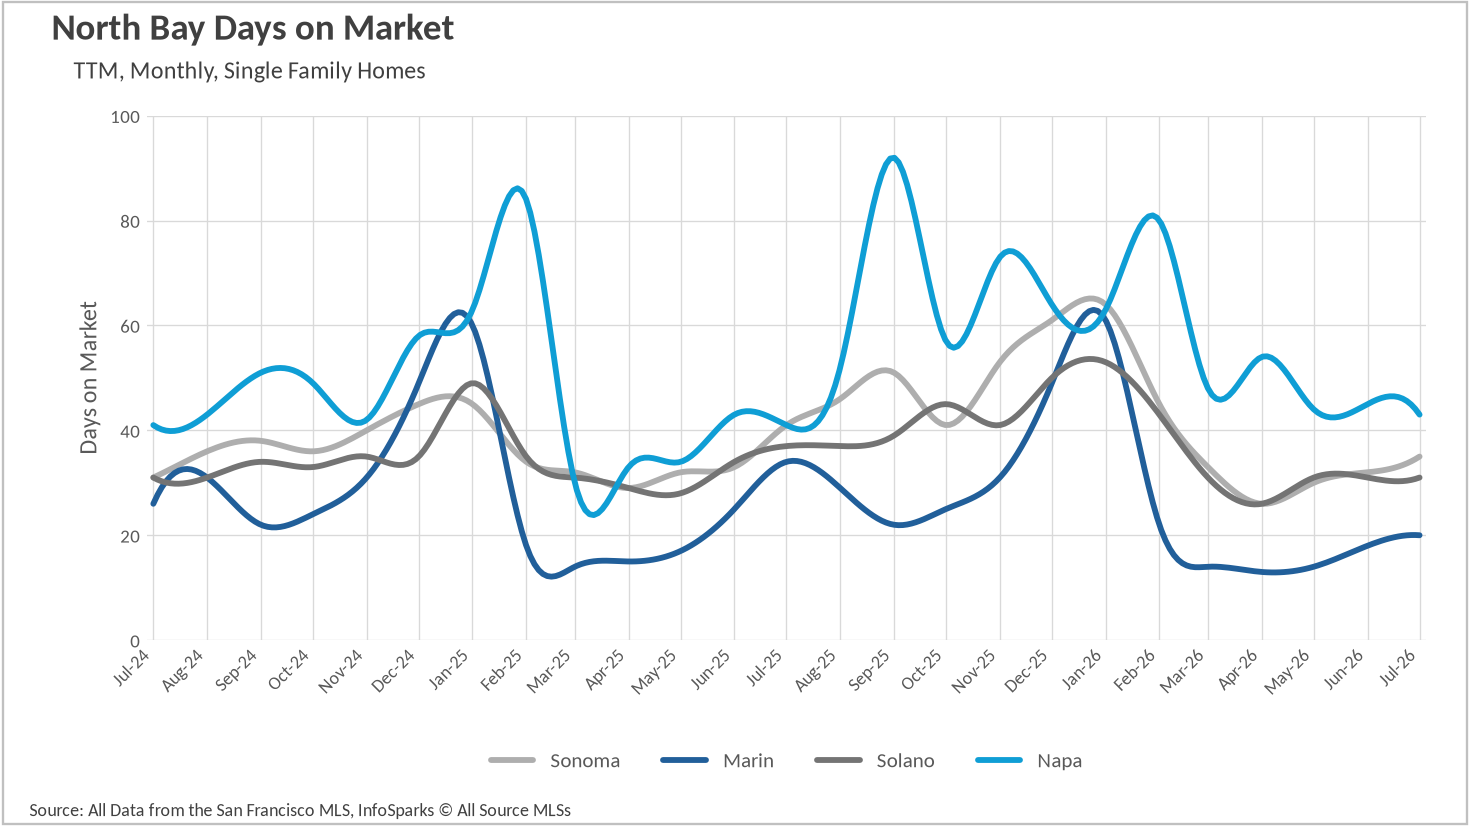
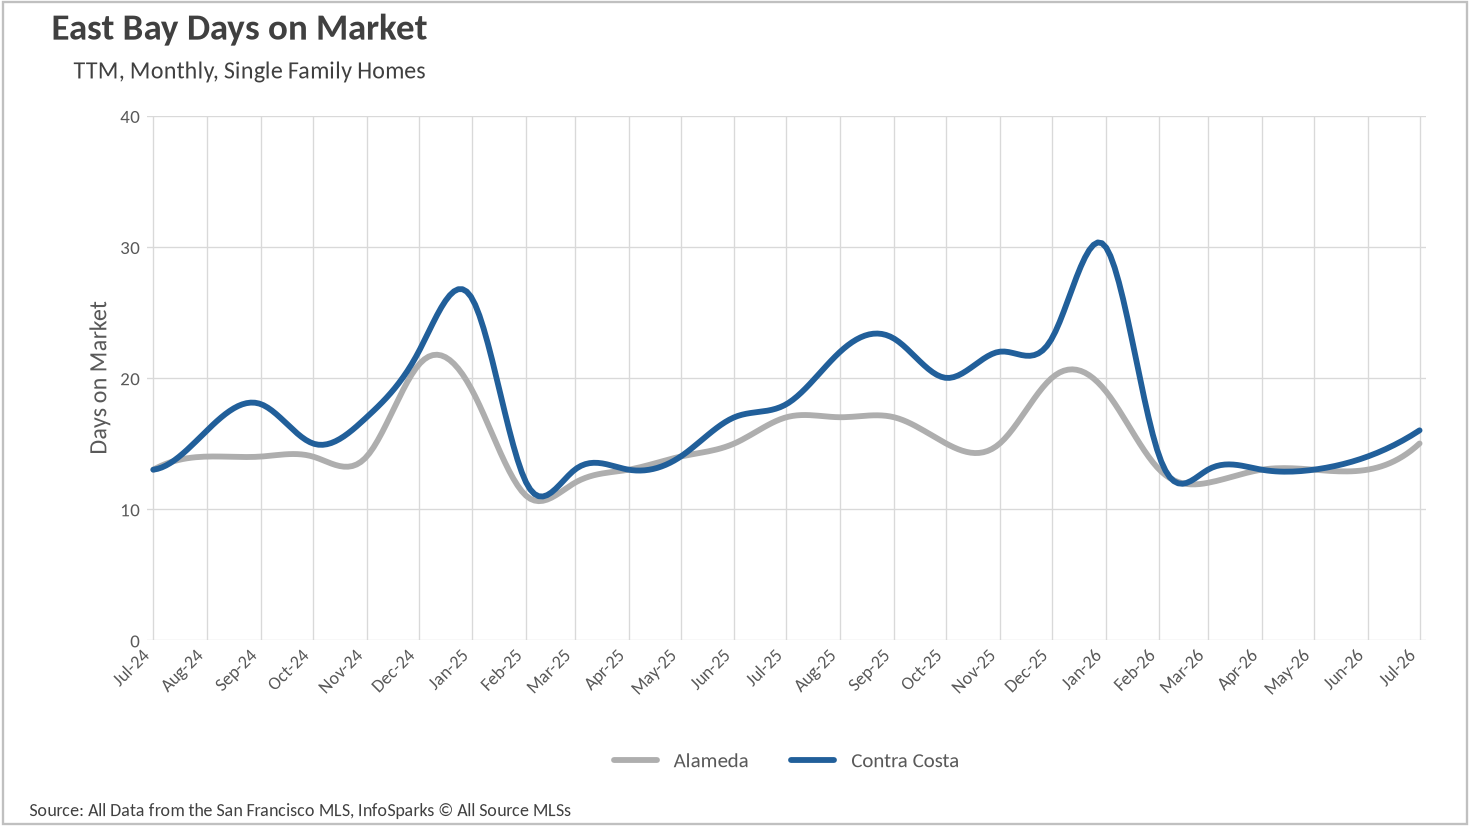
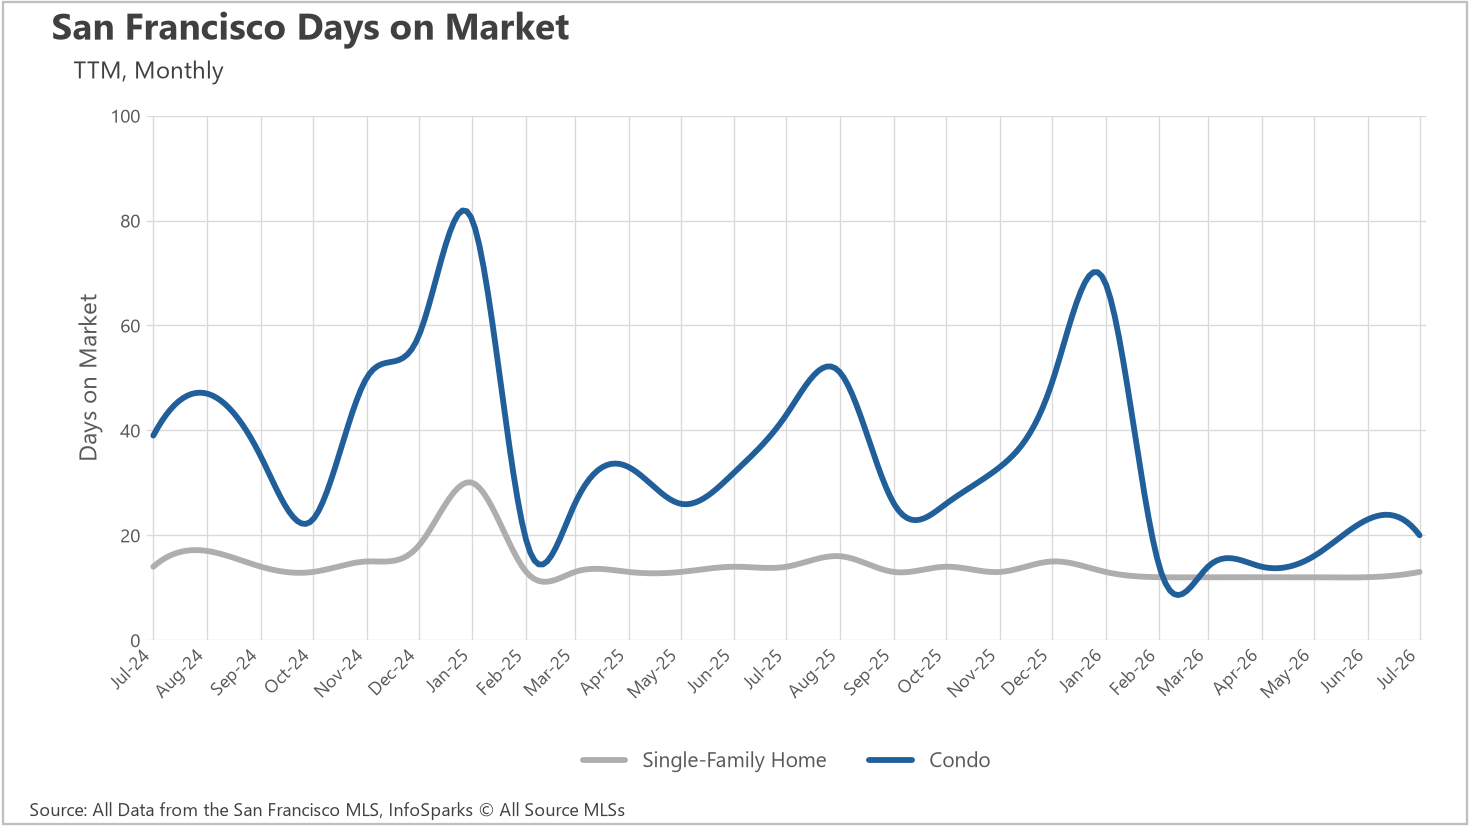
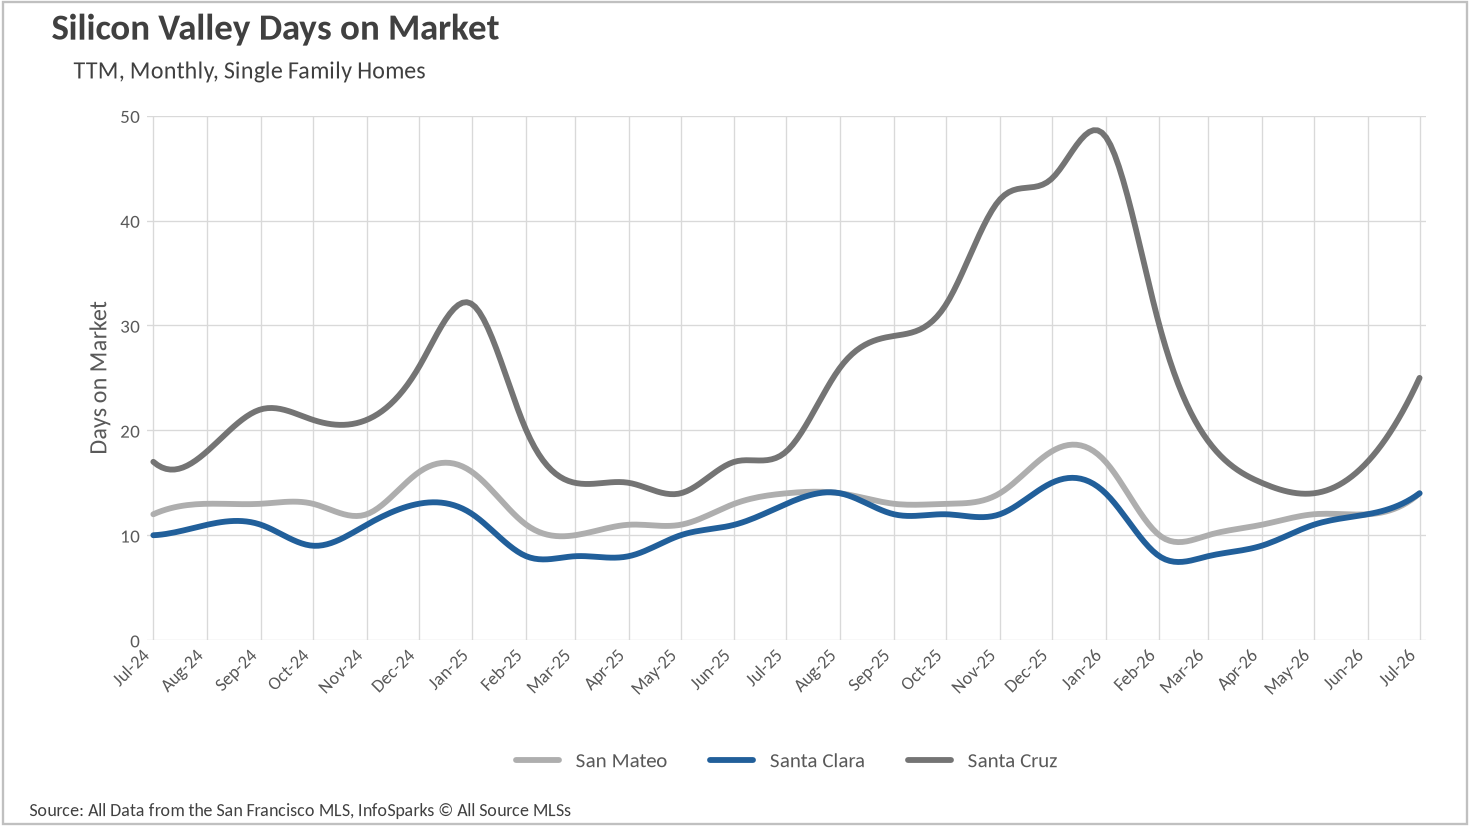
Marketing times form a clean gradient outward from the region's job centers. San Francisco single-family homes averaged 13 days on market, San Mateo and Santa Clara Counties both 14 days, Alameda 15, and Contra Costa 16. Marin County improved dramatically to 20 days, 41.18% faster than the 34 days it required last July. From there the clock stretches: Santa Cruz County at 25 days, Solano at 31, Sonoma at 35, and Napa the slowest in the region at 43 days.

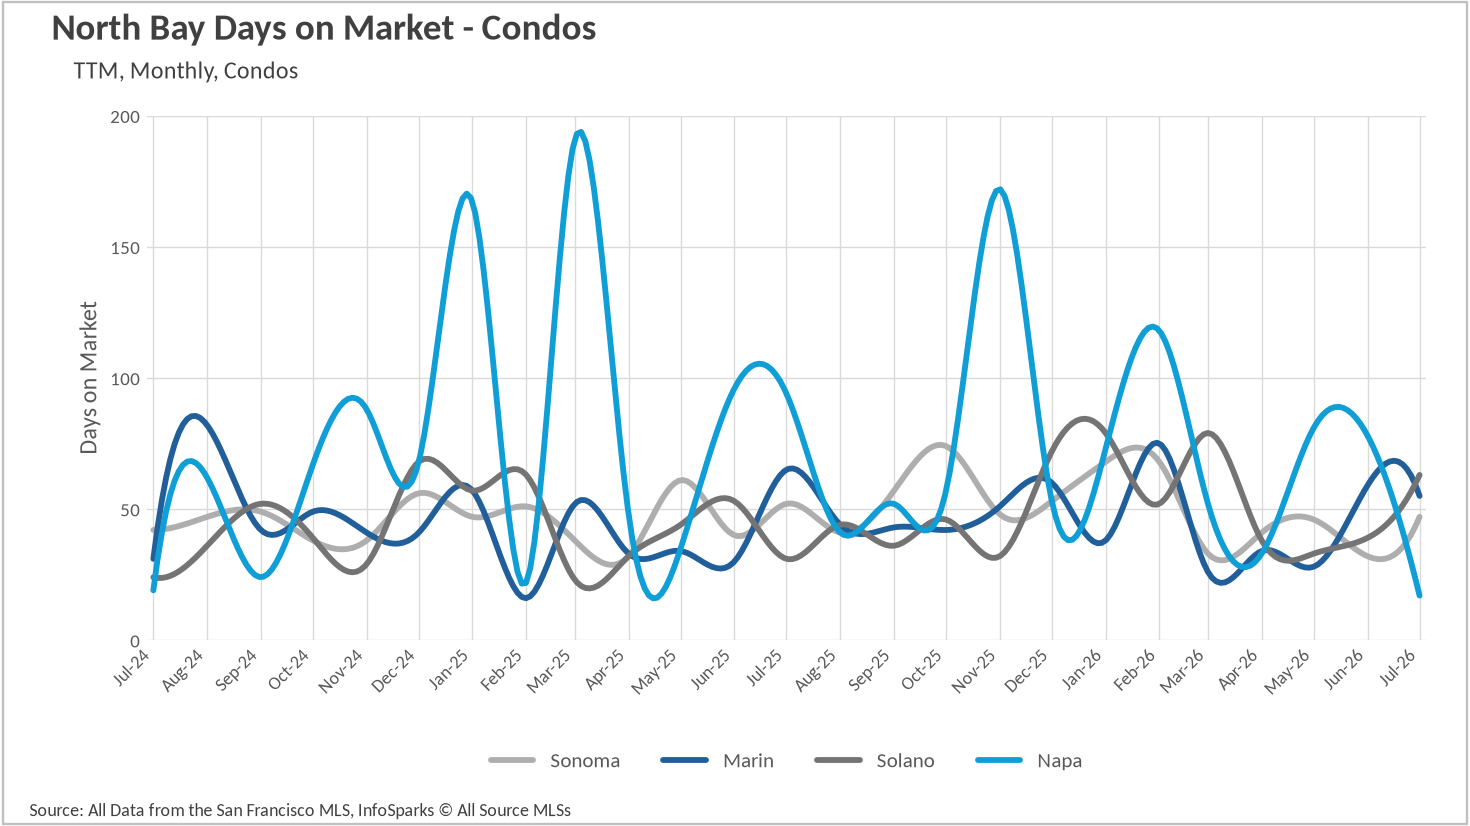
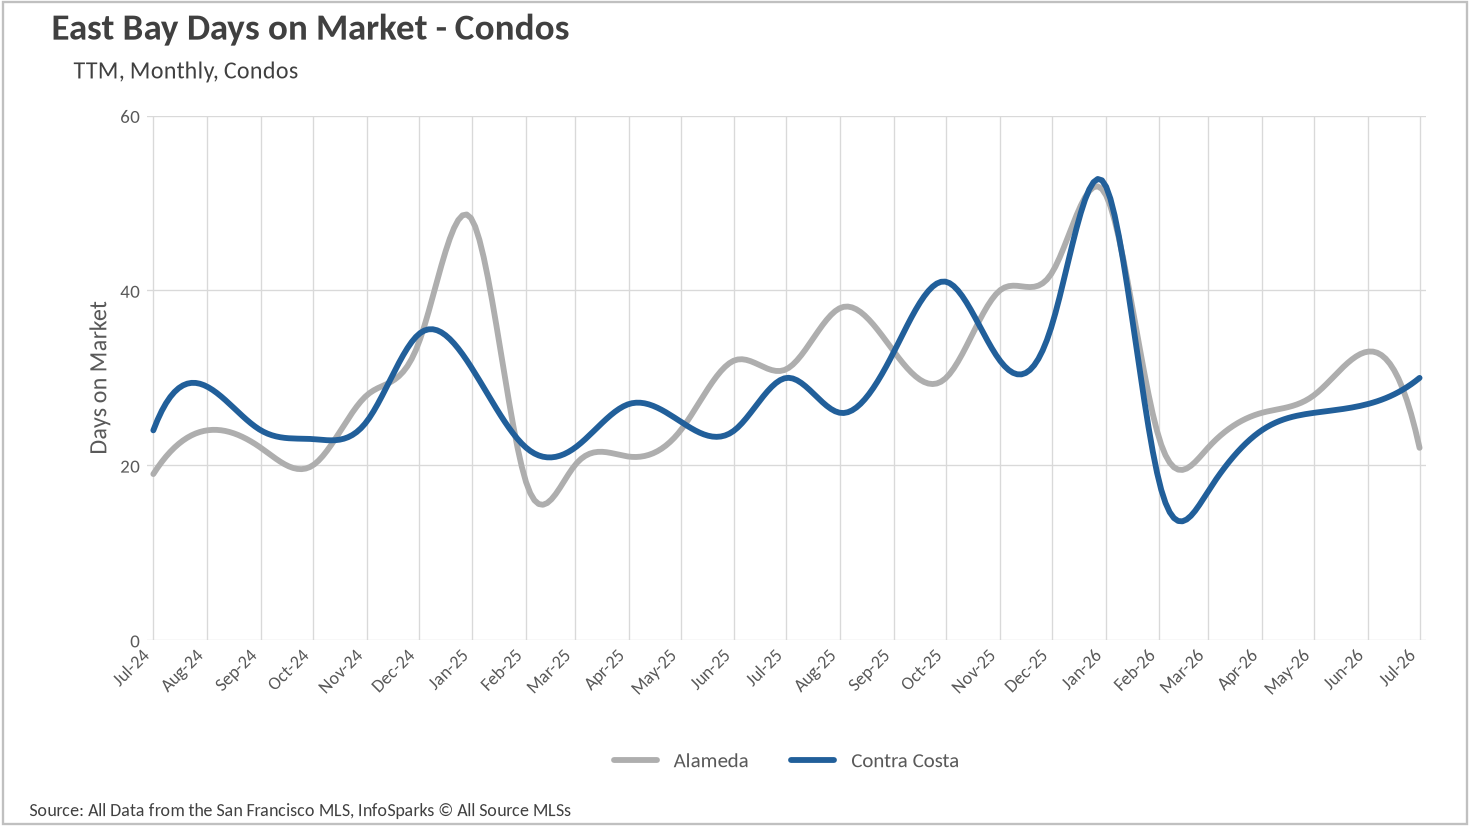
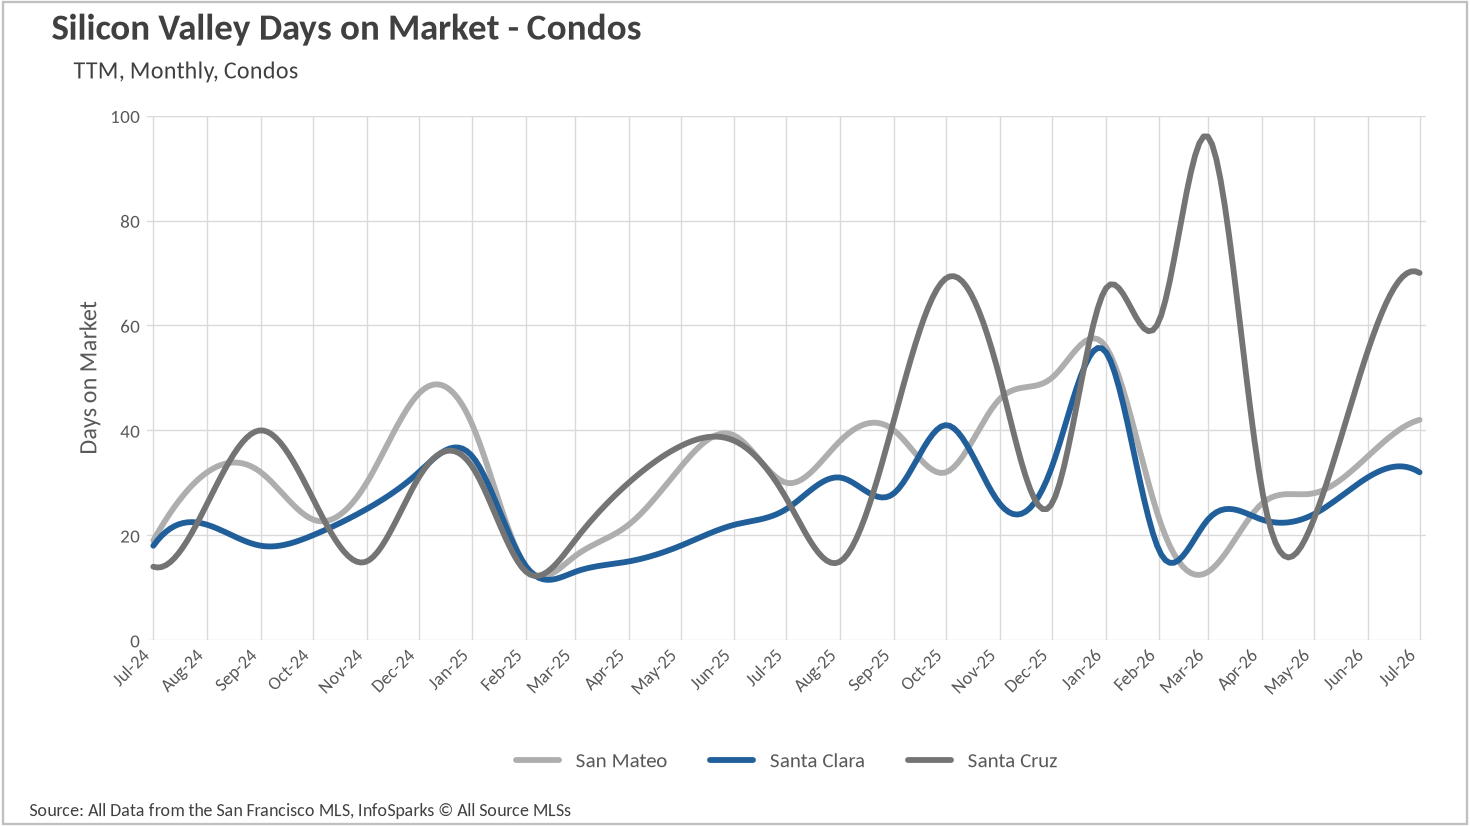
The condo side is where the regional divergence is widest. San Francisco condos averaged 20 days, down 53.49% from 43 days last July, and Alameda County condos improved 29.03% to 22 days, the fastest pace in more than two years there. At the other end, San Mateo County condos slowed to 42 days, Marin to 55, Solano to 63, and Santa Cruz County to 70 days, nearly triple last July's 27. Napa County's 17-day condo figure is the outlier of outliers and rests on very few closings. The practical lesson for sellers is that attached-housing timelines vary far more by location than single-family timelines do, and pricing strategy should reflect the local pace rather than the regional headline.

Sellers hold the cards across almost the entire region

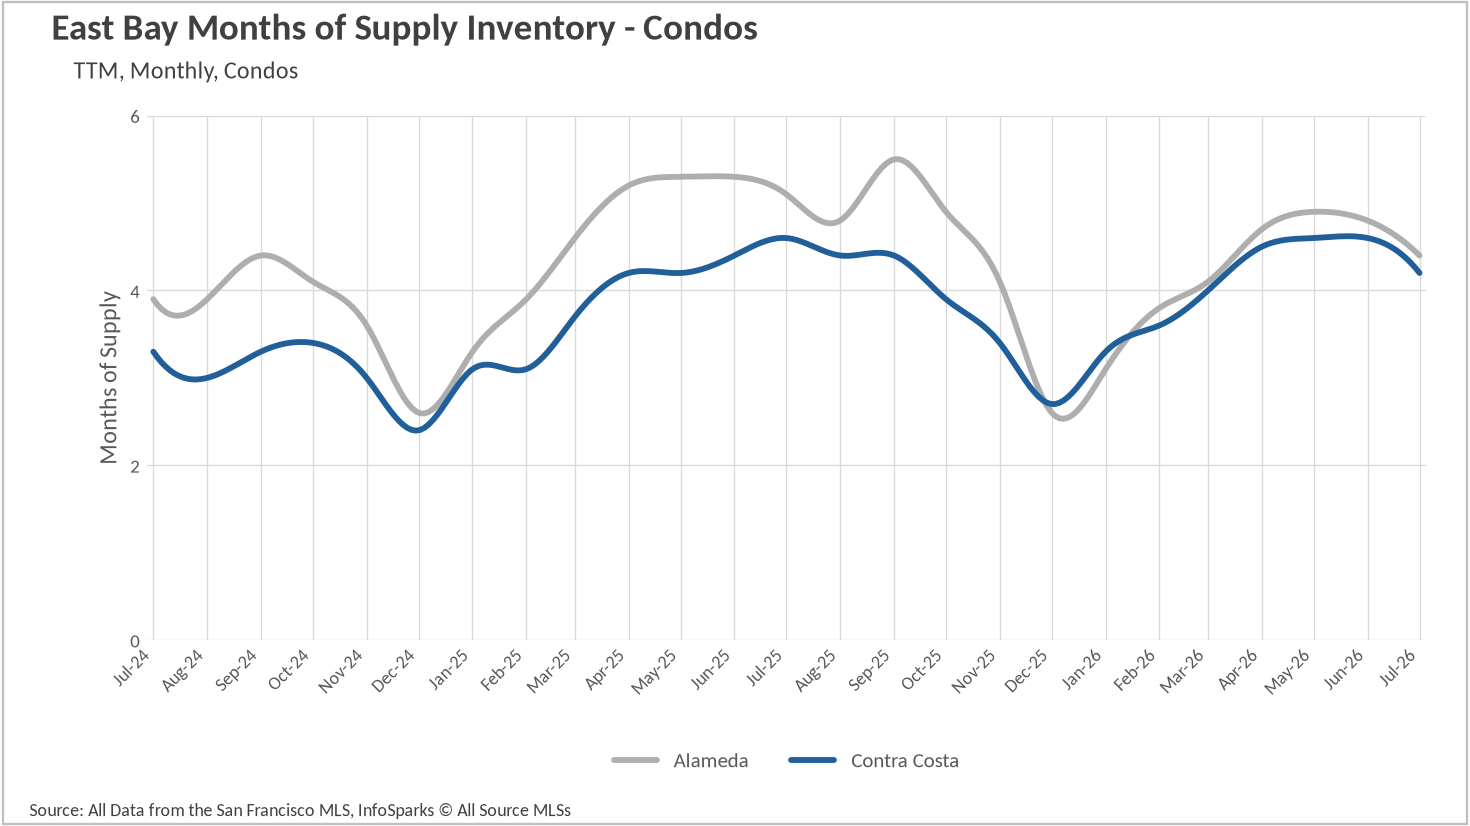
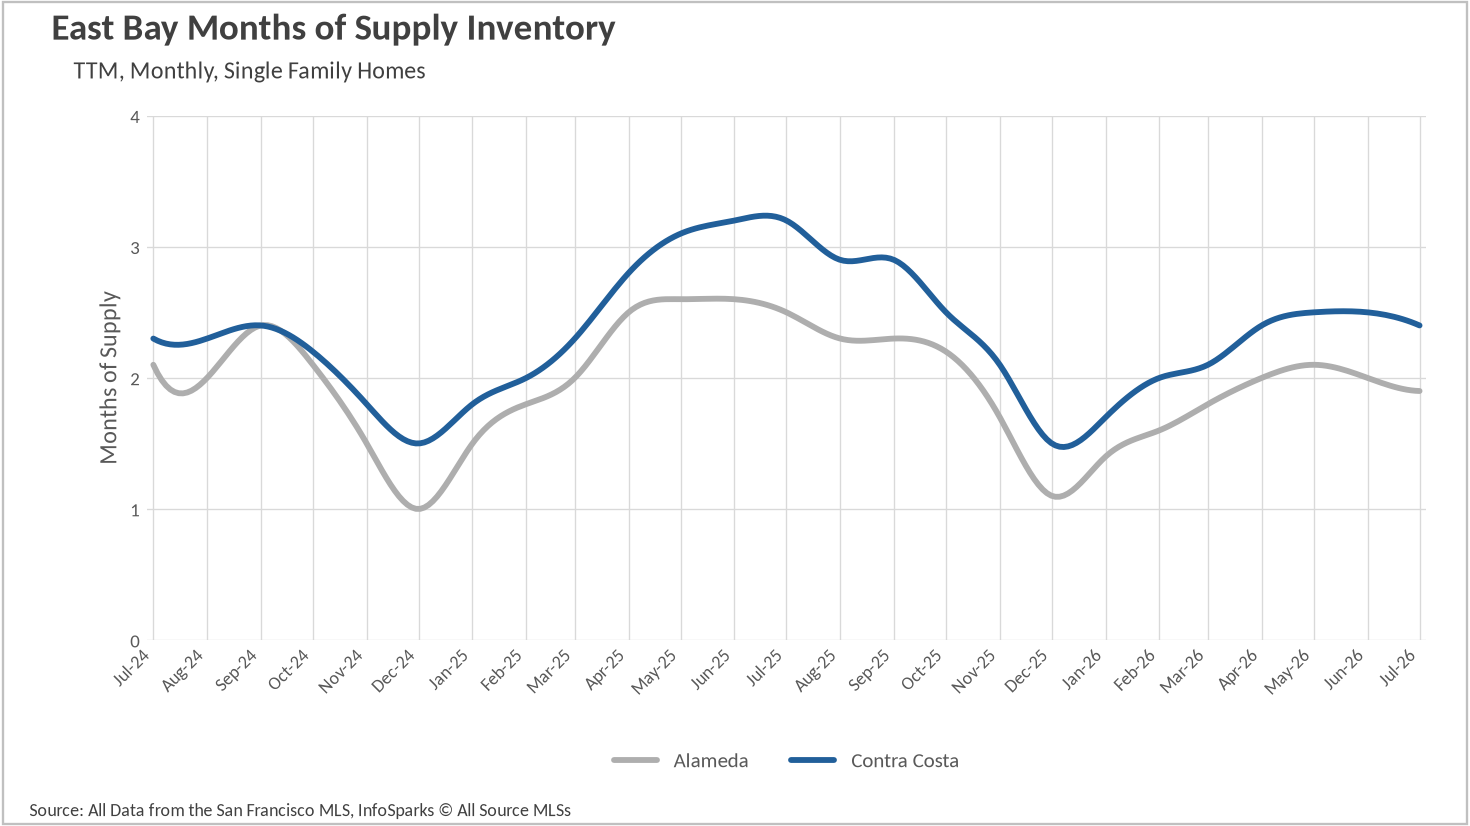
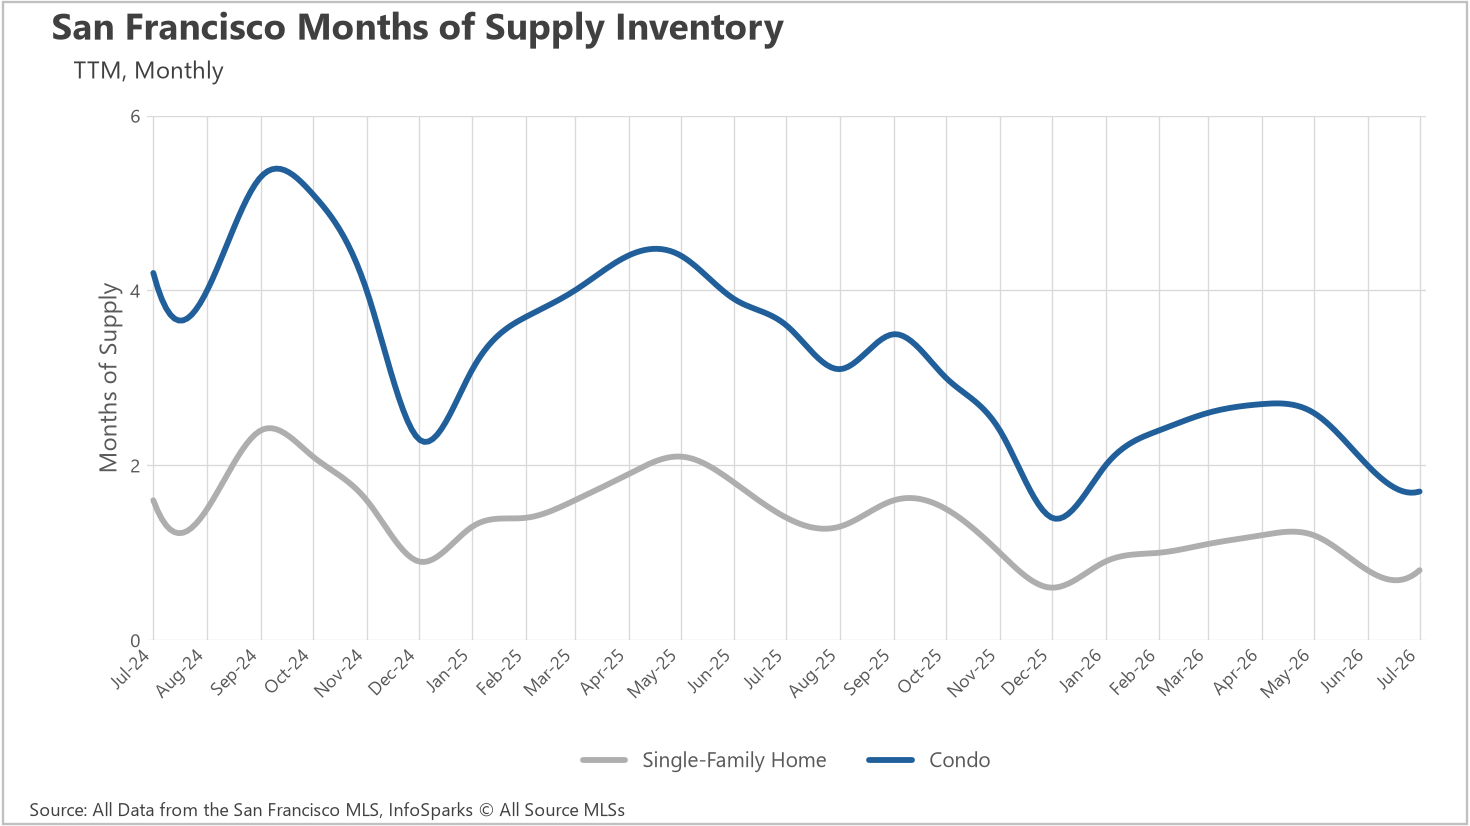
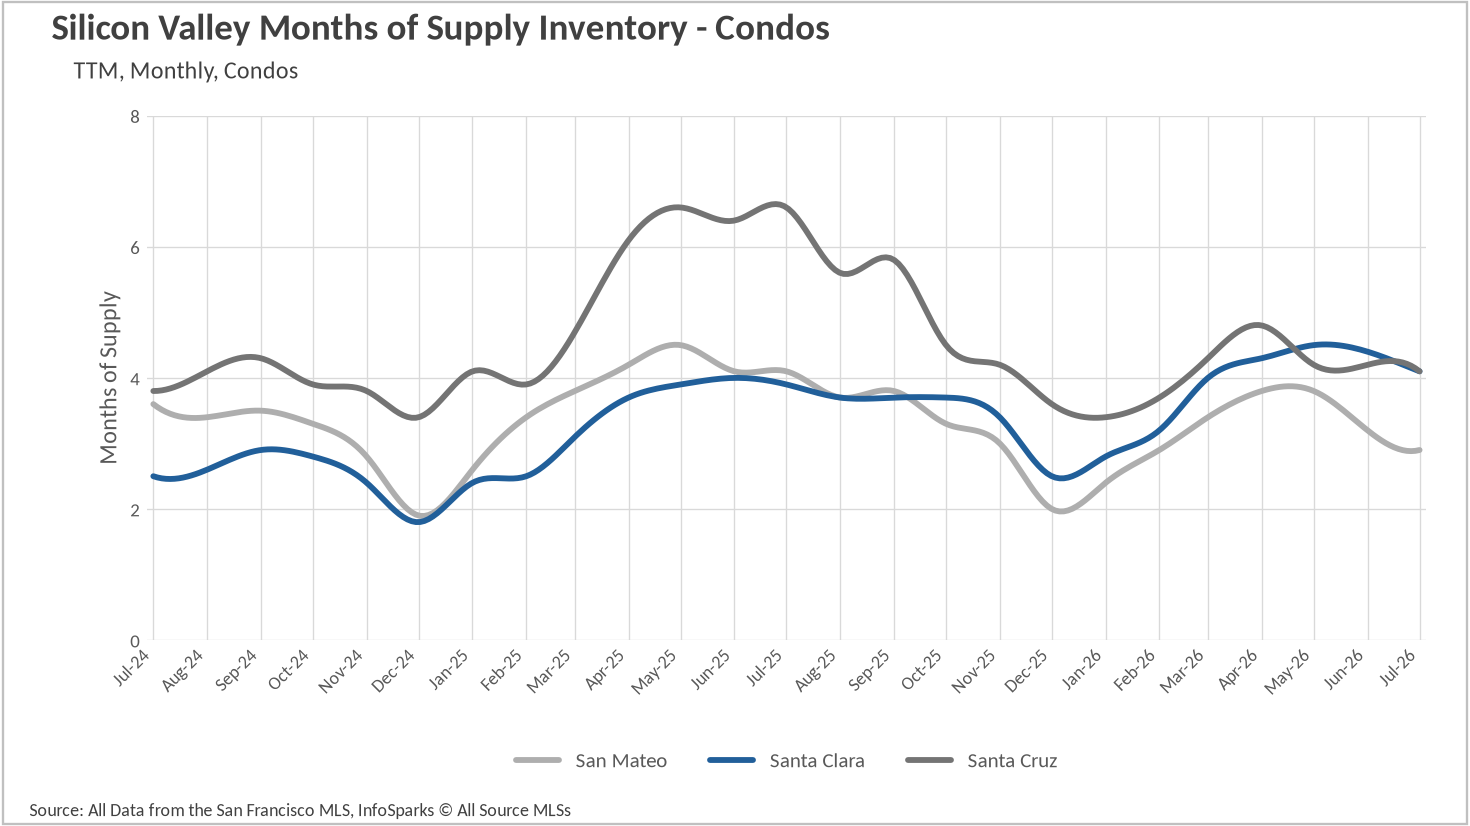
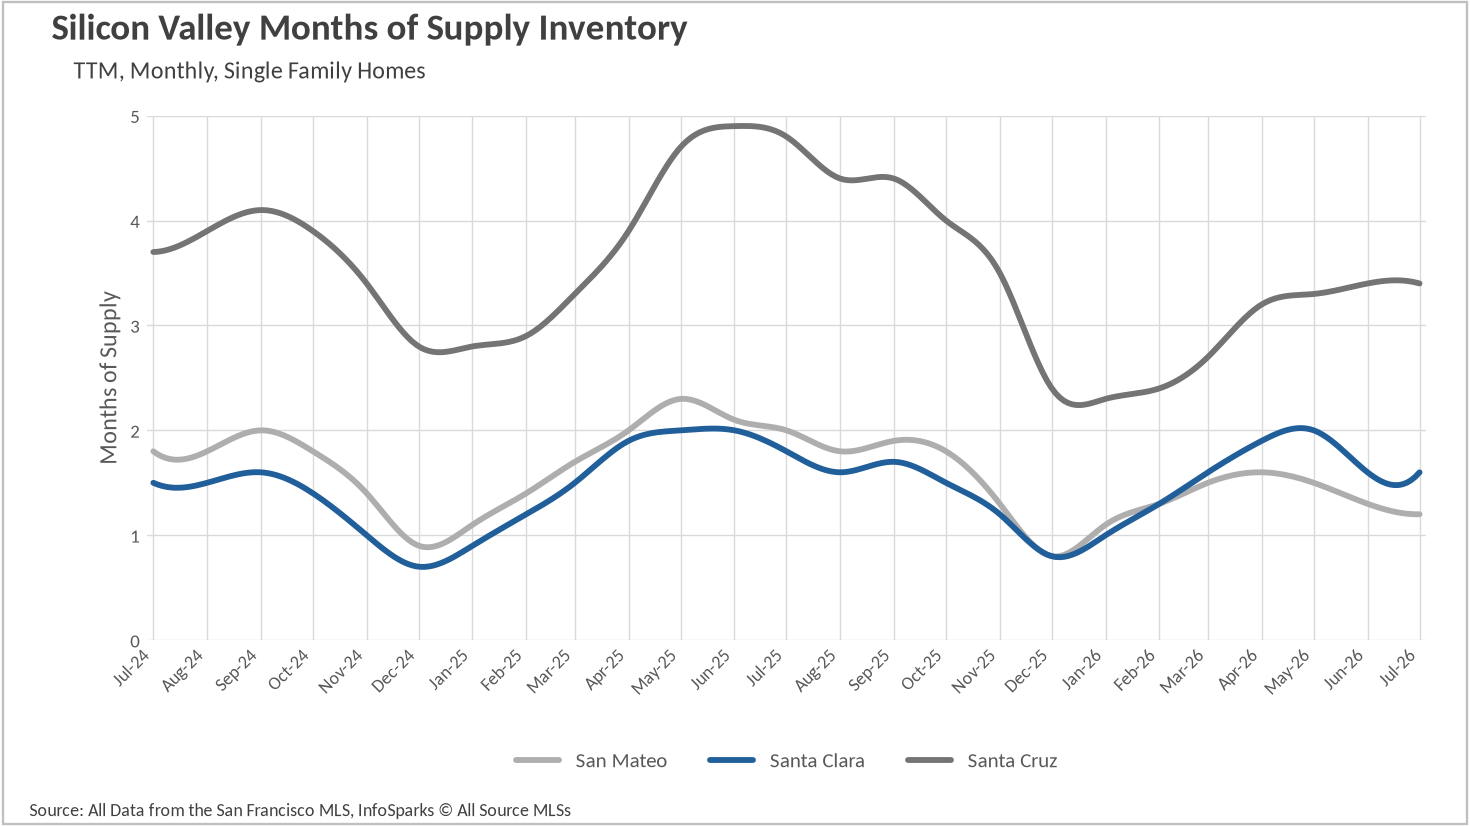
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.

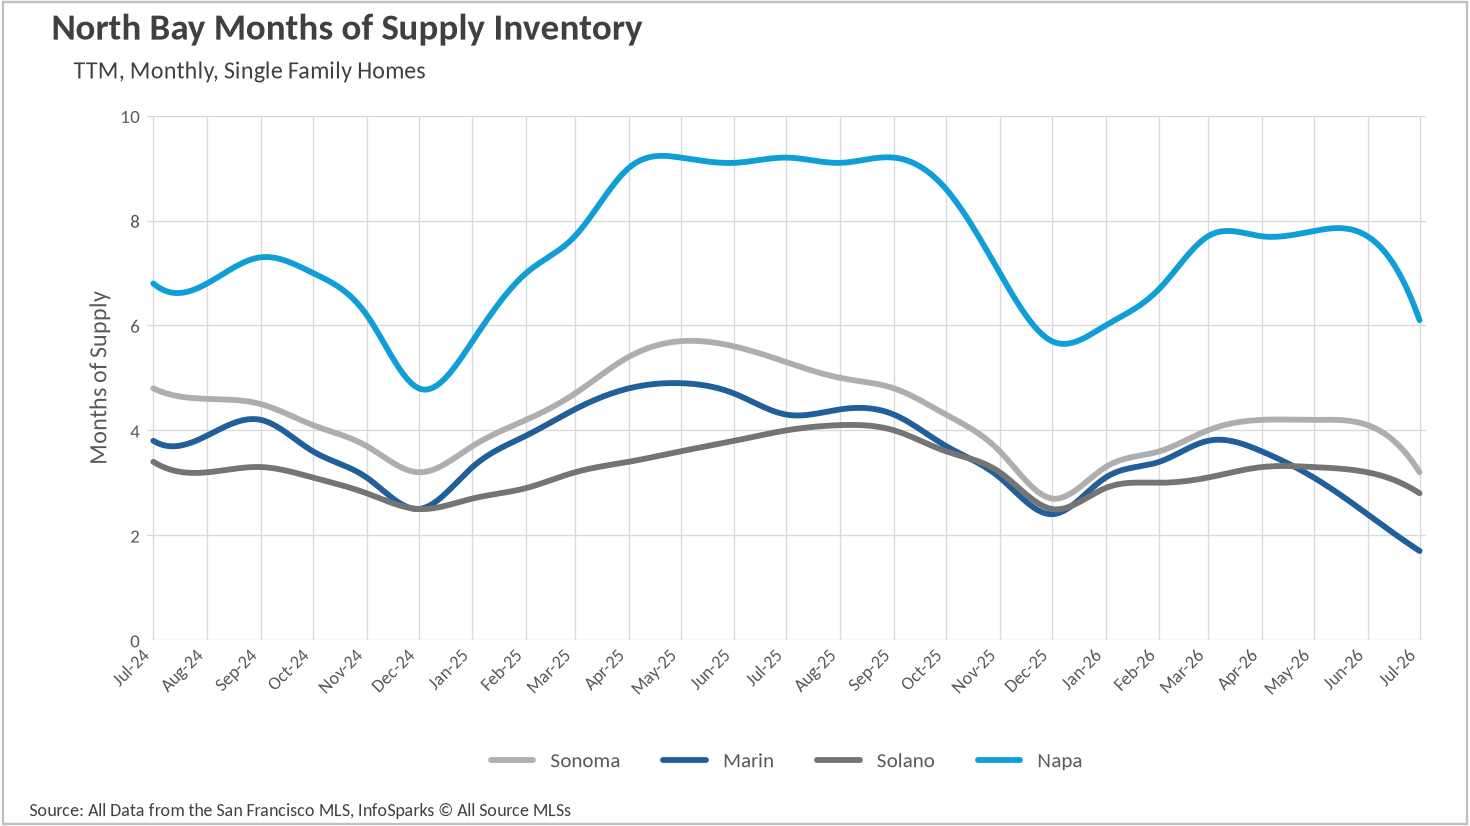
Measured that way, the Bay Area's single-family market is a seller's market almost without exception. San Francisco leads at 0.8 months of supply, down 42.86% year over year, followed by San Mateo at 1.2, Santa Clara at 1.6, Marin at 1.7, Alameda at 1.9, Contra Costa at 2.4, and Solano at 2.8 months. Sonoma County at 3.2 months and Santa Cruz County at 3.4 months sit right at the balanced threshold, both having compressed sharply from last July. Napa County, at 6.1 months, is the region's only true single-family buyers' market, and even that is down 33.70% from 9.2 months a year ago.

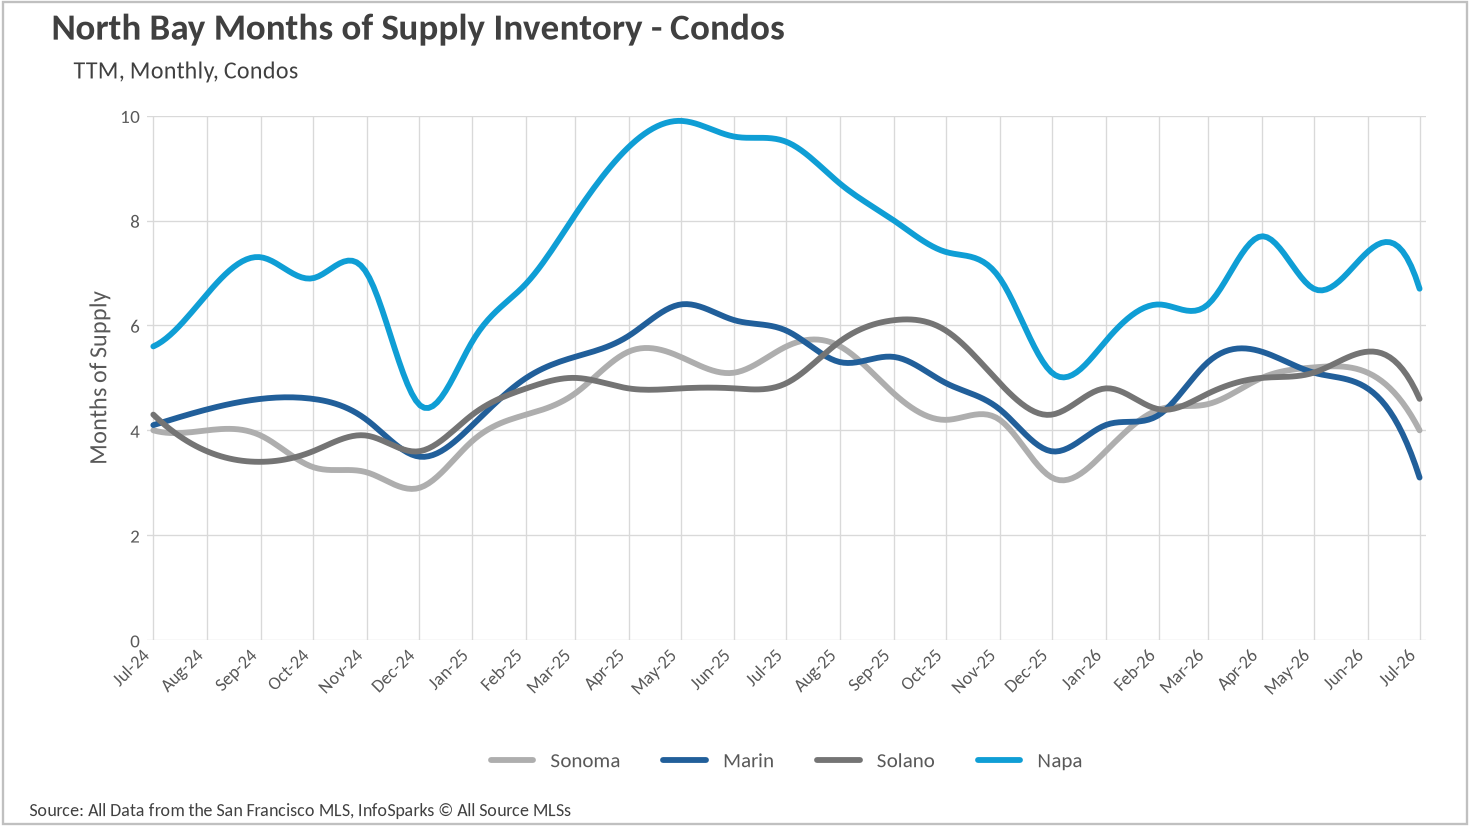
The condo segment still offers buyers more room, but the gap is narrowing quickly. San Francisco condos have moved all the way from 3.6 months of supply last July to 1.7 months now, and San Mateo County condos have tightened to 2.9 months. Marin County condos, at 3.1 months, are effectively balanced after sitting near 5.9 months a year ago. Buyers looking for genuine negotiating leverage will find it in Alameda County at 4.4 months, Solano at 4.6, Napa at 6.7, and in the 4.0 to 4.2 month range across Sonoma, Santa Clara, Santa Cruz, and Contra Costa Counties. Heading into the fall, the message for the region is consistent: single-family sellers are negotiating from strength, and condo buyers should act on the leverage they still have, because it has been eroding all summer.

Local Lowdown Data

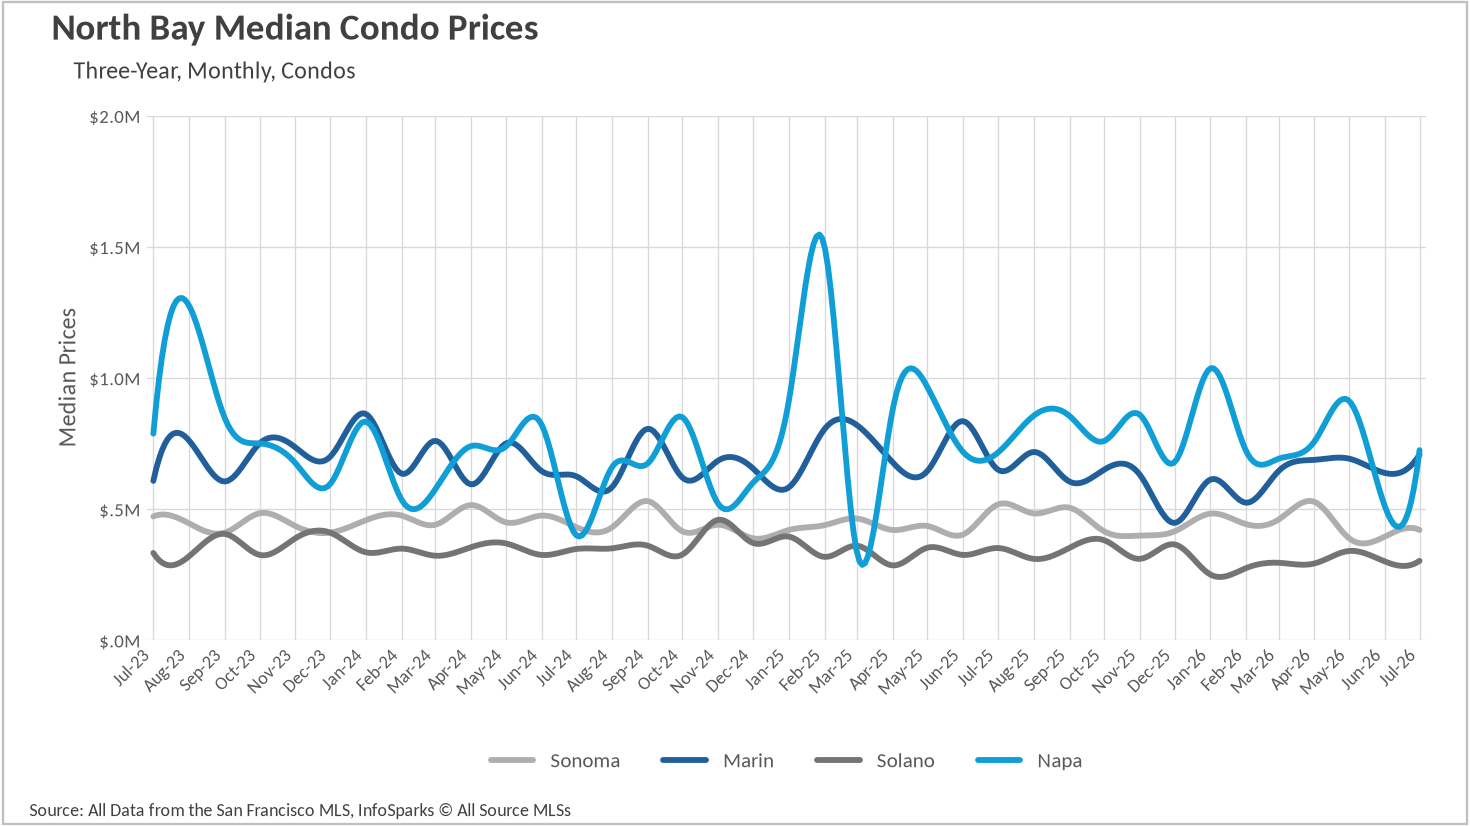
Line chart comparing monthly median condo prices in Sonoma, Marin, Solano, and Napa from July 2023 to July 2026.Line chart of North Bay home prices by county, July 2023–July 2026; Marin is highest and Solano lowest.Chart of year-over-year North Bay condo price changes by county, August 2025–July 2026; Napa shows the largest swings.Bar chart comparing year-over-year single-family home price changes across Sonoma, Marin, Solano, and Napa, August 2025–July 2026.North Bay condo inventory chart showing monthly new listings, sold listings, and listings for sale from July 2024 to July 2026.Chart of North Bay single-family home listings and homes for sale, July 2024 to July 2026.North Bay condo supply chart, July 2024–July 2026, with Napa consistently highest.Line chart of North Bay single-family home inventory, July 2024–July 2026; Napa leads, while Marin falls to 1.7 months.Line chart of North Bay condo days on market by county, July 2024–July 2026; Napa fluctuates most.Line chart compares North Bay counties’ monthly days on market, July 2024–July 2026; Napa fluctuates most.Line chart of monthly East Bay condo prices, comparing Alameda and Contra Costa from July 2023 to July 2026.Line chart of East Bay single-family home prices, July 2023–July 2026; Alameda prices exceed Contra Costa prices.East Bay condo price-change chart: Alameda declines through June; Contra Costa swings from losses to gains.Bar chart comparing East Bay single-family home price changes in Alameda and Contra Costa, August 2025–July 2026.Chart of East Bay condo listings from July 2024 to July 2026, comparing new, sold, and for-sale listings.East Bay single-family home inventory chart comparing monthly new listings, sold listings, and homes for sale from July 2024 to July 2026.Line chart of East Bay condo supply, comparing Alameda and Contra Costa from July 2024 to July 2026.Line chart compares monthly single-family home inventory in Alameda and Contra Costa counties, July 2024–July 2026.Line chart compares monthly condo days on market in Alameda and Contra Costa from July 2024 to July 2026.East Bay days-on-market chart comparing Alameda and Contra Costa single-family homes from July 2024 to July 2026.Chart comparing monthly San Francisco median prices for single-family homes and condos, July 2023–July 2026.Chart of year-over-year San Francisco home and condo median price changes, August 2025–July 2026.Chart comparing San Francisco single-family home and condo prices as percentages of original price, July 2023–July 2026.Chart of San Francisco condo inventory, showing monthly new listings, sales, and for-sale listings from July 2024 to July 2026.Chart of San Francisco single-family home listings and sales from July 2024 to July 2026.San Francisco monthly housing inventory chart, July 2024–July 2026, comparing condos with single-family homes.San Francisco days-on-market line chart comparing single-family homes and condos, July 2024–July 2026.Line chart of Silicon Valley median condo prices by county, July 2023–July 2026.Line chart comparing monthly median single-family home prices in San Mateo, Santa Clara, and Santa Cruz counties, July 2023–July 2026.Bar chart comparing monthly year-over-year condo price changes in San Mateo, Santa Clara, and Santa Cruz counties.Bar chart of Silicon Valley home price changes by county, August 2025–July 2026; San Mateo rises most in July.Silicon Valley condo inventory chart comparing monthly new, sold, and for-sale listings, July 2024–July 2026.Chart of Silicon Valley single-family home listings, July 2024–July 2026, with new, sold, and for-sale inventory.Line chart of monthly condo inventory in San Mateo, Santa Clara, and Santa Cruz, July 2024–July 2026.Line chart compares monthly single-family home inventory in San Mateo, Santa Clara, and Santa Cruz counties, July 2024–July 2026.Line chart of condo days on market in San Mateo, Santa Clara, and Santa Cruz, July 2024–July 2026.Line chart comparing monthly single-family home days on market in San Mateo, Santa Clara, and Santa Cruz counties.

We Would Love to Meet You!

You’ve got questions and we can’t wait to answer them.