Real Estate Market Report: November 2023

Michelle Kim  |  December 1, 2023
Real Estate Market Report: November 2023

The Big Story

Fed policy is working, but mostly just on housing

Quick Take:
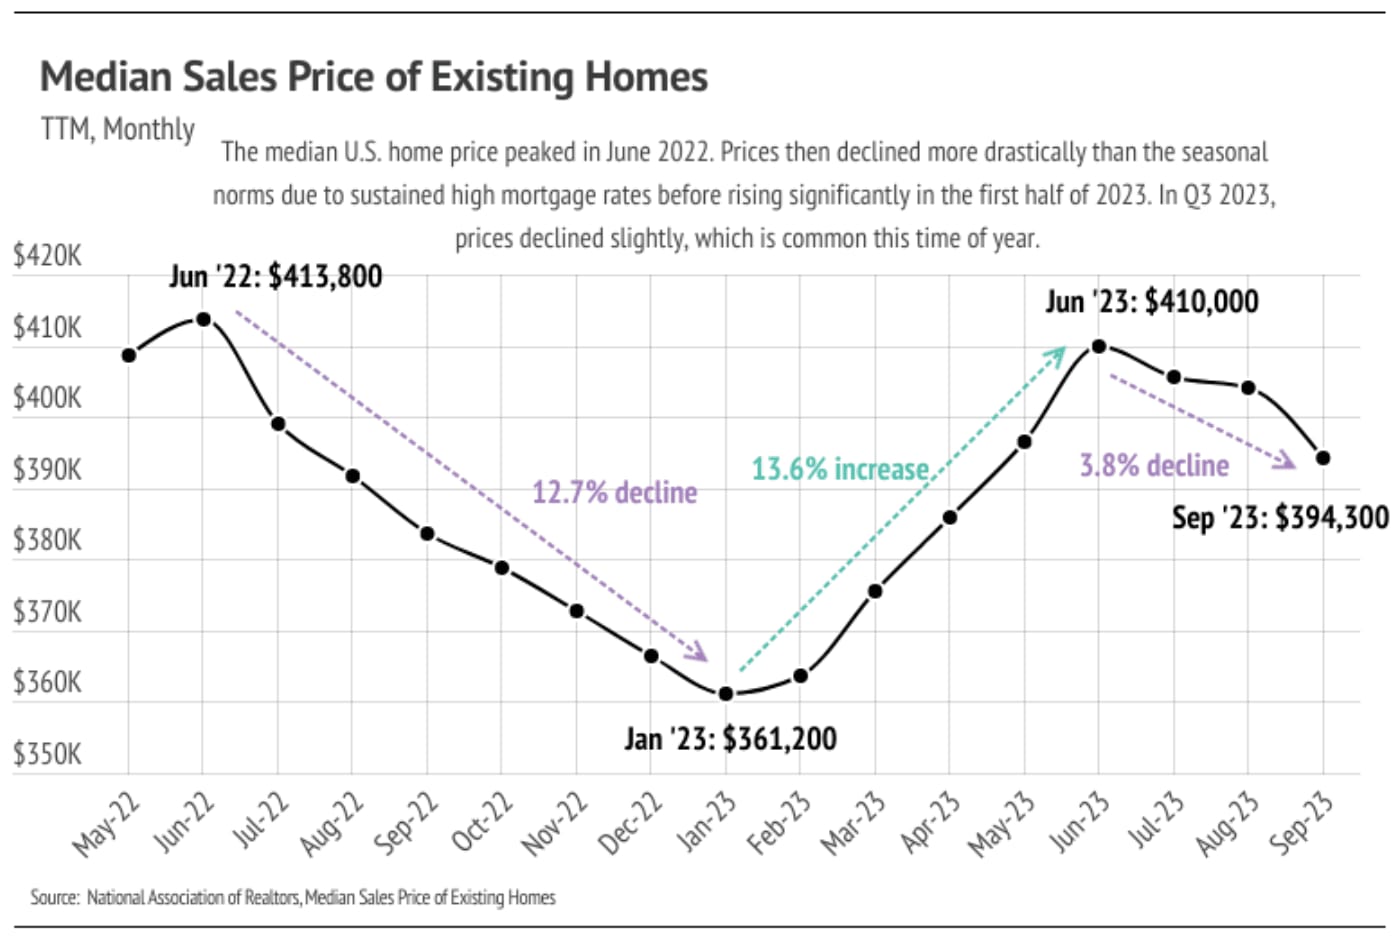
  • The national median home price declined 3.8% in the third quarter, landing only 4.7% below the all-time high reached in June 2022 and reflecting typical seasonal trends. Prices didn’t contract significantly in Q3 2023 despite mortgage rates rising 0.6%.
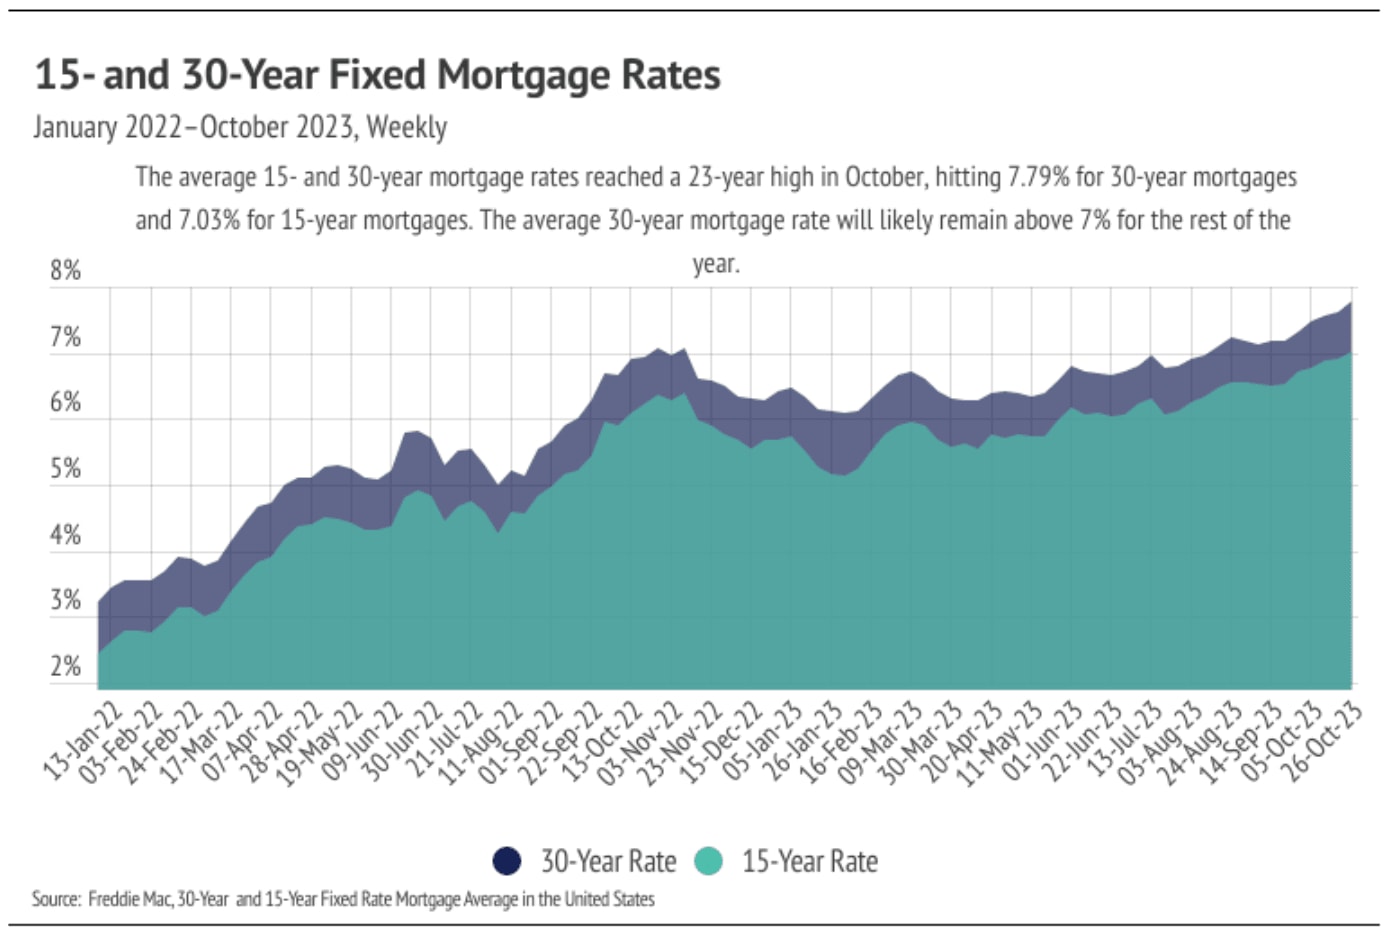
  • In October, the average 30-year mortgage rate reached its highest level since October 2020 at 7.79%. Higher and higher rates continue to price potential buyers out of the market and prevent sellers who are locked into hyper-low rates from entering the market.
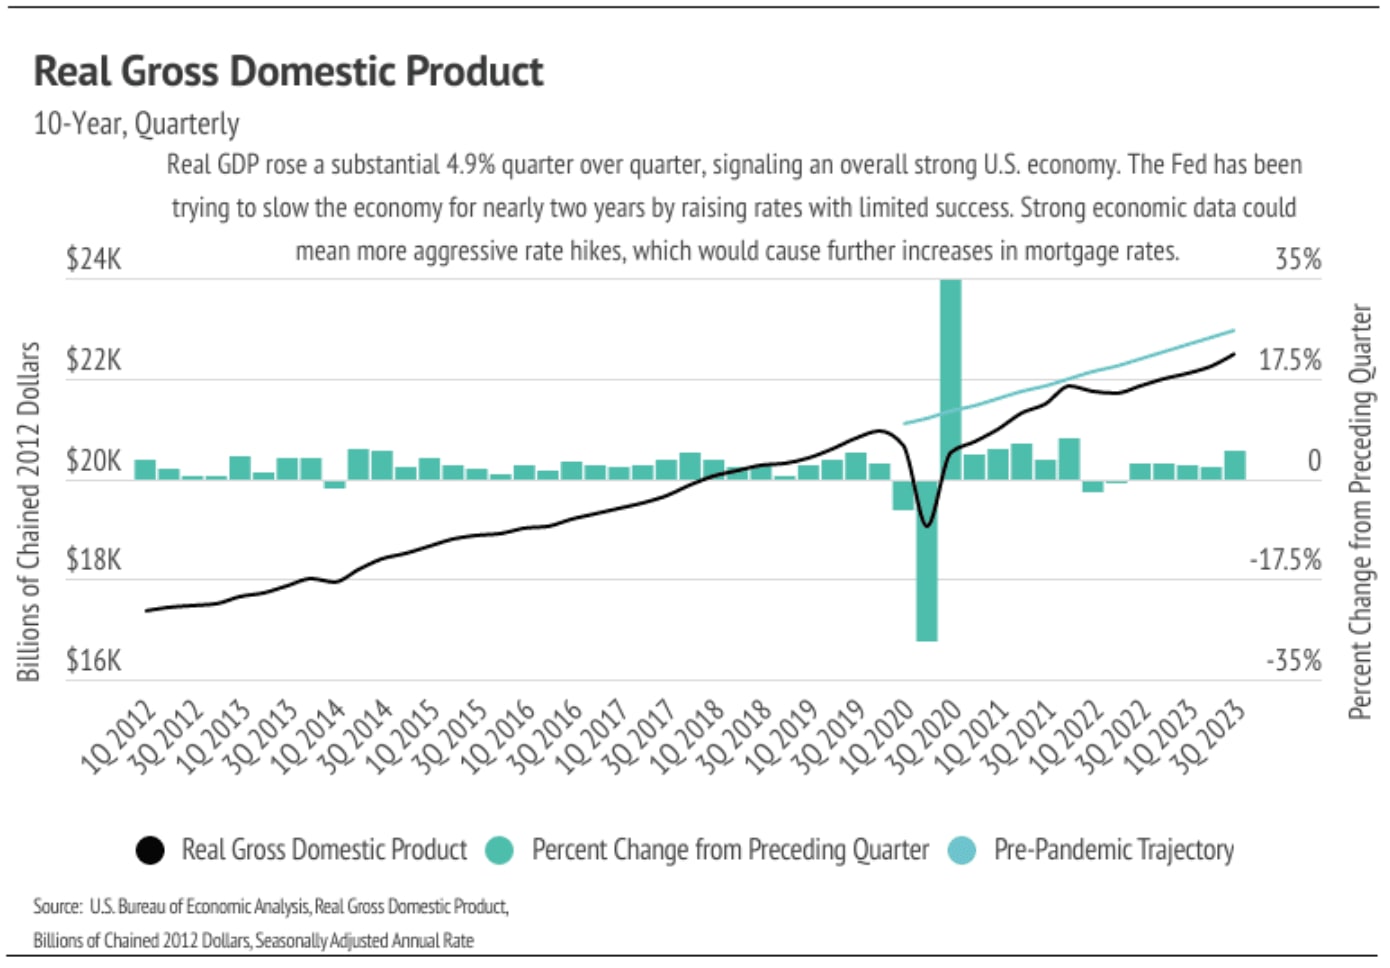
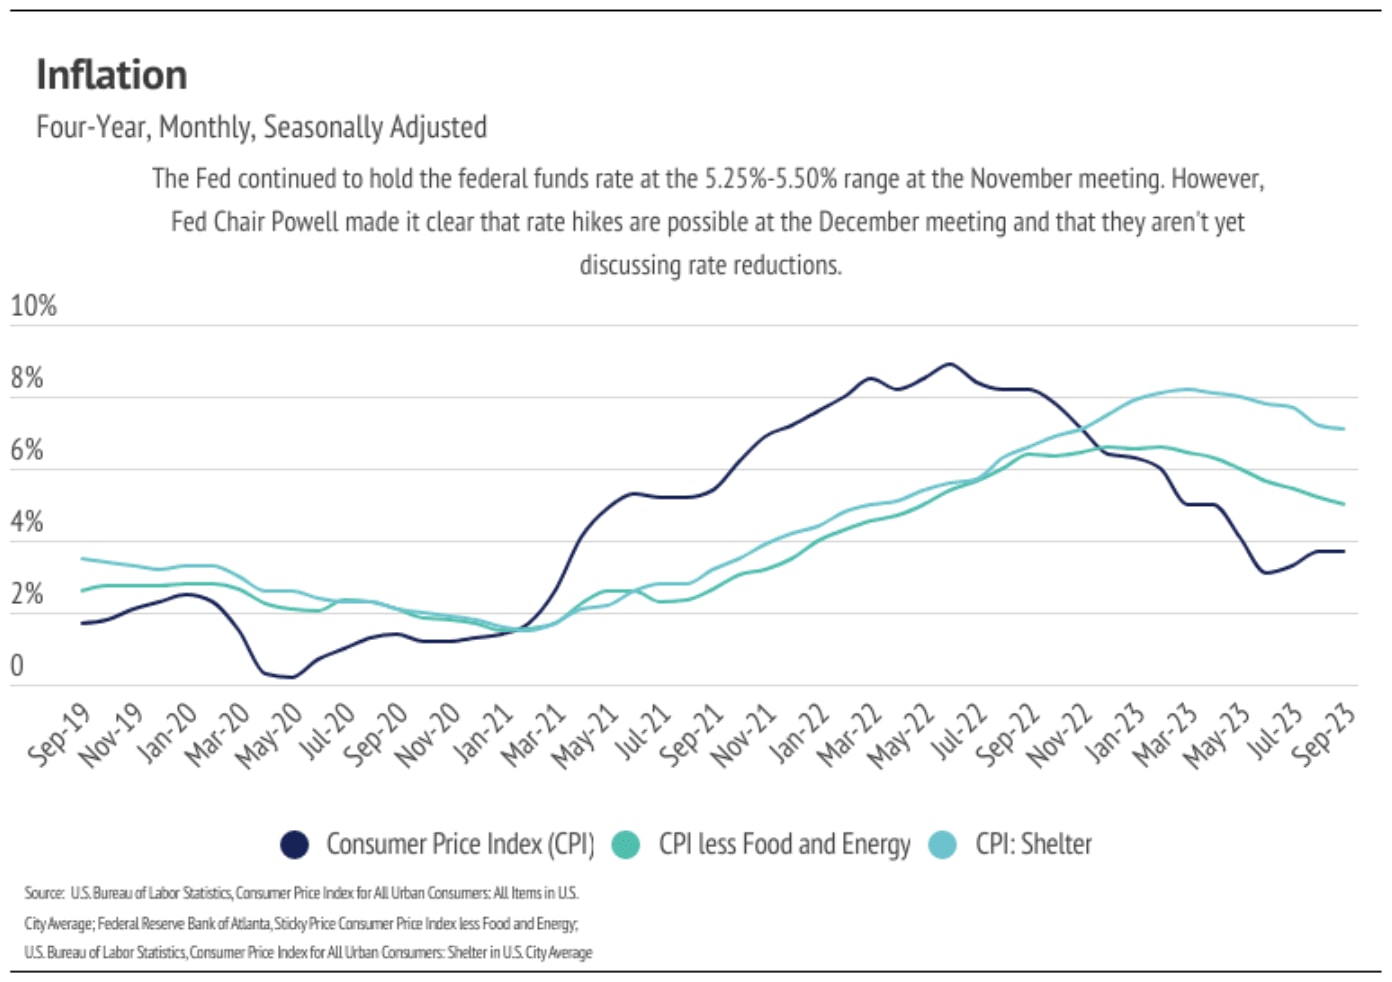
  • The Q3 Real Gross Domestic Product (inflation-adjusted GDP) rose 4.9% quarter over quarter, indicating a broadly strong economy. Although unemployment rose 0.3% to 3.9%, the jobs market remains robust. Inflation, which rose in Q3, is nearly double the Fed’s target rate of 2%, so rate reductions won’t happen in the near future.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
 

It’s all about interest rates

Home prices remain near all-time highs, largely due to the sustained low inventory levels, and despite the average 30-year mortgage rate hitting a 23-year high in October at 7.79%. It’s hard to overstate the full significance of higher mortgage rates on the housing market; but, in short, they are the primary driver of market slowdown. For example, when accounting for the cost of financing a mortgage, a buyer’s monthly cost for a median home today is actually 11% higher than in June 2022 when prices were at their peak. Looking further back to when the Fed began to raise rates at the beginning of 2022, the median monthly cost of a home has increased 76% from then until now.
 
So why have prices stayed elevated even as the cost of financing has skyrocketed over the past 22 months? For sellers, prices have to stay high or else they wouldn’t enter the market. Approximately 75% of U.S. homeowners have mortgage rates of less than 4%, according to JPMorgan, which has kept sellers from entering the market. If prices broadly contracted, even fewer sellers would come to market because they likely couldn’t afford a new house because their profit margin would be too low. Although people move for all sorts of reasons, generally speaking, there are very few sellers who are selling because they have no choice. Even if sellers were breaking even on their home sale, transitioning from a sub 4% mortgage to a nearly 8% rate is completely unappealing. Sellers who are coming to market now need to make a profit so that they can finance less of their next home in order to counteract the higher mortgage rate. Of course, this is for existing homes, but new construction isn’t much different. Material and financing costs are higher for homebuilders, too, and when a house costs more to build, the prices increase as well.
 
Inflation isn’t helping the market, either. People feel less wealthy than they did three years ago, and they’re right to feel that way. In just the three years from September 2020 to September 2023, the dollar has lost about 15% of its buying power, the same amount it lost over the preceding 10 years (September 2010 to September 2020). Even though inflation is declining, all that means is that prices are rising more slowly than last year — which is good, but it doesn't make anything more affordable. The combination of declining purchasing power and higher mortgage rates only reduces market participants, slowing the market.
 
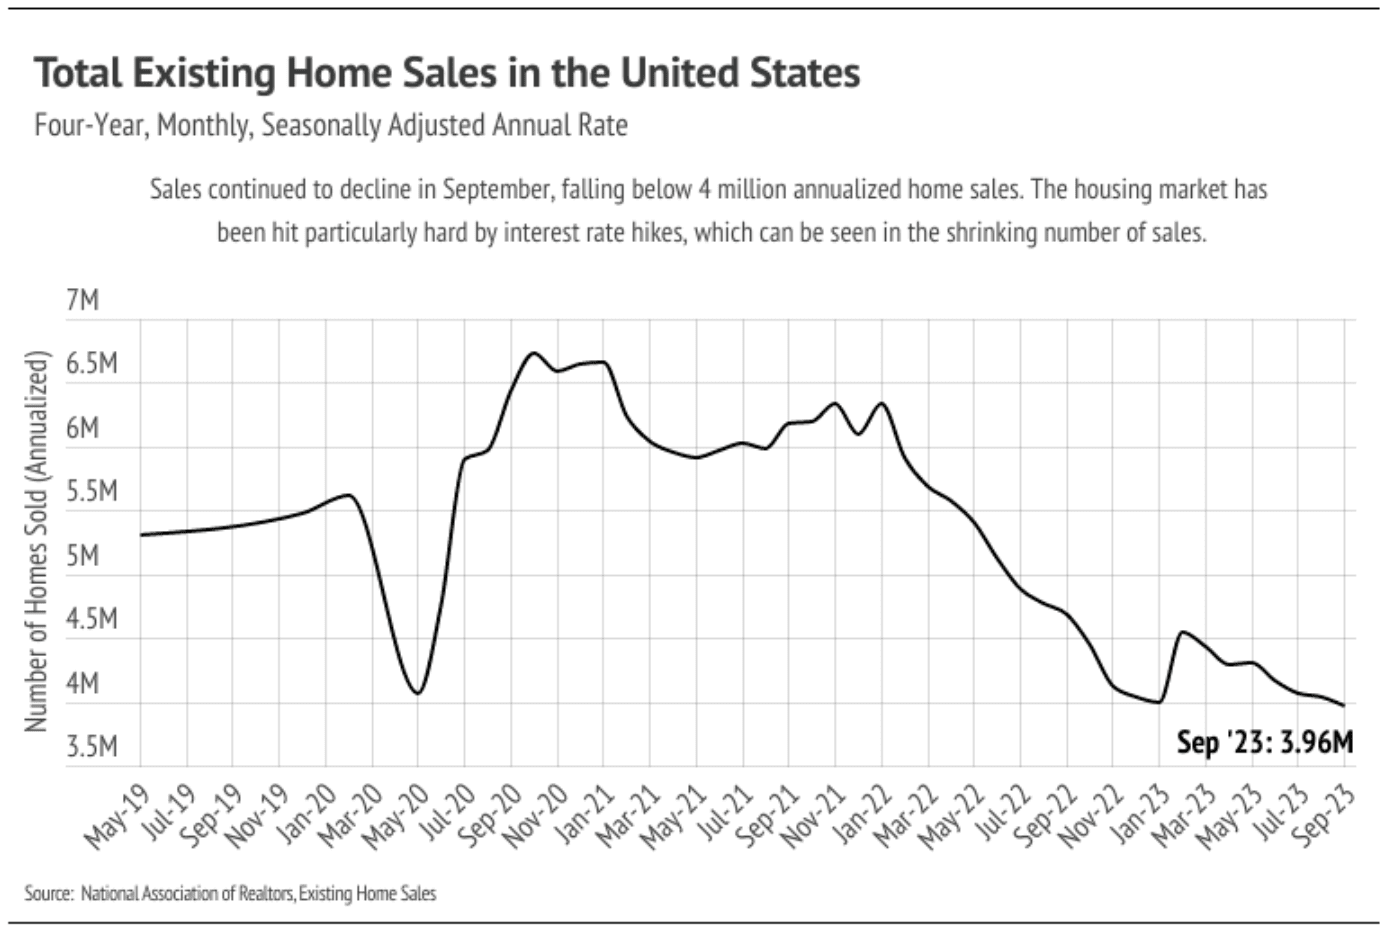
High mortgage rates aren’t going away anytime soon because inflation is still about twice as high as the Fed would like. So far, most of the economic slowing the Fed intended by raising rates seems to be isolated to the housing market. The National Association of Realtors (NAR) reported that the number of homes sold dropped 2.0% month over month and 15.4% year over year to the lowest number of sales in the four years that NAR reports. Real GDP rose significantly in Q3 2023, indicating strong U.S. economic growth rather than economic slowdown. It’s unlikely that the Fed will hike rates at the December meeting, and very unlikely that they will reduce rates in the near future. We can expect mortgage rates between 7% and 8% in 2024, which will continue to slow the market.
 
Different regions and individual houses vary from the broad national trends, so we’ve included a Local Lowdown below to provide you with in-depth coverage for your area. In general, higher-priced regions (the West and Northeast) have been hit harder by mortgage rate hikes than less expensive markets (the South and Midwest) because of the absolute dollar cost of the rate hikes and limited ability to build new homes. As always, we will continue to monitor the housing and economic markets to best guide you in buying or selling your home.
 

Big Story Data

Line chart of U.S. median existing-home prices, dipping in January 2023 before rising and declining by September.Chart of weekly 15- and 30-year mortgage rates, rising to October 2023 highs of 7.79% and 7.03%.Chart of U.S. real GDP from 2012 to 2023, with a sharp 2020 dip and a rising pre-pandemic trajectory line.Line chart of U.S. existing home sales, declining to 3.96 million in September 2023.Inflation chart comparing overall CPI, core CPI, and shelter CPI from September 2019 to September 2023.

Recent Blog Posts

Stay up to date on the latest real estate trends.
Living in Cow Hollow, San Francisco: A Guide to the Neighborhood Lifestyle

Michelle Kim  |  October 23, 2026

Explore life in Cow Hollow, from historic homes and boutique shopping along Union Street to neighborhood cafés, waterfront recreation, and the charm of everyday San Fr… Read more
Living in NoPa, San Francisco: A Guide to the Neighborhood Lifestyle

Michelle Kim  |  October 19, 2026

Explore life in NoPa, San Francisco, from classic Victorian homes and local dining on Divisadero Street to nearby parks, walkability, and neighborhood charm.
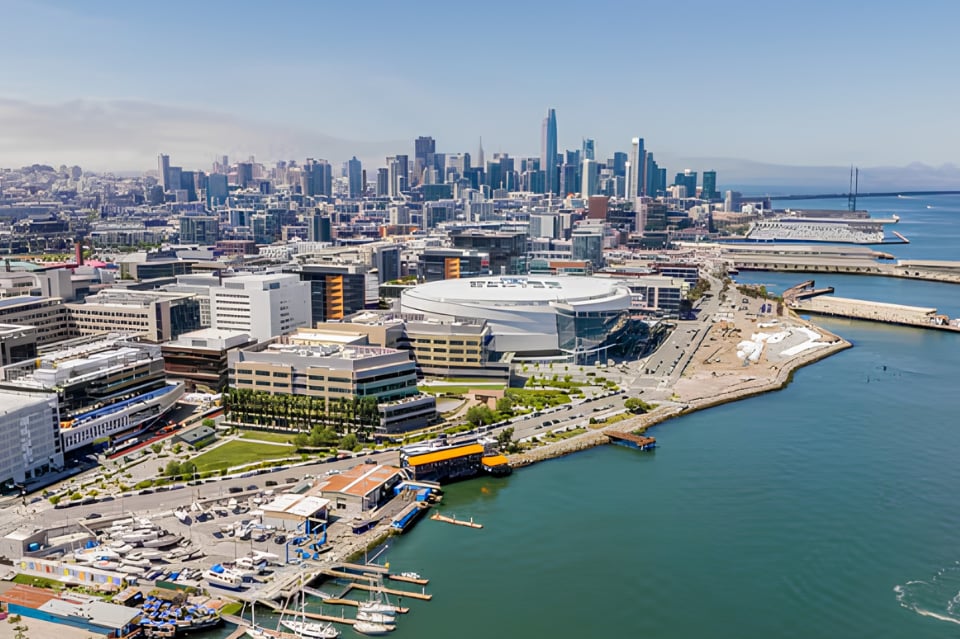
Aerial panorama of San Francisco's downtown skyline and waterfront along the bay.
Living in Mission Bay: A Guide to the Neighborhood Lifestyle

Michelle Kim  |  October 2, 2026

Explore life in Mission Bay, from waterfront parks and modern residences to dining, entertainment, outdoor recreation, and convenient city connections.

The Big Story Market Update
The Local Lowdown: September 2026

Michelle Kim  |  September 30, 2026

Quick Take: Median home sale prices slipped for the second straight month in August, falling to $429,100 from June's peak of $442,800, though they remain slightly abov… Read more
North Bay Market Update
The Local Lowdown: September 2026

Michelle Kim  |  September 30, 2026

Quick Take: Marin County dominated August, with the median single-family home selling for $1,778,000, a 15.83% jump over last August, while Sonoma, Solano, and Napa Co… Read more
East Bay Market Update
The Local Lowdown: September 2026

Michelle Kim  |  September 30, 2026

Quick Take: Single-family prices are holding firm year over year, with Alameda County up slightly and Contra Costa County up nearly 3%, while the condo picture has spl… Read more

We Would Love to Meet You!

You’ve got questions and we can’t wait to answer them.